
Story
S&P Upgrades Latam Airlines to 'BB+' on Strong Revenue and Cost Management
Summary
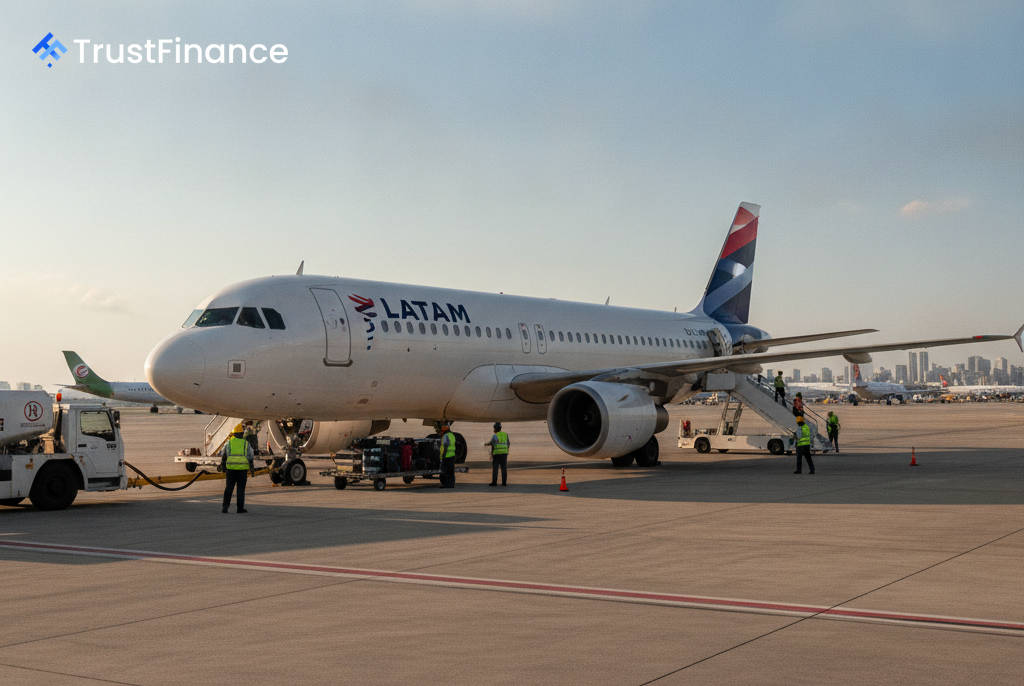
S&P Global Ratings has raised Latam Airlines Group's issuer credit rating to 'BB+' from 'BB', citing the carrier's robust financial performance and successful management of soaring fuel costs in the first half of 2026.
S&P Global Ratings has upgraded Latam Airlines Group S.A.'s (NYSE: LTM) issuer credit rating to 'BB+' from 'BB', reflecting the airline's strong performance despite significant market volatility. The ratings agency, in its September 21, 2026, announcement, also assigned a stable outlook to the new rating.
The Rating in Detail
The stable outlook is based on S&P's expectation that Latam's funds from operations (FFO) to debt ratio will remain above 45% through 2028. The agency also affirmed its 'BBB-' issue-level rating on the airline's senior secured notes due in 2030 and 2031, maintaining a '1' recovery rating on the debt.
This upgrade recognizes the company's resilience in the face of major operational headwinds. Notably, Latam successfully navigated an 80% year-over-year surge in all-in fuel prices during the first half of 2026.
Strong Financial Performance
Latam's ability to pass higher costs through to fares was a key factor in the decision. According to the S&P report, the airline's financial results for the second quarter of 2026 demonstrated this strength:
 Ad
- Passenger revenue increased by 27.9% year-over-year.
- Passenger revenue per available seat kilometer (a key industry metric) expanded by 17.5%.
Looking ahead, S&P projects that Latam's adjusted EBITDA will reach $4.3 billion in 2026, driven by a 9%-10% growth in available seat kilometers and load factors of approximately 84%. The ratings firm also anticipates positive free operating cash flow of around $1.3 billion in 2026 and $1.9 billion in 2027.
Capital Plans and Outlook
The airline is pursuing a significant fleet expansion, with plans for a net increase of 69 aircraft by 2028. S&P anticipates this will increase gross debt by $3.5 billion to $4.0 billion between 2025 and 2028, but expects the company's credit metrics to remain robust, with adjusted debt-to-EBITDA holding between 1.5x and 1.6x.
Latam has also balanced its growth investments with shareholder returns, recently approving a share repurchase program for up to 5% of its total shares over the next five years. S&P noted it expects the company to maintain a disciplined approach, in line with its financial policy targets of a net leverage ratio below 2.0x and a strong liquidity position.
Read next
More on Stocks
Tomi Environmental Stock Jumps 15% After Terminating Merger with Carbonium Core
Shares of Tomi Environmental Solutions (NASDAQ:TOMZ) surged in after-hours trading after the company and Carbonium Core Inc. mutually agreed to cancel their planned merger. Management expressed confidence in the company's standalone growth prospects.
Vicor Stock Surges After Doubling Q3 Revenue Growth Forecast on Patent Royalties
The power systems company more than doubled its sequential revenue growth forecast for the third quarter, citing new royalty income from its patented technology used in AI data centers.

Endava Shares Drop 10% After CFO Placed on Leave Amid Accounting Investigation
The technology services provider announced CFO Mark Thurston was placed on administrative leave pending an investigation into the accounting treatment of certain customer and supplier agreements.

MOEX Russia Index Slips 0.78% as Mining and Energy Stocks Decline
The Russian stock market closed lower on Monday, with the benchmark MOEX Index falling 0.78% due to widespread losses in the mining, oil and gas, and manufacturing sectors. The decline came as crude oil prices fell, while the Russian ruble remained stable.