
Story
Zalando Shares Plunge as Weak Organic Growth Undercuts Q2 Results
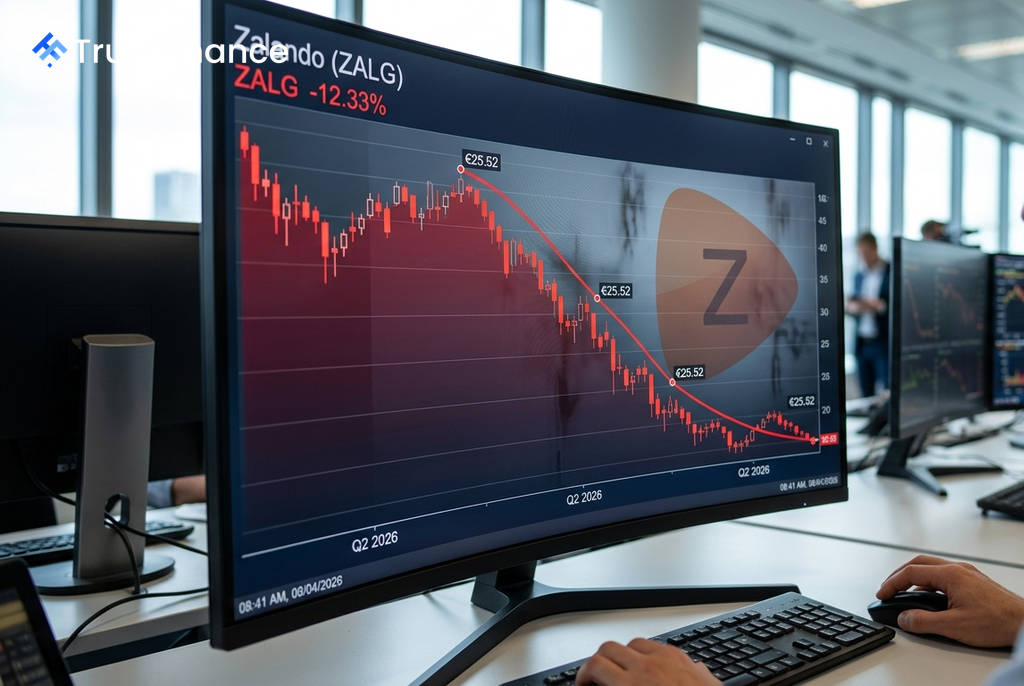
Shares in German online fashion retailer Zalando SE (ZALG) experienced their worst single-day drop in months, falling 12.33% to €25.52 after its second-quarter 2026 results disappointed the market. The report's headline figures were overshadowed by concerns about sluggish underlying performance once the impact of a recent acquisition was removed.
Results Mask Underlying Weakness
Zalando reported second-quarter revenue of €3.42 billion and an adjusted EBIT of €205 million, both of which fell short of analyst consensus estimates. While the company posted impressive reported Gross Merchandise Volume (GMV) growth of 20.7%, investors focused on the much weaker pro-forma figure.
When stripping out the effects of the ABOUT YOU acquisition, Zalando's pro-forma GMV growth was just 4.4%. This significant discrepancy between the headline and organic growth figures raised concerns about the health of the core business, leading to a sharp sell-off.
Guidance and Market Reaction
In response to the performance, Zalando refined its full-year forecast. The company now expects GMV and revenue growth to be in the lower half of its previously stated 12% to 17% range. The guidance for adjusted EBIT was narrowed to a range of €680 million to €720 million, from a previous €660 million to €740 million.
 Ad
The negative market reaction was amplified by the stock's recent performance; shares had gained approximately 25% in the three months leading up to the earnings release, suggesting elevated investor expectations.
A Mixed Operational Picture
Despite the headline disappointment, the earnings report contained some positive operational points. The company's Business-to-Business (B2B) segment showed significant strength, with its adjusted EBIT increasing by 257.7% to €41 million.
However, several challenges remain:
- The core Business-to-Consumer (B2C) segment experienced margin compression, falling to 5.3% from 6.7% in the prior year.
- Management noted weakness in the sneaker category, a key segment for the retailer.
- Synergies from the ABOUT YOU integration are reportedly ahead of schedule, but the acquisition is also contributing to lower overall margins and higher fulfillment costs.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.