
Story
Yili Group Q2 Profit Plummets 84% on Ausnutria Impairment Amid Growth Headwinds
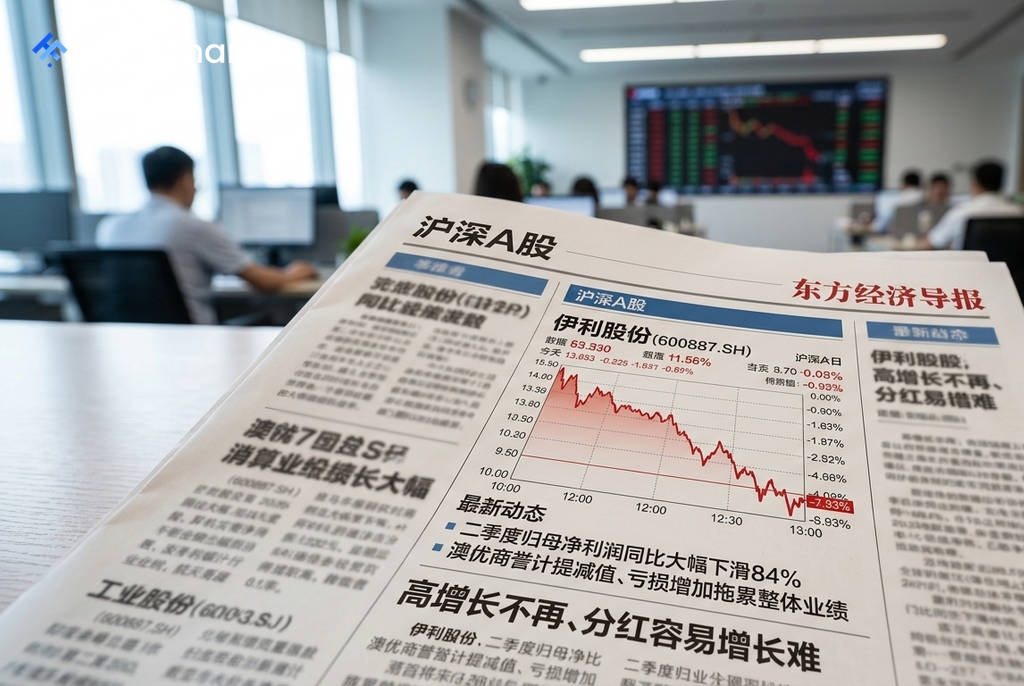
Inner Mongolia Yili Industrial Group (600887.SH) saw its net profit plunge 84% year-over-year in the second quarter of 2026, driven by a massive impairment charge related to a past acquisition. The development adds to investor scrutiny following a period of stagnant growth and a multi-billion yuan share sale by the company's chairman earlier this year.
Ausnutria Acquisition Weighs on Earnings
The sharp profit decline was primarily caused by significant writedowns associated with Ausnutria Dairy, a goat milk formula company Yili acquired in 2021. In its H1 2026 results, Yili booked a combined 2.46 billion RMB charge, consisting of a 1.55 billion RMB goodwill impairment and a 910 million RMB inventory provision for Ausnutria.
This accounting measure, while not a direct cash expense, reflects the deteriorating performance of the acquisition. For the first half of 2026, Yili's overall revenue grew a modest 4.13% on a low prior-year base, while net profit attributable to shareholders fell by 20%.
Core Business Segments Face Challenges
Yili's core business segments are navigating a difficult market, with performance varying across categories.
 Ad
- Liquid Milk: This segment, which accounts for roughly 70% of total revenue, has struggled with stagnation. After declining in 2024 and 2025, liquid milk revenue saw a marginal 1.3% increase in H1 2026, but growth was nearly flat in the second quarter, indicating that a stable recovery has not yet been established.
- Milk Powder: The acquisition of Ausnutria was intended to bolster this high-margin segment. However, Ausnutria's poor performance has become a drag, with its revenue falling 18.6% and swinging to a 705 million RMB loss in the first half. The impairment is intended to clear these historical burdens, allowing the segment to move forward.
- Ice Cream: The cold drinks business remains a relative bright spot where Yili holds a dominant market position. However, its performance has been volatile, and it has yet to surpass its 2023 peak.
Chairman's Share Sale and Strategy Shift
The weak financial results come at a sensitive time for the company. In March 2026, Chairman Pan Gang sold 61.99 million shares, cashing out 1.64 billion RMB. While the stated reason was to repay stock pledge loans, the move unsettled the market, which saw it as a lack of confidence amid slowing growth and a depressed stock price.
In recent years, Yili has shifted its strategic focus from aggressive top-line growth to improving profitability. The company has emphasized its target of achieving a net profit margin of 9-10%. This strategy supports a generous dividend policy, which has seen the company pay out nearly 59 billion RMB over the past decade. However, the latest earnings report highlights the significant operational challenges that remain in achieving this high-quality growth.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.