
Story
UBS Favors 3- to 5-Year Bonds for Income After Global Selloff
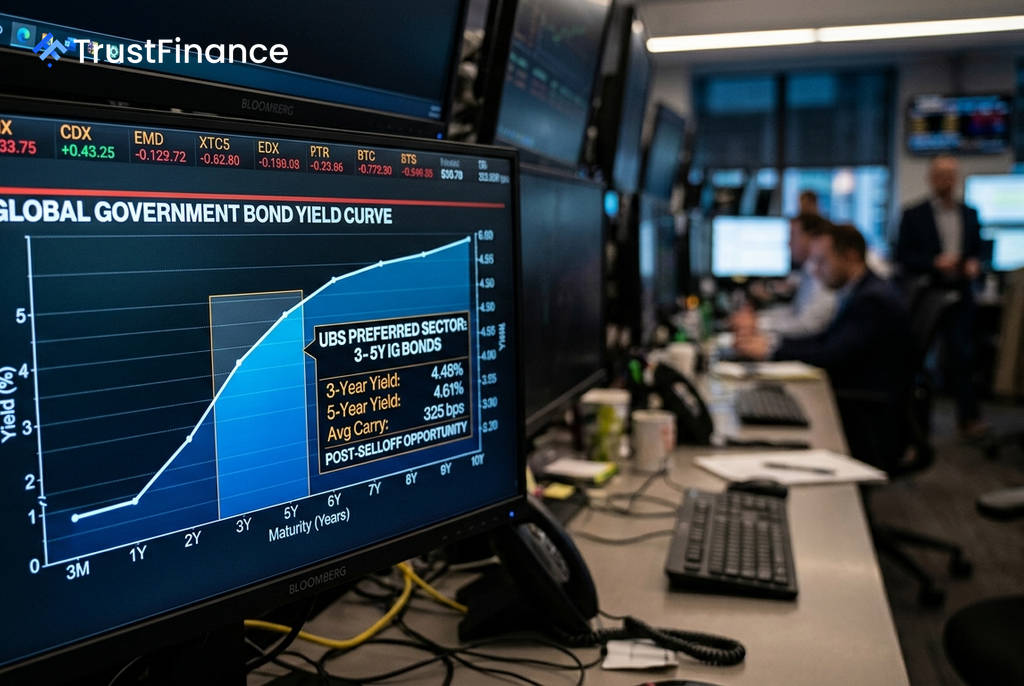
Following a global bond selloff, UBS strategists see more attractive opportunities to earn income, or carry, but are urging investors to avoid chasing higher yields in longer-dated debt. The bank recommends a defensive shift, favoring investment-grade bonds in the three- to five-year maturity range where the income potential is more favorable relative to the risk.
Caution on Long-Duration Debt
UBS has become more tactically cautious on duration after a sharp increase in interest-rate volatility and an aggressive bear flattening of global yield curves, according to a recent note. While credit spreads have remained relatively resilient, the bank highlights rising spread volatility in long-dated investment-grade and parts of the high-yield market as a sign of growing investor nervousness.
Several factors contribute to this cautious stance:
- Rising Treasury Yields: UBS identifies a U.S. 10-year Treasury yield approaching 5% as a critical threshold. A move beyond that level could make it difficult for credit markets to remain insulated from the rates selloff.
- Heavy Debt Issuance: An increasing supply of long-term debt, partly driven by large technology and infrastructure spending related to AI, is putting pressure on the market.
- Investor Demand: Investors are demanding more compensation for holding longer-maturity bonds due to the elevated interest-rate volatility.
Preferred Investment Strategy
 Ad
In this environment, UBS's model suggests a move up in quality and a focus on the middle of the curve. The bank's preferred positioning is to take profits in U.S. high-yield bonds and reallocate to global investment-grade credit, particularly in the three- to five-year sector.
UBS finds the European front-end particularly attractive after the recent repricing of monetary policy. U.S. investment-grade bonds in the same three- to five-year bucket also screen well, as their spread volatility is lower and their correlation with equities has decreased. The bank also stated a preference for cash over synthetic credit exposure and for European credit over U.S. credit.
Positioning Risks
Beyond market dynamics, UBS flagged that investor positioning itself is a potential risk. Exposure to credit from systematic investors like Commodity Trading Advisors (CTAs) is already stretched. The bank warned that a sudden pickup in volatility from negative headlines could force these investors to quickly cut their long positions, potentially accelerating a market downturn.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.