
Story
S&P Downgrades Flowers Foods to 'Junk' on Weak Bread Sales and Rising Leverage
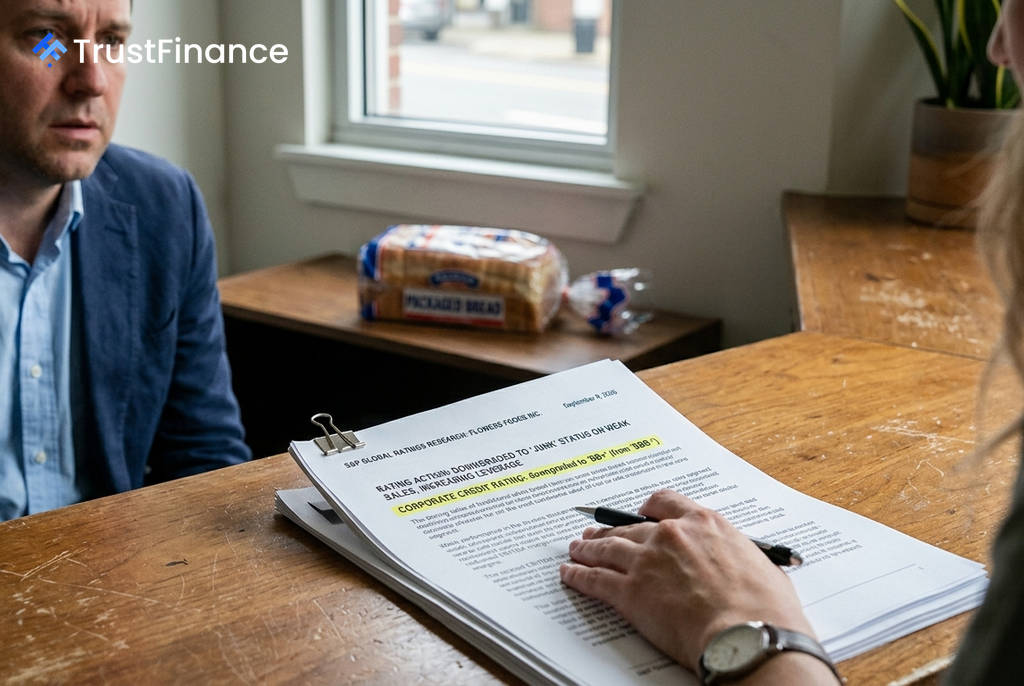
S&P Global Ratings has downgraded Flowers Foods Inc. (NYSE: FLO) to non-investment-grade status, citing weakening demand for its core packaged bread products, declining profits, and rising debt levels. The credit rating agency lowered its long-term issuer rating on the company to 'BB+' from 'BBB-', assigning a negative outlook.
The Downgrade Explained
The move to 'BB+', commonly referred to as speculative or "junk" grade, strips Flowers Foods of its investment-grade status, which can increase future borrowing costs. S&P also lowered its issue-level rating on the company’s senior unsecured notes to 'BB+' from 'BBB-'.
The negative outlook reflects the probability that S&P could lower its ratings again if the company cannot improve its financial metrics. According to the agency, this could happen if Flowers fails to restore its leverage to below 3x over the next 12 months.
Business Headwinds
The ratings action follows a period of significant underperformance. According to S&P, Flowers Foods reported a 4% year-over-year sales decline and an 18% drop in S&P Global Ratings-adjusted EBITDA in the second quarter of fiscal 2026. The core of the problem lies in its main product category, where volumes for fresh packaged breads fell 9.5% as consumers shift away from traditional loaf products.
 Ad
S&P stated that Flowers has lost market share to competitors like Lewis Bakeries and Grupo Bimbo, which the agency said have been quicker to innovate. As a result, S&P lowered its assessment of Flowers’ business risk profile to "fair" from "satisfactory," pointing to its concentration in declining categories and less product diversity than its investment-grade peers.
Financial Pressure and Outlook
The company's profitability has eroded, with its S&P-adjusted EBITDA margin declining by 200 basis points in the second quarter. The agency attributed the margin compression to lower sales volumes combined with increased costs for labor, freight, and marketing.
This has pushed the company's S&P-adjusted leverage up to 3.5x. In a move to address its balance sheet, Flowers announced in May 2026 that it would cut its dividend by 50% to prioritize debt reduction. S&P expects the company's profits will remain pressured and leverage elevated through fiscal 2027.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.