
Story
Seagate Reports Strong Q4 Earnings and Bullish Forecast on Surging AI Demand
Seagate Technology (NASDAQ: STX) reported fourth-quarter financial results that surpassed analyst expectations and provided a first-quarter forecast well above consensus, signaling that intense demand for data storage driven by artificial intelligence workloads continues to accelerate.
By the Numbers
The data storage company announced strong performance across key metrics for its fourth quarter of fiscal year 2026, extending a streak of significant earnings beats. The company also issued a robust outlook for the first quarter of fiscal year 2027.
- Q4 EPS: $5.71, a 12% surprise above consensus.
- Q4 Revenue: $3.63 billion, representing 48% year-over-year growth.
- Q4 Gross Margin: Reached 52.7% on a non-GAAP basis, an increase of 5.7 percentage points from the prior quarter.
- Q1 FY27 Guidance: The company projects earnings per share of $7.30 on revenue of $4.1 billion, approximately 24% higher than prior analyst estimates for EPS.
AI and Technology Driving Growth
Seagate attributed its performance to powerful, structural demand from data centers, which accounted for $2.9 billion, or 81% of its total sales, a 57% increase year-over-year. The company noted that its supply of nearline exabytes is largely allocated into calendar year 2028, indicating a long-term demand cycle.
 Ad
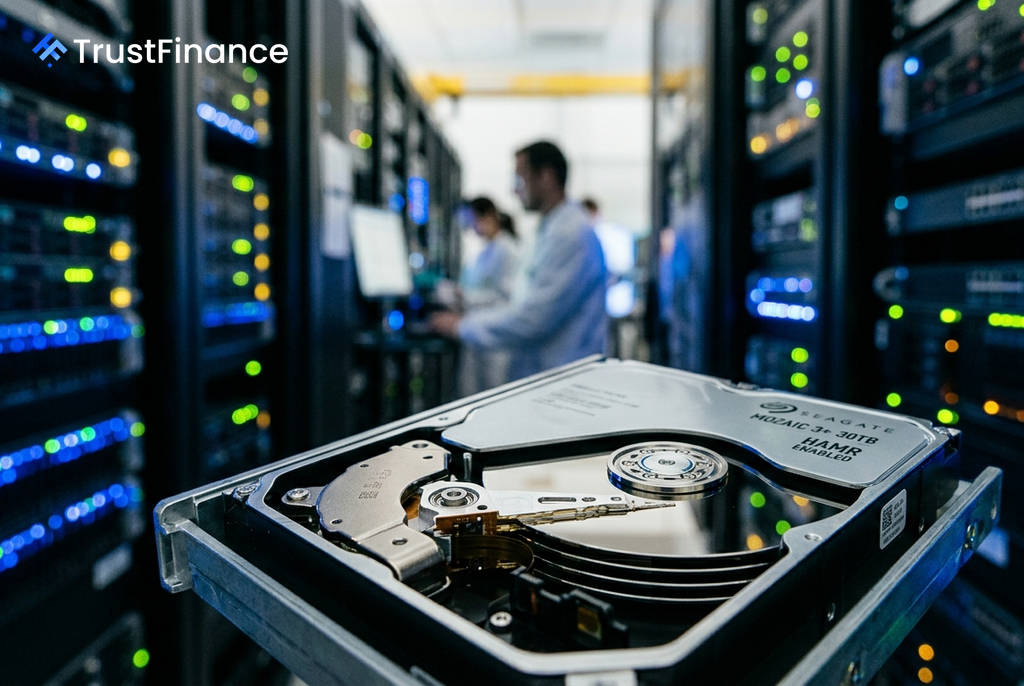
This growth is supported by the ramp-up of its Heat-Assisted Magnetic Recording (HAMR) technology, marketed as Mozaic. Its 30TB+ Mozaic 3+ drives have been qualified by major cloud providers, while revenue shipments of its 44TB+ Mozaic 4+ drives began in late March 2026. The technology allows for higher storage density at a lower cost per terabyte, directly boosting margins.
Outlook and Market Catalysts
Driven by strong profitability, Seagate's free cash flow for the full fiscal year 2026 reached $3.1 billion, enabling it to reduce its net debt to $1.9 billion from $4.2 billion a year prior. The company's net leverage now stands at a modest 0.4x.
Investors are watching several potential catalysts, including year-end contract renewals with major cloud service providers, which could lock in higher prices. The continued volume ramp of higher-capacity 44TB drives is also expected to improve the company's cost structure and expand margins further. However, risks include a potential slowdown in hyperscaler spending or any unforeseen issues with the adoption of HAMR technology. The stock has also seen a significant run-up of approximately 390% over the past 12 months.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.