
Story
Rovi H1 EBITDA Beats on One-Time Gain; Core Business Shows Mixed Results

Summary
The Spanish pharmaceutical firm's first-half earnings were significantly inflated by an acquisition gain, while revenue growth was driven by its manufacturing unit, offsetting weakness in its key heparin drug franchise.
Spanish pharmaceutical company Laboratorios Rovi SA (BME:ROVI) reported a significant beat on first-half earnings, though the result was heavily skewed by a one-time gain from an acquisition. Operating revenue for the period also surpassed estimates, driven by strong growth in its contract manufacturing division.
Headline Results Driven by Acquisition
Rovi's earnings before interest, taxes, depreciation, and amortization (EBITDA) for the first half of 2026 reached €121.1 million, far exceeding the consensus estimate of €54.1 million, according to its report on Thursday. The outperformance was primarily attributed to a €62.4 million bargain purchase gain related to its acquisition of the Phoenix manufacturing facility on April 1, 2026.
When adjusted for this non-recurring item, the company's underlying EBITDA showed a 10% decrease. Total operating revenue for the first six months grew 9.4% to €344.2 million, beating analyst forecasts of €325.4 million.
Contrasting Divisional Performance
The company's revenue growth was anchored by its Contract Development and Manufacturing Organization (CDMO) business, where sales surged 38% year-over-year to €106.3 million. This was boosted by existing business, new revenue from Bristol Myers Squibb, and a contribution of approximately €45 million from the newly acquired Phoenix facility.
 Ad
In contrast, the Specialty Pharma division saw flat revenue at €238 million. Key points include:
- Okedi: Sales of the schizophrenia treatment rose 27% to €34 million.
- LMWH: The heparin franchise continued to face headwinds, with sales falling 5% to €125 million due to international partner destocking and pricing pressures.
Outlook and Investment
Rovi maintained its full-year guidance, forecasting low-to-mid single-digit growth in operating revenue. However, the company expects challenges in its heparin business to persist, projecting a mid-single-digit percentage decline in LMWH sales for the full year.
The company also reported a 98% increase in research and development expenses to €33.3 million. Rovi attributed the higher spending to preparations for a Phase III clinical trial of its Letrozole SIE drug, which is scheduled to begin in the third quarter of 2026.
Read next
More on Stocks
Taiwan Weighted Index Closes 0.25% Lower on Sector Weakness
Taiwan's benchmark stock index ended Thursday's session in negative territory, weighed down by losses in the biotech and cement sectors. The decline came despite several individual stocks reaching new all-time highs.
RBI Reportedly Conducts $10 Billion in Currency Swaps to Drain Liquidity
The Reserve Bank of India has carried out at least $10 billion in sell-buy currency swaps in recent weeks to absorb a record cash surplus in the banking system, according to a Bloomberg report.
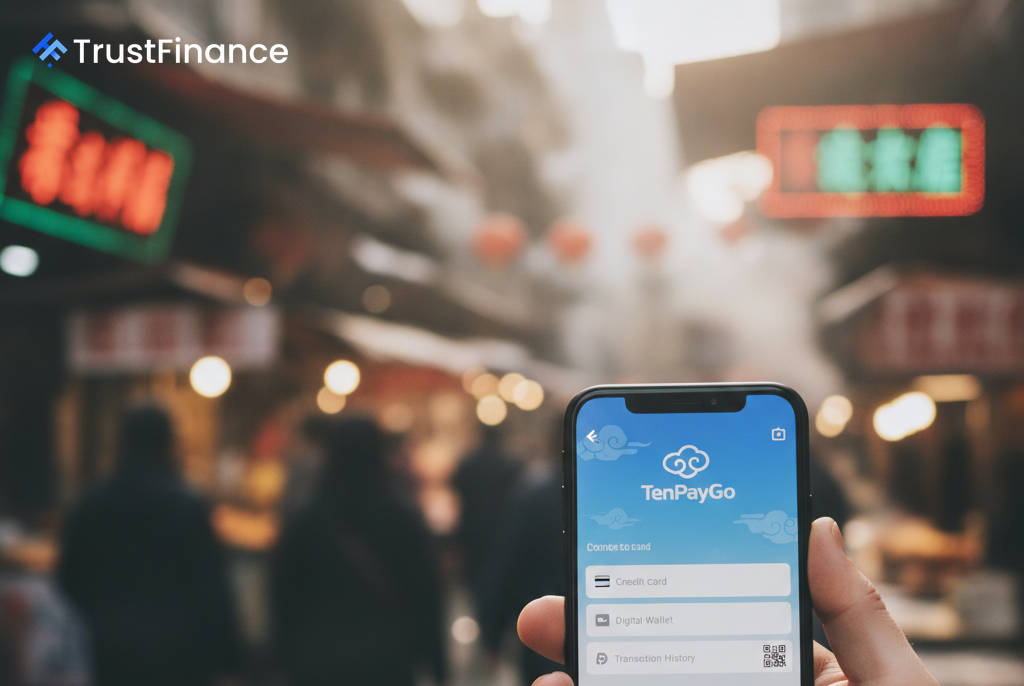
Tencent Launches TenPayGo App to Simplify Mobile Payments for Foreign Visitors in China
The new app, TenPayGo, allows international travelers to link foreign credit cards and digital wallets for use across the vast WeChat Pay network, aiming to capture a growing inbound tourism market.
Mitchells & Butlers Reports Q4 Sales Growth, Expects FY26 Results to Meet Consensus
The U.K. pub and restaurant operator announced a 1.4% rise in like-for-like sales for the fourth quarter and projected that cost pressures would ease in the upcoming fiscal year.