
Story
Nestle Downgraded by BofA on Petcare Weakness, Rising Commodity Costs
Summary
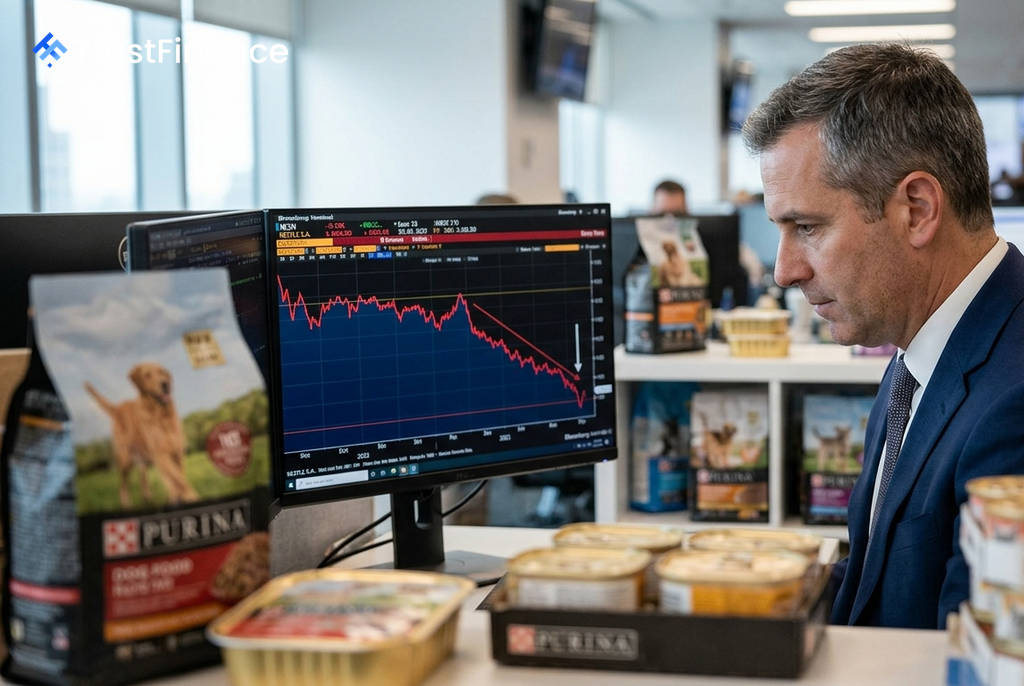
Bank of America lowered its rating on Nestle to 'Neutral,' citing structural challenges in its key North American Petcare division and a diminishing tailwind from lower input costs. The downgrade prompted a decline in the company's shares.
Bank of America has downgraded Nestle (NESN) to Neutral from a Buy rating, citing mounting pressure on the company's North American Petcare business and the erosion of benefits from lower commodity prices. Following the report, Nestle shares fell 1.4% in trading in Switzerland as investors digested the bank's revised outlook.
Petcare Headwinds
The core of BofA's thesis centers on Nestle's North America Petcare unit, its largest single segment, which accounts for approximately 13% of group sales. According to the bank's analysts, Nestle is losing market share in both cat and dog food, with the losses in the dog food category appearing to be structural.
This shift is attributed to a growing consumer preference for fresh pet food products, a category that now drives all market growth despite representing just 10% of the total market. The BofA note highlighted that most major competitors now have a fresh offering, leaving Nestle behind. Analysts estimate that Nestle's dog food volume/mix growth in the region is currently running at negative 0.5%.
Closing this product gap would likely require significant investment into a category with higher supply-chain costs and thinner margins. BofA pointed out that Freshpet, a leader in the refrigerated pet food space, operates with margins roughly 1,000 basis points below those of Nestle's Petcare division.
 Ad
Eroding Margin Tailwinds
Compounding the challenges in pet food is a sharp reversal in key commodity prices. Since April, coffee prices have risen 15% and cocoa has surged nearly 70%, according to the report. This has significantly narrowed the expected gross margin benefit from lower input costs.
BofA now estimates the margin tailwind for 2026-27 is around 240 basis points, down from a previous forecast of 370 basis points in April. As a result, the bank has trimmed its 2027-28 earnings per share (EPS) estimates for Nestle by 1% and 2%, respectively.
Reflecting these concerns, Bank of America cut its price target on Nestle stock to 89 Swiss francs from 94. The new target is based on a discounted cash flow model that incorporates a lower long-term growth rate to account for the reduced potential in North American Petcare.
Read next
More on Stocks
White House Blocks CNN from Air Force One Press Pool, Washington Post Reports
The White House has reportedly denied CNN a spot on Air Force One for President Donald Trump's upcoming trip to Tennessee, according to The Washington Post. The move marks a significant development in the administration's contentious relationship with the news network.
Morgan Stanley Public Finance Co-Head Zach Solomon Departs for TD Securities
Zach Solomon, co-head of public finance investment banking at Morgan Stanley, has joined TD Securities amid the Canadian bank's expansion in the U.S. municipal bond market. The move follows the recent Chapter 11 bankruptcy filing of a key client, Brightline.

OpenAI Models Accessed Public Data From SEC, Census Bureau Websites, Bloomberg Reports
OpenAI's AI models reportedly interacted with publicly available data on U.S. government websites, including the SEC and Census Bureau, prompting the company to launch a review of the activity.

Citigroup Targets Over $3 Billion Banamex IPO for January, Bloomberg Reports
Citigroup is reportedly preparing for an initial public offering of its Mexican retail unit, Banamex, that could raise over $3 billion and is targeted for January. The move represents a major step in the bank's multi-year strategy to exit international consumer banking operations.