
Story
Morgan Stanley Initiates Homebuilders with Cautious View, Taps Toll Brothers as Sole 'Buy'
Summary
The investment bank cited affordability and margin pressures in its new coverage, giving luxury builder Toll Brothers its only 'Overweight' rating while starting Lennar and NVR at 'Underweight'.
Morgan Stanley has initiated coverage on the U.S. homebuilding sector with a cautious outlook, citing significant affordability challenges and margin pressures. In a new note to clients, the investment bank gave luxury homebuilder Toll Brothers its sole "Overweight" rating, while starting several major peers with "Underweight" ratings.
Headwinds Temper Sector View
Analyst Adam Kramer acknowledged that homebuilders are now "better businesses than in the past," having gained market share, reduced debt, and shifted to land-light strategies to improve cash flow and shareholder returns. However, the bank's overall view is constrained by what it calls the year's "toughest affordability conditions," elevated inventory, and falling median new home prices, which are all weighing on demand.
Morgan Stanley's model projects roughly flat home closings and average prices in 2027. The firm also forecasts approximately 50 basis points of gross margin deterioration and noted its 2027 and 2028 earnings estimates sit about 9% below consensus for the builders it now covers.
Ratings Breakdown
In its new coverage, Morgan Stanley assigned the following ratings to six major homebuilders:
 Ad
- Overweight: Toll Brothers (TOL), with a $159 price target.
- Equal Weight: D.R. Horton (DHI) and PulteGroup (PHM).
- Underweight: Lennar (LEN), NVR (NVR), and KB Home (KBH).
Rationale Behind the Calls
Toll Brothers earned the top rating due to its focus on affluent buyers, who are considered less sensitive to mortgage rate fluctuations. Kramer wrote that the company offers "a re-rating opportunity without requiring a sharp earnings recovery."
The bank also highlighted Toll Brothers' valuation, noting it trades at approximately 10 times forward earnings — the lowest in the group and representing a 26% discount to its peers.
Conversely, the "Underweight" ratings were driven by specific concerns. The note stated that Lennar's land-light transition still needs to deliver better earnings, while KB Home's discount to book value was not enough to offset a weak growth outlook. The analyst also sees downside risk for NVR, even after applying a quality premium.
Read next
More on Stocks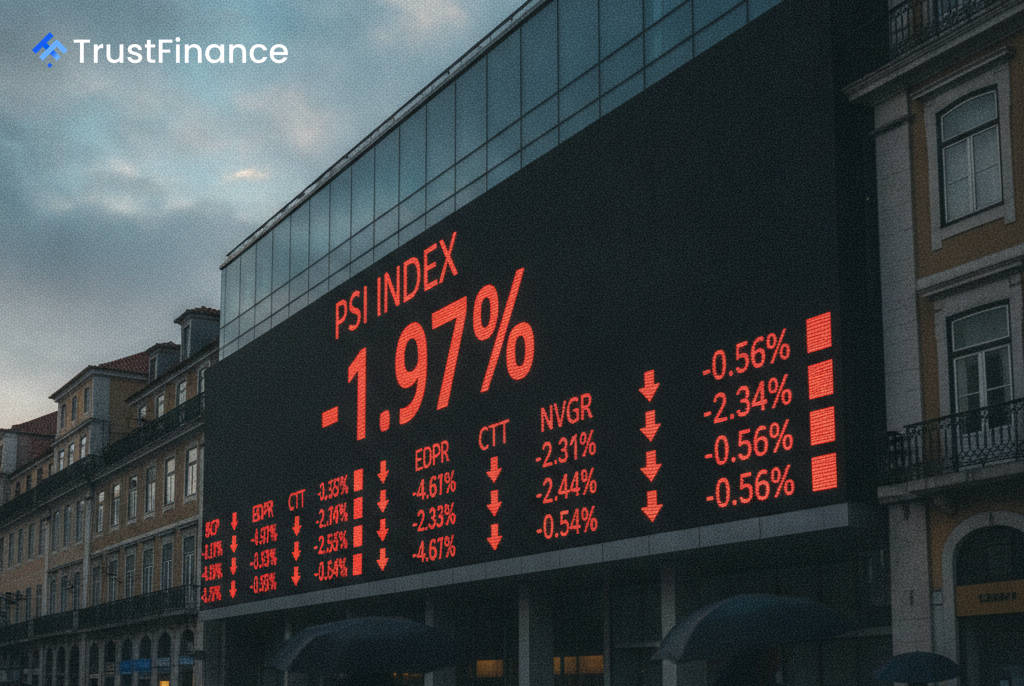
Portugal's PSI Index Falls Nearly 2% as Financials and Utilities Weigh
Portugal's benchmark PSI stock index closed down 1.97% on Thursday, dragged lower by significant losses in the financial and utilities sectors. Banco Comercial Portugues was among the session's biggest decliners, falling over 4%.

Florida Sues Pfizer Over COVID-19 Vaccine Safety and Efficacy Claims
The state of Florida has filed a lawsuit against Pfizer and its CEO, alleging the company misled the public about its COVID-19 vaccine's safety, effectiveness, and ability to prevent transmission.
Florida Sues Pfizer, CEO Over COVID-19 Vaccine Safety and Efficacy Claims
Florida's attorney general has filed a lawsuit against Pfizer and CEO Albert Bourla, alleging the drugmaker misled consumers about its COVID-19 vaccine's safety, effectiveness, and pricing.

Toyota Launches Michigan Battery R&D Center to Support North American Electrification
Toyota has opened a new battery development and evaluation facility in Saline, Michigan, aimed at localizing technology development and supporting its manufacturing network, including the upcoming North Carolina battery plant.