
Story
Jefferies Upgrades Energean to 'Hold' on Improved Risk-Reward Outlook
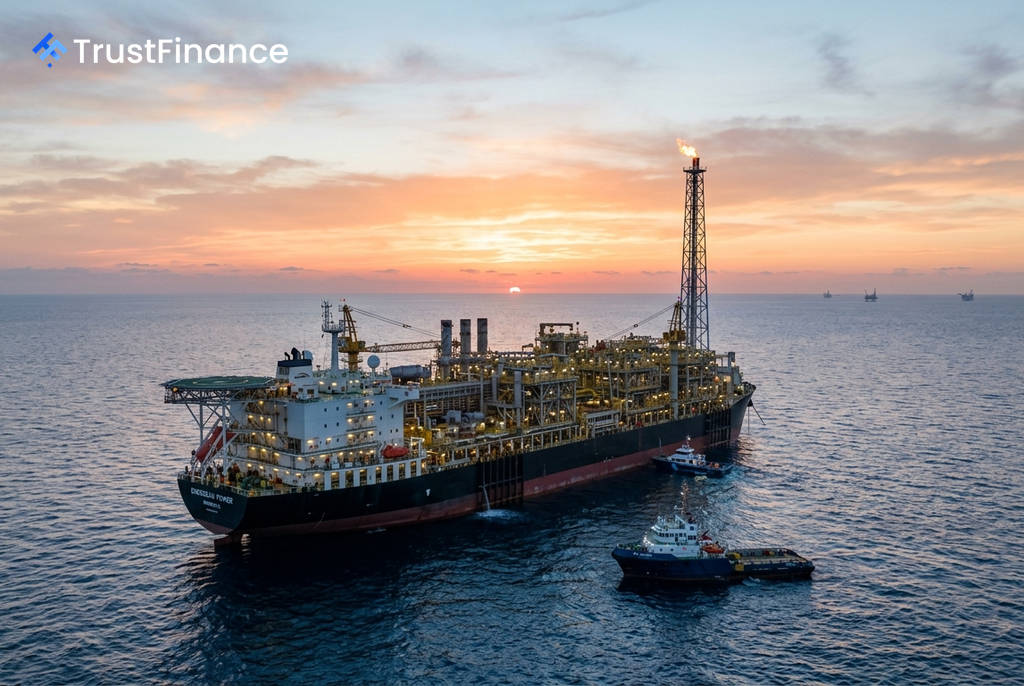
Jefferies has upgraded UK-based energy producer Energean to "Hold" from "Underperform," citing an improved risk-reward profile following the stock's weakness year-to-date. In a note to clients, the investment bank raised its price target on the London-listed shares by 18% to 800 pence.
Rationale for the Upgrade
Jefferies described Energean as "something of an anomaly" among exploration and production companies in 2026, noting its share price has declined despite a backdrop of strengthening commodity prices. The brokerage attributed this disconnect to Energean's production mix.
An estimated 63% of the company's projected 2026 output of 134,000 barrels of oil equivalent per day (boe/d) is linked to fixed-price gas contracts for domestic use in Israel. This structure has limited the stock's sensitivity to the rally in global energy markets, but Jefferies now sees a more balanced valuation after the underperformance.
Updated Valuation and Debt Forecast
The upgrade is supported by a significant revision to Jefferies' financial model. The bank increased its net asset value (NAV) estimate for Energean by 52% to 910 pence per share. This change was driven by updated modeling for Israel-specific taxes, which pushed out the impact of the Sheshinski levy, and the incorporation of higher oil price assumptions.
 Ad
Jefferies projects that Energean's year-end 2026 net debt will reach $3.5 billion, slightly above the consensus estimate of $3.4 billion and the company's guidance of $3.25 billion to $3.35 billion. The higher debt forecast reflects continued investment in the development of its key Karish gas field offshore Israel.
Operational Outlook
Investors are awaiting Energean's interim results on September 9 for updates on operations and strategy. The company revised its 2026 production guidance down in May to a range of 130,000 to 140,000 boe/d, following a 41-day suspension at the Karish field due to geopolitical tensions. At the same time, it raised its capital expenditure guidance for the year to a range of $800 million to $860 million.
Looking ahead, Jefferies anticipates that capital expenditures will fall materially in 2027 as major projects are completed. Production is expected to grow year-on-year, aided by the commissioning of a second oil train on the Karish floating production vessel in July, which boosted liquids processing capacity to 31,000 barrels per day.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.