
Story
Disney Stock Could Rise 40% by Exiting Streaming, Wells Fargo Says
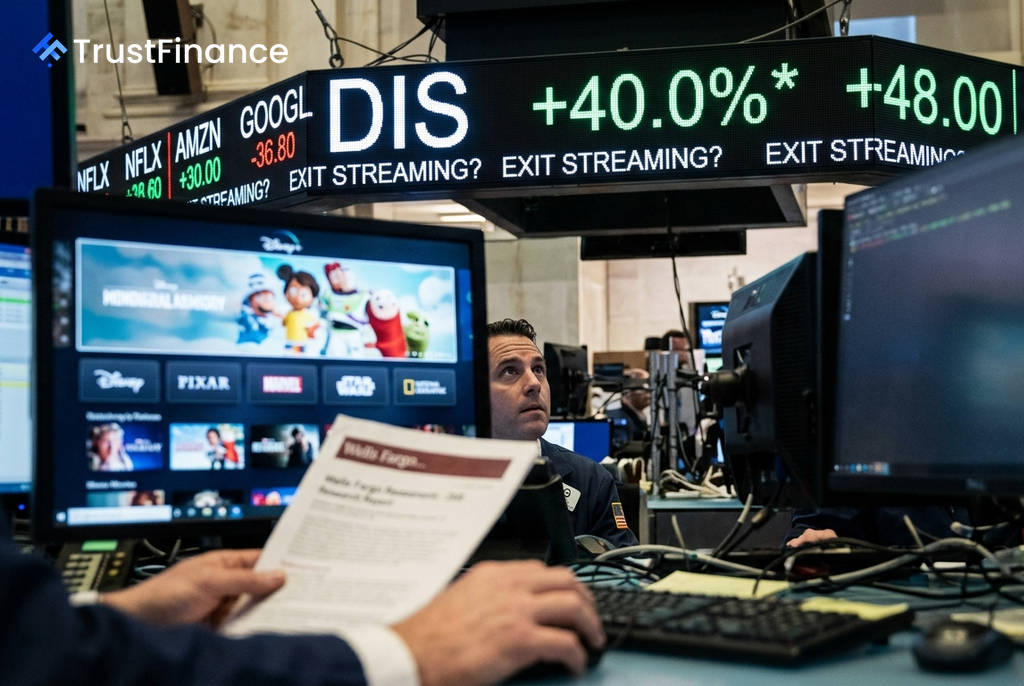
A Wells Fargo analyst has proposed a radical strategic shift for The Walt Disney Company, arguing the media giant could unlock a 40% increase in its stock price by exiting the direct-to-consumer (DTC) streaming business. The contrarian thesis suggests Disney should abandon the costly distribution model of Disney+ and revert to its historical role as a pure content producer and licensor.
A Return to Licensing
In a research note, Wells Fargo analyst Steven Cahall challenged the prevailing industry view that media companies must own their distribution channels. He argued that Disney's multi-year stock de-rating is directly tied to the financial strain of competing in the "engagement wars" against digital natives like Netflix and YouTube.
Instead of continuing to burn cash on its streaming service, Cahall suggests Disney could generate more reliable, high-margin revenue by licensing its vast library of content to other platforms. "We lay out the case for DIS to return to its old biz model of producing vs. distributing," the note stated, adding it would de-risk earnings and sharpen management's focus on intellectual property and its Experiences segment.
The Financial Case
The analyst projects that a shift back to a wholesale licensing model could generate significant returns for Disney. The note included several key estimates:
 Ad
- Potential annual licensing revenues could exceed $15 billion by fiscal year 2028.
- This could add an estimated 10% to earnings per share, pushing it above $9 per share.
- Citing Sony's lucrative movie deals, the note estimated Disney could command nearly $4 billion for its global "pay 1" movie window alone, given its box office dominance.
Cahall contrasted this potential with the low 13% operating income margin projected for Disney's DTC business by fiscal year 2027. The note also asserted that licensing content to services like Netflix or Amazon Prime would cause "zero damage" to Disney's brand, box office performance, or theme park attendance.
Market Outlook
While outlining this long-term, bullish scenario, Wells Fargo lowered its near-term price target on Disney stock from $146 to $125, citing macroeconomic pressures and adjustments to box office forecasts. The bank maintained its "Overweight" rating on the stock.
The note represents a significant departure from typical Wall Street analysis, which tends to focus on incremental metrics like subscriber growth and average revenue per user (ARPU). Cahall's thesis questions the fundamental strategic pivot Disney made in 2019, suggesting that being an asset-light IP powerhouse is a more viable path to shareholder value than competing as a tech-distribution company.