
Story
Circle Receives Conflicting Analyst Ratings: Morgan Stanley Downgrades to Underweight, TD Cowen Initiates at Buy
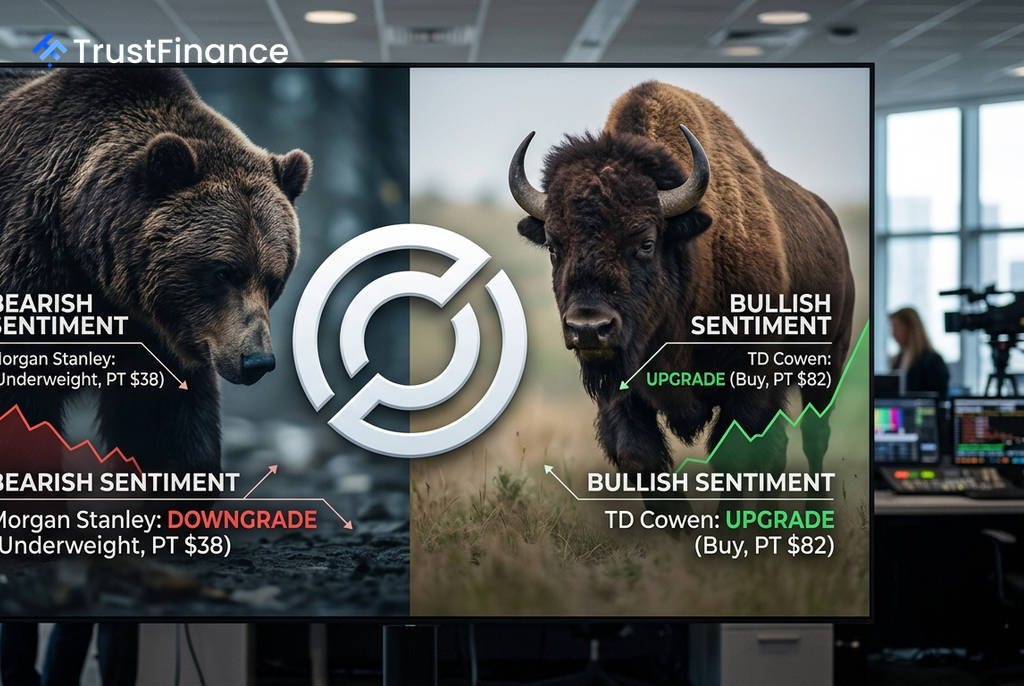
Circle Internet Group faced sharply divergent analyst opinions on Monday, as Morgan Stanley downgraded the stablecoin issuer to Underweight, citing competitive threats, while TD Cowen initiated coverage with a Buy rating, highlighting the company's underappreciated platform ambitions.
The Bear Case: Morgan Stanley's Downgrade
Morgan Stanley cut its rating on Circle to Underweight from Equal-weight and slashed its price target to $38 from a previous $106. The firm's rationale centers on slowing growth for Circle's core USDC stablecoin, rising competitive pressures, and concerns that a planned shift toward transaction-based revenue will be slower and less profitable than the market anticipates.
According to the bank's note, analysts reduced their USDC circulation forecasts by approximately 33% for 2027 and 44% for 2028. This led to earnings estimates that are about 20% below the Wall Street consensus for 2028. Morgan Stanley warned that stablecoin usage remains concentrated in crypto trading and that new threats are emerging from tokenized money market funds, tokenized bank deposits, and consortium-backed initiatives like OpenUSD.
The Bull Case: TD Cowen's Buy Initiation
In a starkly contrasting view, TD Cowen initiated its coverage of Circle with a Buy rating and an $82 price target. The firm argued that investors are overly focused on Circle's reserve-income business, which profits from interest on its USDC reserves, and are overlooking its evolution into a broader digital financial infrastructure provider.
 Ad
TD Cowen's thesis is built on Circle's potential in payments, treasury services, tokenized assets, and developer tools. The bank projects that USDC circulation will grow at a compound annual rate of roughly 31% through 2030 and believes new fee-generating products will reduce the company's long-term dependence on interest rates.
A Tale of Two Theses
The opposing ratings create a clear debate for investors. Morgan Stanley's outlook is rooted in the challenges facing Circle's current, dominant business model, which relies on income from USDC reserves. The downgrade suggests significant headwinds that could erode its market position and profitability.
Conversely, TD Cowen's bullish case looks beyond the present model, betting that Circle's strategic pivot to a diversified, fee-based financial platform will unlock significant future value. The firm pointed to potential catalysts including greater regulatory clarity and increased institutional adoption, while acknowledging risks from lower interest rates and competition from bank-issued stablecoins.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.