
Story
CICC Reaffirms 'Outperform' on China Resources Land, Sees 61% Upside
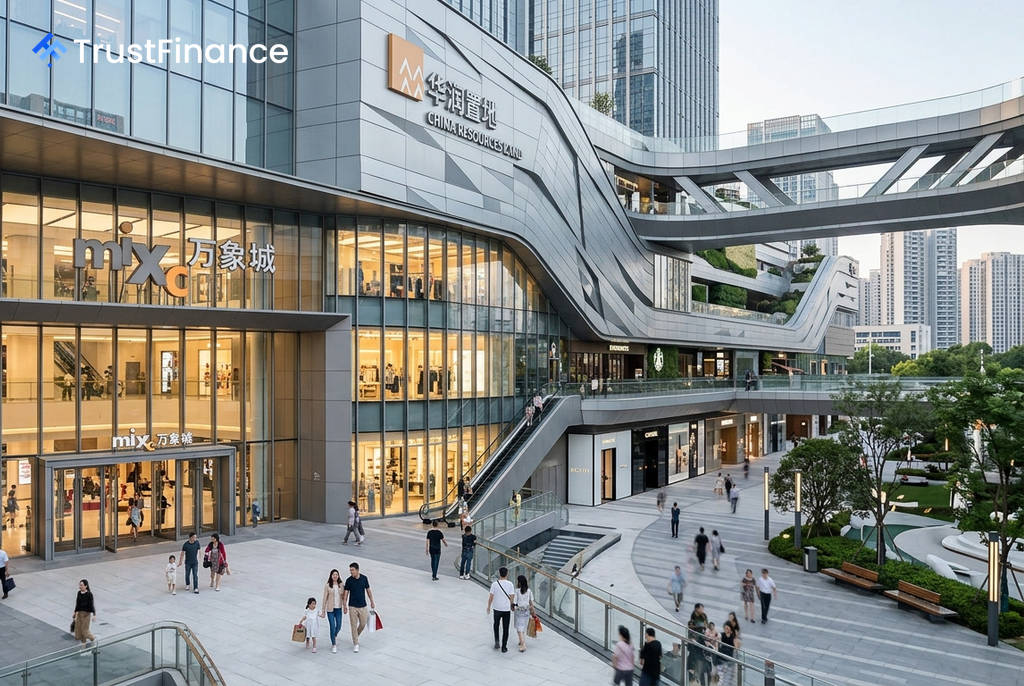
China International Capital Corporation (CICC) has reaffirmed its 'Outperform' rating for property developer China Resources Land (01109.HK), maintaining a price target of HK$46.7 per share. In a research note, the bank highlighted the company's resilient core business and steady growth in other segments, suggesting the stock presents a potential investment opportunity once market sentiment stabilizes after a recent sector-wide correction. The price target implies a potential upside of 61% from the stock's current level.
First-Half Results in Line with Expectations
According to CICC, China Resources Land's first-half 2024 performance met the bank's forecasts. The company reported a 2% year-over-year increase in core net profit to ¥10.16 billion, even as total revenue declined 29% to ¥67.9 billion. The revenue dip was primarily attributed to a 39% drop in development property sales, which was partially offset by a 17% increase in rental income from its investment properties.
The developer's settlement gross margin improved by 1.4 percentage points to 25.4%, driven by changes in the mix of properties sold. The company maintained its interim dividend at ¥0.20 per share, unchanged from the previous year.
Financial Stability and Segment Strength
CICC's report emphasized the developer's sound financial position, a key differentiator in China's challenged real estate market. The bank noted several key metrics:
 Ad
- The net gearing ratio stood at a healthy 41.0%.
- The weighted average financing cost was just 2.63%, having decreased by 9 basis points from the start of the year.
- Interest-bearing debt fell by 3.7% from the beginning of the year to ¥271.2 billion.
China Resources Land's core property development business, its 'first growth curve', demonstrated resilience with contracted sales rising 6% year-over-year to ¥116.5 billion, outperforming many of its peers. Meanwhile, its 'second curve'—investment properties like shopping malls—showed strong momentum, with rental income growing 19.4% to ¥12.44 billion, significantly outpacing broader retail sales growth.
Outlook and Risks
Looking ahead, CICC believes the company is well-positioned to maintain its top-three market share in sales, supported by an ample land bank with approximately ¥500 billion in unsold value. The bank kept its earnings forecasts for 2024 and 2025 unchanged.
However, the report also identified potential risks to its outlook. These include a greater-than-expected downturn in the new housing market and rental growth from its investment property portfolio falling short of projections.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.