
Story
CICC Lifts China Merchants Port Target to HK$18 on Strong Revenue Growth
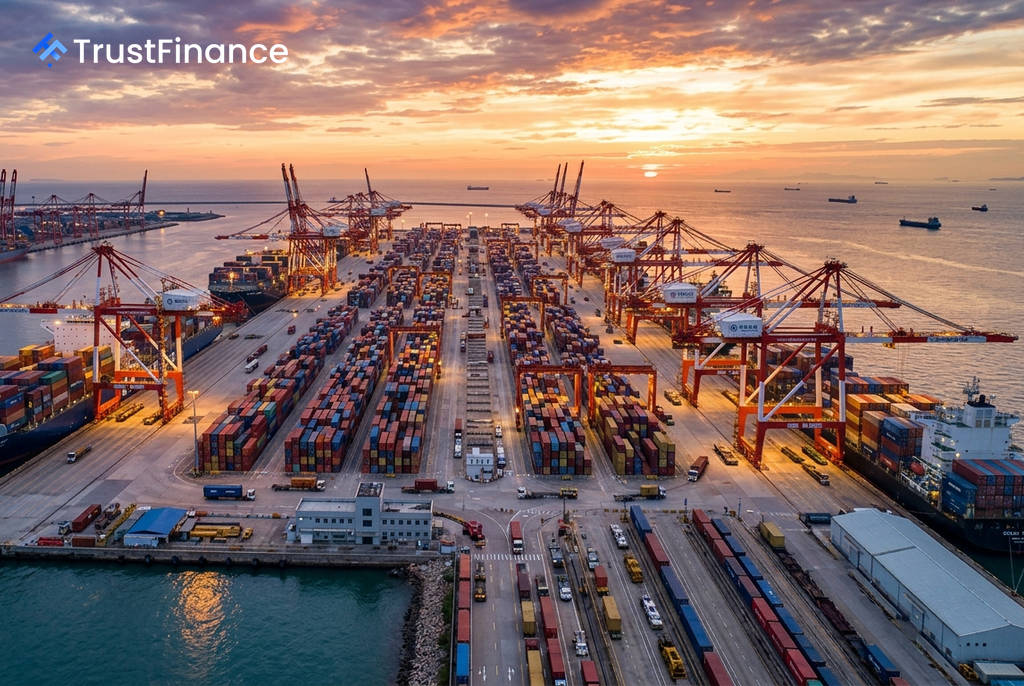
China International Capital Corporation (CICC) has raised its price target for China Merchants Port Holdings Co., Ltd. (00144.HK), signaling increased confidence in the port operator's earnings potential. The investment bank affirmed its "Outperform" rating on the stock while lifting the target price by 9.1% to HK$18.00 per share.
Analyst Revisions
In a research note, CICC attributed the upgrade to stronger-than-expected revenue per container in the first half of the year. The new price target implies a potential upside of 9.7% from the stock's current price and corresponds to a price-to-earnings (P/E) ratio of 9.7x for 2024 and 9.0x for 2025.
Following the company's recent performance, CICC adjusted its financial forecasts:
- 2024 Revenue: Increased by 3.42% to HK$14.25 billion.
- 2024 Net Profit: Maintained, as stronger core port performance was offset by losses from non-core equity investments in the first half.
- 2025 Net Profit: Raised by 7.37% to HK$8.42 billion, on expectations of continued growth in container volume and revenue per unit.
Strong First-Half Performance
 Ad
The revision follows China Merchants Port's report of solid first-half results, which CICC noted beat its expectations. The company posted revenue of HK$7.30 billion, a year-over-year increase of 13.0%, and a net profit attributable to shareholders of HK$3.83 billion, up 6.9%.
Operationally, total container throughput at terminals where the company has an interest rose by 4.5% year-over-year. CICC highlighted that revenue growth from the core port business significantly outpaced the 3.5% volume increase at its controlled terminals, indicating improved terminal fees and a more favorable cargo mix.
Outlook and Risks
Looking ahead, CICC expects the company's cargo volumes to maintain healthy growth. Key drivers identified in the report include increased shipments of AI-related products, rising exports of high-end Chinese manufactured goods, and sustained economic growth in emerging markets.
The bank also sees potential for further profitability gains through operational efficiencies, increased automation, and disciplined cost controls. However, CICC cautioned that its outlook is subject to risks, including geopolitical shifts and a potential slowdown in the global economy.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.