
Story
Analysts Bullish on Hut 8's AI Pivot, Citing Over $19B in Leases
Summary
Hut 8 Corp. is transitioning from a Bitcoin miner to an AI data center provider, securing over $19 billion in lease commitments. Wall Street analysts are overwhelmingly positive on the stock's long-term potential, despite current unprofitability and significant debt.
Hut 8 Corp. (HUT) is executing an aggressive strategic pivot from its origins as a Bitcoin miner to an artificial intelligence-focused data center and energy infrastructure operator. The move has garnered significant support from Wall Street, with the company securing over $19 billion in combined lease commitments that underpin a bullish long-term outlook.
A Strategic Pivot to AI Infrastructure
The company's transformation is anchored by several large-scale, long-term agreements with major technology players. These deals highlight a strategic shift to capitalize on the immense power and infrastructure demand driven by the AI boom.
Key developments fueling this strategy include:
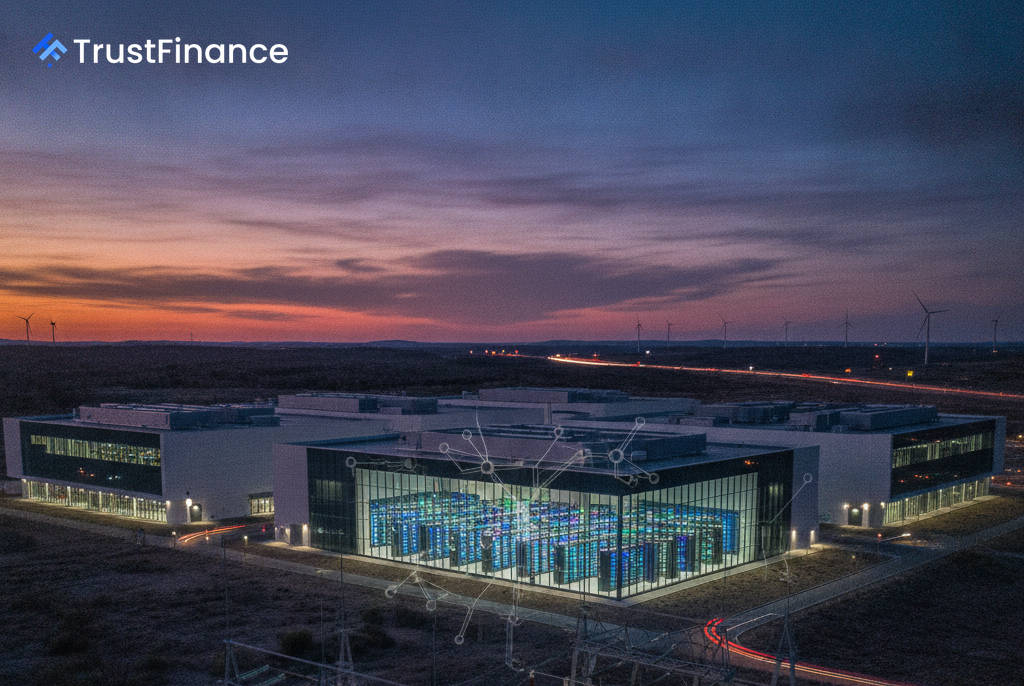
- A $9.8 billion, 15-year lease for 352 MW at its Beacon Point campus in Texas with an investment-grade tenant.
- $3.25 billion in investment-grade bonds, backed by Google, to fund a data center where Alphabet Inc. will be the anchor tenant.
According to the source material, these contracts underscore Hut 8's control over scarce, pre-permitted power infrastructure, a highly valued commodity for hyperscale cloud providers.
Financials: Growth vs. Profitability
 Ad
Hut 8's revenue growth has been substantial, reportedly climbing from $7.32 million in fiscal 2021 to a projected $235.12 million in fiscal 2025. However, this rapid expansion has yet to translate into consistent profitability. The company reported a net loss of -$226.15 million in fiscal 2025, and forward earnings per share (EPS) estimates are projected to remain negative through at least mid-2027.
The company's balance sheet presents a mixed picture. While a debt-to-equity ratio of 531.6% signals high leverage, a current ratio of 19.3x indicates exceptional near-term liquidity, suggesting it can easily cover its short-term obligations.
Wall Street's Bullish Thesis
Despite the lack of current profits, investment banks are overwhelmingly positive. Morgan Stanley initiated coverage with an Overweight rating and a Street-high price target of $263. Other firms, including Benchmark, Needham, and Jefferies, also carry Buy-equivalent ratings.
Analysts are effectively looking past the current income statement and valuing the company based on its long-term, contracted cash flows from its infrastructure assets. The consensus analyst price target implies a +54.6% upside from current levels, as of June 30, 2026. This view contrasts sharply with quantitative fair value models, which, based on current earnings, suggest a significant downside.
The central bet from analysts is that Hut 8 will eventually be re-rated by the market from a volatile crypto miner to a more stable, utility-like infrastructure company. The primary risks to this thesis are execution timelines for its large-scale projects and the challenge of servicing its substantial debt load while it continues to invest in growth.
Read next
More on Stocks
Darden Shares Dip as LongHorn Strength Is Offset by Olive Garden Slowdown
The restaurant operator beat industry benchmarks for same-store sales, driven by exceptional performance at LongHorn Steakhouse, but sluggish growth at its flagship Olive Garden brand and concerns over beef inflation weighed on the stock.
Oracle Declines on Data Center Report; Meta and Eli Lilly Gain in Mixed Trading
Oracle shares fell Thursday following a report of a data center disruption, while Meta Platforms and Eli Lilly posted significant gains. Stitch Fix plunged over 20% after issuing weak forward guidance.

Durable Goods Orders, Consumer Sentiment Data to Guide Markets on Friday
Investors are awaiting key U.S. economic data on Friday, including durable goods orders and the University of Michigan's consumer sentiment survey, for fresh insights into manufacturing health and potential shifts in monetary policy.

US Energy Secretary Explores Voluntary Diesel Export Curbs With Refiners
The U.S. Energy Secretary has contacted major refiners to discuss voluntarily limiting diesel exports as the administration weighs options to combat high fuel prices without imposing a formal ban.