
Story
Adidas Recovery Hinges on Footwear as Growth Stalls, Baird Analysts Say
Summary
Analysts at Baird believe Adidas's multi-year recovery story remains intact but have grown concerned about stalled footwear growth and sustained discounting, which could threaten wholesale momentum.
Adidas AG's (ADSGn) recovery prospects remain credible, but slowing growth in its critical footwear division and persistent market-wide discounting are raising concerns about the pace and profitability of its turnaround, according to an analysis by Baird.
A Mixed Outlook
Baird analysts noted that the German sportswear company's brand positioning remains strategically strong, supporting a multi-year earnings recovery. A key positive sign was a 6% growth in the wholesale channel during Q2 2026, which indicates that retailer demand is currently healthy and provides an important distribution tailwind for the company.
The positive view assumes that this brand strength and product momentum will eventually translate into improved revenue growth and operating leverage. However, analysts flagged several points of concern that temper this outlook.
Footwear and Margin Pressures
The central issue is the performance of the footwear category, which is fundamental to the brand's economics. Baird highlighted several risks to the recovery thesis:
 Ad
- Stalled Footwear Growth: The segment grew by only 1% in Q2 2026, a significant slowdown for a category that typically holds the strongest recovery potential.
- Widespread Discounting: Heavy promotional activity across the U.S. and European markets is pressuring full-price sales and gross margins.
- Wholesale Risk: Sustained discounting from competitors could make retail partners more cautious about placing future orders, potentially making the recent 6% wholesale growth difficult to sustain.
- Macroeconomic Headwinds: Softer consumer conditions, particularly in Europe, could further dampen retailers' willingness to commit to new inventory.
The Path Forward
According to Baird, the investment debate is shifting from whether the brand can recover to whether that recovery can broaden beyond apparel and into the crucial lifestyle footwear segment. Adidas management has reportedly acknowledged continued pressure in lifestyle footwear, even as performance categories show strength.
Management has indicated that wholesale footwear could see improvement in Q4 2026 or early 2027 as retailer inventories normalize. Baird's analysts concluded that while they remain positive on the brand's health, their investment thesis has become more dependent on a successful "footwear repair."
Read next
More on Stocks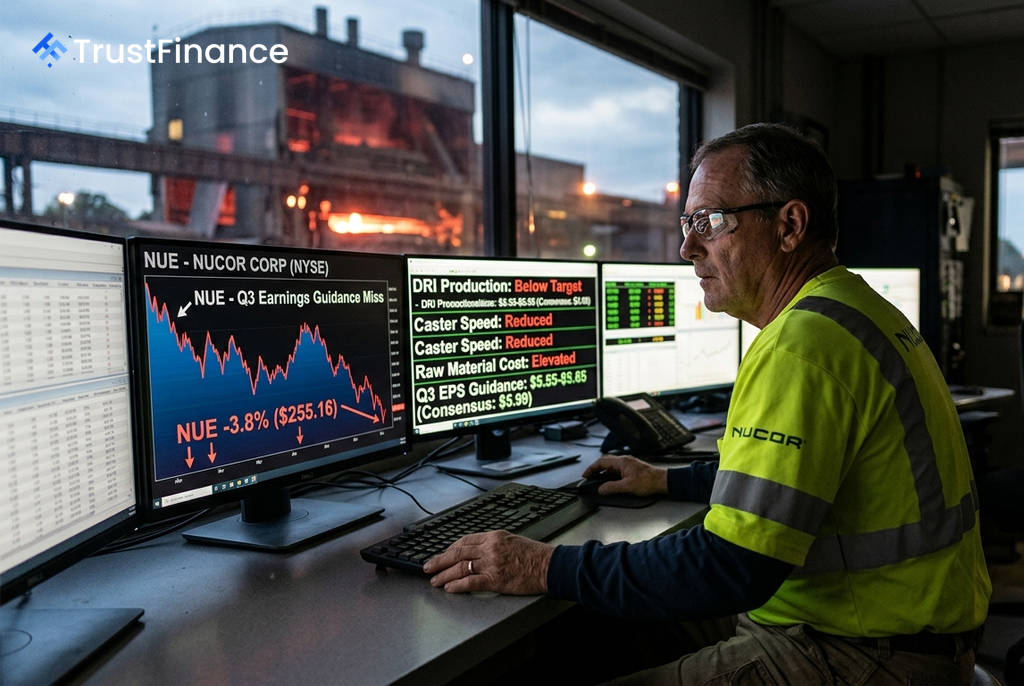
Nucor Stock Slides After Q3 Earnings Guidance Misses Analyst Forecasts
Nucor Corporation (NUE) shares fell after the company projected third-quarter earnings of $5.55 to $5.65 per share, below the Wall Street consensus of $5.99, citing the absence of significant one-time gains from the prior quarter.
Disney Asks Court to Halt FCC License Review, Alleges Political Pressure From Trump
The Walt Disney Company has filed a legal challenge to stop the Federal Communications Commission from conducting an early review of its ABC station licenses, claiming the regulator is acting on President Trump's directives.
Starbucks Settles Florida Lawsuit Over Diversity Policies for $1 Million
The coffee giant has agreed to settle a lawsuit with Florida's attorney general, pledging to avoid race- or sex-based quotas in its employment practices and pay $1 million to cover the state's litigation costs.
Latin American Stocks Rally as Dollar Slides After Fed Rate Hike
Equities and currencies across Latin America gained as a pullback in the U.S. dollar following the Federal Reserve's latest interest rate increase boosted commodity-linked assets and improved investor sentiment toward emerging markets.