
Story
TWFG's High-Growth Outlook Tempered by Steep Valuation Risks
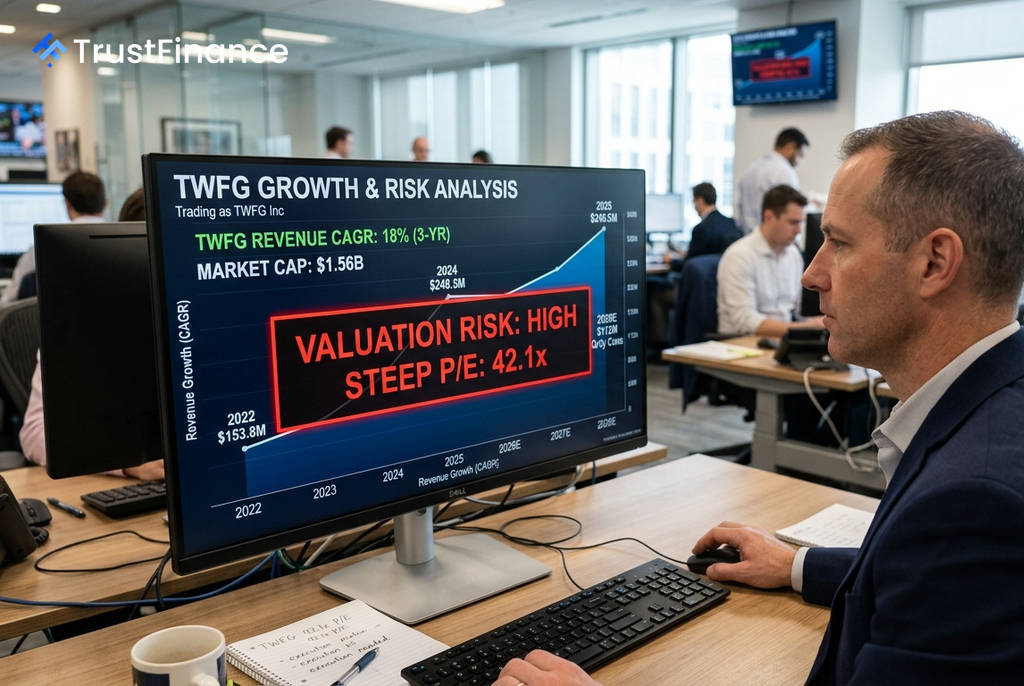
TWFG Inc., an independent insurance distribution platform, presents a compelling growth story for investors, backed by strong revenue forecasts and a solid balance sheet. However, the stock's high valuation creates a significant hurdle, demanding near-perfect execution to justify its current premium, according to an analysis by Investing.com.
Growth Trajectory and Financial Health
The company's business model, which focuses on distributing rather than underwriting insurance products, has fueled substantial expansion. Based on fiscal-year data, TWFG's revenue grew from $153.88 million in 2022 to $248.51 million in 2025, representing an annualized growth rate of approximately 17.4%. The source material noted a projected three-year revenue CAGR of 18%.
TWFG's financial position appears robust, providing flexibility to fund future growth. Key metrics reported as of late 2025 and mid-2026 include:
- Total Debt: $15.49 million (as of Dec 31, 2025)
- Levered Free Cash Flow: $53.14 million (as of Dec 31, 2025)
- Debt-to-Capital Ratio: 0.5%
- Current Ratio: 2.6x (as of Jun 30, 2026)
Valuation Presents a High Hurdle
 Ad
Despite the positive growth outlook, the primary risk for investors lies in the company's demanding valuation. The stock trades at a trailing price-to-earnings (P/E) ratio of 42.1x as of June 30, 2026, a multiple that already prices in continued strong performance.
A significant gap exists between valuation models and analyst consensus. While one fair-value model cited by Investing.com suggested a 55.1% potential upside, the average upside based on analyst targets was only 7.5% as of the same date. This discrepancy highlights differing views on the company's future prospects.
Context and Outlook
Compounding the valuation risk is the company's thin net margin, which was 3.2% in 2025. Such a narrow margin makes the stock vulnerable to a sharp price correction if revenue growth slows and fails to meet the market's high expectations.
Ultimately, TWFG is positioned as a high-growth candidate with a scalable, low-leverage business model. The investment thesis hinges on its ability to continue its rapid expansion. However, the premium valuation suggests that much of this optimism is already reflected in the stock price, placing a heavy burden on the company to consistently deliver strong results.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.