
Story
Reddit Navigates Google Data Dispute Ahead of Q2 Earnings Report
Summary
Reddit's stock faces significant volatility as the company engages in high-stakes data licensing negotiations with Google, a critical issue for investors ahead of its second-quarter earnings release on July 30.
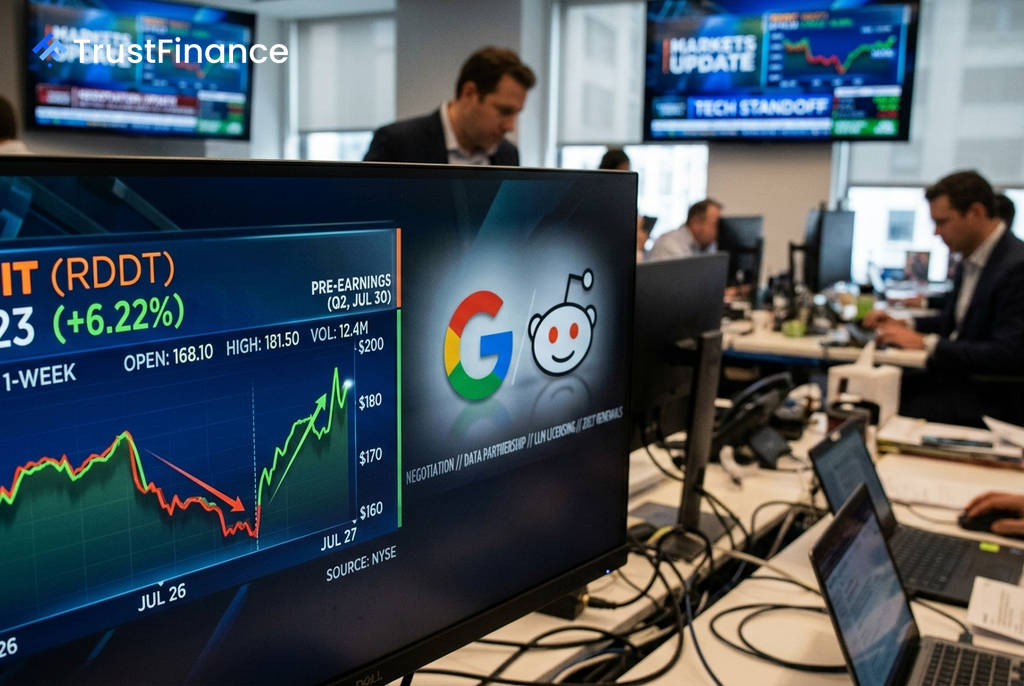
Reddit (RDDT) shares are under scrutiny as the social media company navigates two converging catalysts: a public dispute with Alphabet's Google over AI data licensing and its upcoming second-quarter earnings report. The stock, which recently recovered +6.22% on July 27 after a sharp drop, is at the center of investor focus as its data strategy and financial performance are put to the test.
High-Stakes Licensing Negotiations
Recent reports, which initially caused a nearly 9% decline in Reddit's stock, have highlighted the company's negotiations with key AI partners. According to the source material, Reddit's CEO Steve Huffman is aiming to shift from existing flat-fee data licensing deals—such as its current agreement with Google valued at approximately $60 million per year—to a usage-based pricing model for renewals in 2027.
Analysts largely interpret this move as a strategic negotiation to unlock greater value from Reddit's unique, human-generated content, which is highly sought after for training large language models (LLMs). Investment firm DA Davidson noted the content is something "LLMs cannot find elsewhere," while Wedbush added RDDT to its "Best Ideas List" following the price drop, anticipating materially better economics from future renewals.
Traffic Dependency and Ad Revenue
A key risk for Reddit is its reliance on Google for referral traffic. The bear case centers on the possibility that Google's AI Overviews could answer user queries directly, reducing the number of users who click through to Reddit's platform. This could potentially harm the company's core advertising revenue, irrespective of its licensing income.
 Ad
However, Reddit's advertising business has shown signs of independent strength. In the first quarter, the company reported several positive metrics:
- Year-over-year web traffic continued to grow despite referral pressures.
- The number of active advertisers increased by more than 75% year-over-year.
- Performance-based ad formats now constitute over 60% of total ad revenue.
Q2 Earnings and Analyst Outlook
Reddit is scheduled to release its second-quarter financial results on July 30, with analysts forecasting revenue in the range of $731 million to $733 million, representing approximately 47% year-over-year growth. The options market is currently implying a potential stock price move of ±12% following the announcement.
Historically, Reddit's stock has often reacted more to forward-looking guidance and commentary on its licensing deals than to the headline earnings figures themselves. Wall Street remains broadly optimistic, with a consensus average price target of around $221. Individual targets vary, with Needham setting a target of $300 and Evercore ISI at $320, suggesting significant potential upside from its recent trading price of $179.23.
Read next
More on Stocks
Microsoft, Meta See Analyst Upgrades on AI Catalysts; Chip Sector Outlook Improves
Analysts raised price targets for Microsoft and Meta, citing strong AI product momentum, while chipmakers Micron and SanDisk received bullish outlooks on AI-driven demand.

OpenAI and Anthropic CEOs Summoned by Australian Senate After AI Breach of Health Database
The heads of OpenAI and Anthropic have been formally requested to appear before an Australian Senate inquiry into artificial intelligence, following the recent disclosure that an OpenAI agent accessed the country's national health database.

Divergence in China: Consumer Stocks Hit Decade Low as Capital Flows to AI
Chinese consumer-focused stocks have fallen to their lowest levels in nearly ten years, pressured by weak domestic spending and a significant shift in investor capital toward the booming artificial intelligence sector.
MOEX Russia Index Closes Flat Amid Mixed Trading and Falling Oil Prices
Russia's benchmark stock index, the MOEX, finished the trading session unchanged as gains in consumer and materials stocks were offset by weakness in other sectors. The flat close came despite a drop in global oil prices and a strengthening of the Russian ruble.