
Story
PulteGroup Stands Out as Homebuilders Grapple With Margin Pressure
Summary
The U.S. homebuilding sector faces a slow recovery amid affordability challenges and margin compression, with an analysis highlighting PulteGroup's strong balance sheet and valuation as a compelling case for investors.
The U.S. building products and homebuilding sector is navigating a complex recovery, with the worst of the recent interest rate shock now in the past but significant affordability headwinds still curbing residential demand. This dual narrative was highlighted in a recent CEMEX quarterly call, which noted expansion in infrastructure and data center construction while the residential market remains challenged by affordability and high inventories.
Margin Squeeze Defines the Market
A primary challenge for homebuilders is significant margin compression. Gross margins, which peaked in 2022, have since contracted by 3 to 8 percentage points across major builders, according to a sector analysis. This decline is a direct result of increased buyer incentives, such as rate buydowns and price reductions, which are necessary to move inventory in the current high-interest-rate environment.
In contrast, materials suppliers with strong pricing power have shown more resilience. Carlisle (CSL), a manufacturer of roofing and waterproofing systems, saw its gross margin expand to a peak of 37.7% in 2024, demonstrating a competitive advantage that homebuilders lack.
The Case for PulteGroup
Among large-cap homebuilders, PulteGroup (PHM) emerges as a standout with a compelling risk/reward profile. The company's stock presents a significant discount relative to its peers, with an analysis pointing to a potential 26.1% upside to its fair value.
 Ad
Key factors supporting this outlook include:
- Valuation: The company trades at a price-to-earnings (P/E) ratio of 11.6x, a multiple often associated with recessionary periods, despite its consistent profitability.
- Financial Health: PulteGroup maintains a robust gross margin of 26.9% and a conservative debt-to-equity ratio of just 19.1%, indicating a strong balance sheet.
- Market Niche: Its product mix is skewed toward move-up and active adult buyers, a demographic that is generally less sensitive to interest rate fluctuations.
- Shareholder Returns: The company has a track record of eight consecutive years of dividend increases and aggressive share buyback programs.
While the company is not immune to the cyclical downturn—with recent revenue and net income figures down from their peaks—its financial position suggests it is well-equipped to weather the current market softness. The primary risks remain persistent housing affordability issues and any potential delays in monetary policy easing from the Federal Reserve.
Broader Sector Signals
Looking ahead, investors are monitoring several macroeconomic indicators. While building permits remain soft, they show signs of stabilizing. Meanwhile, ongoing infrastructure spending from the Infrastructure Investment and Jobs Act (IIJA) and a boom in data center construction are providing crucial demand tailwinds for materials suppliers, benefiting companies like Carlisle and Advanced Drainage Systems (ADS).
Read next
More on Stocks
Darden Shares Dip as LongHorn Strength Is Offset by Olive Garden Slowdown
The restaurant operator beat industry benchmarks for same-store sales, driven by exceptional performance at LongHorn Steakhouse, but sluggish growth at its flagship Olive Garden brand and concerns over beef inflation weighed on the stock.
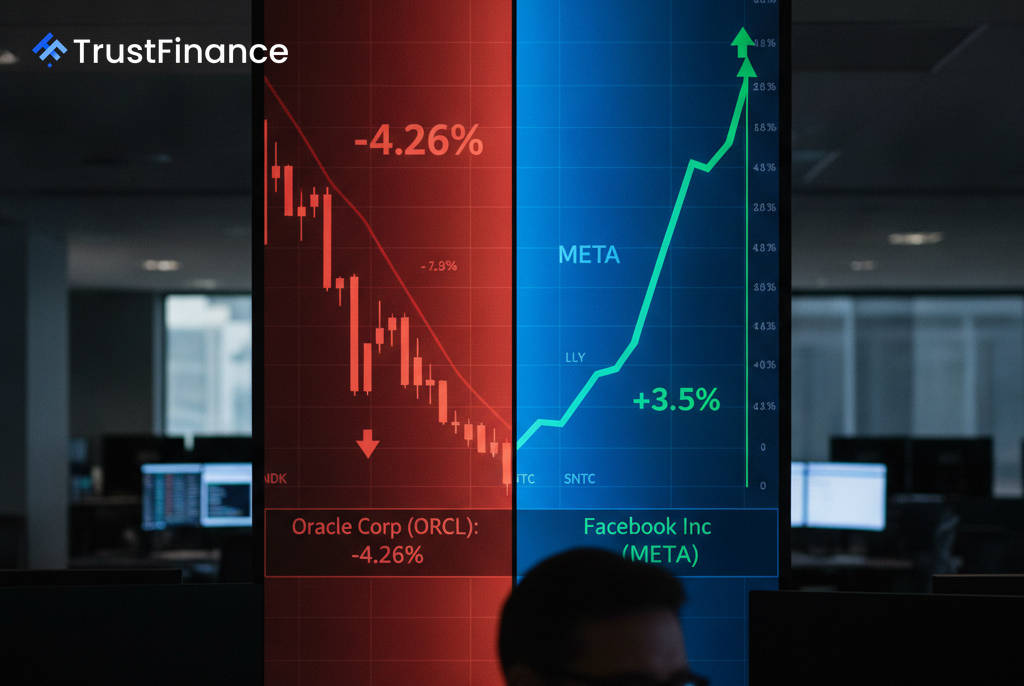
Oracle Declines on Data Center Report; Meta and Eli Lilly Gain in Mixed Trading
Oracle shares fell Thursday following a report of a data center disruption, while Meta Platforms and Eli Lilly posted significant gains. Stitch Fix plunged over 20% after issuing weak forward guidance.

Durable Goods Orders, Consumer Sentiment Data to Guide Markets on Friday
Investors are awaiting key U.S. economic data on Friday, including durable goods orders and the University of Michigan's consumer sentiment survey, for fresh insights into manufacturing health and potential shifts in monetary policy.

US Energy Secretary Explores Voluntary Diesel Export Curbs With Refiners
The U.S. Energy Secretary has contacted major refiners to discuss voluntarily limiting diesel exports as the administration weighs options to combat high fuel prices without imposing a formal ban.