
Story
Nike Stock Plummets as High-Risk China Strategy Divides Investors
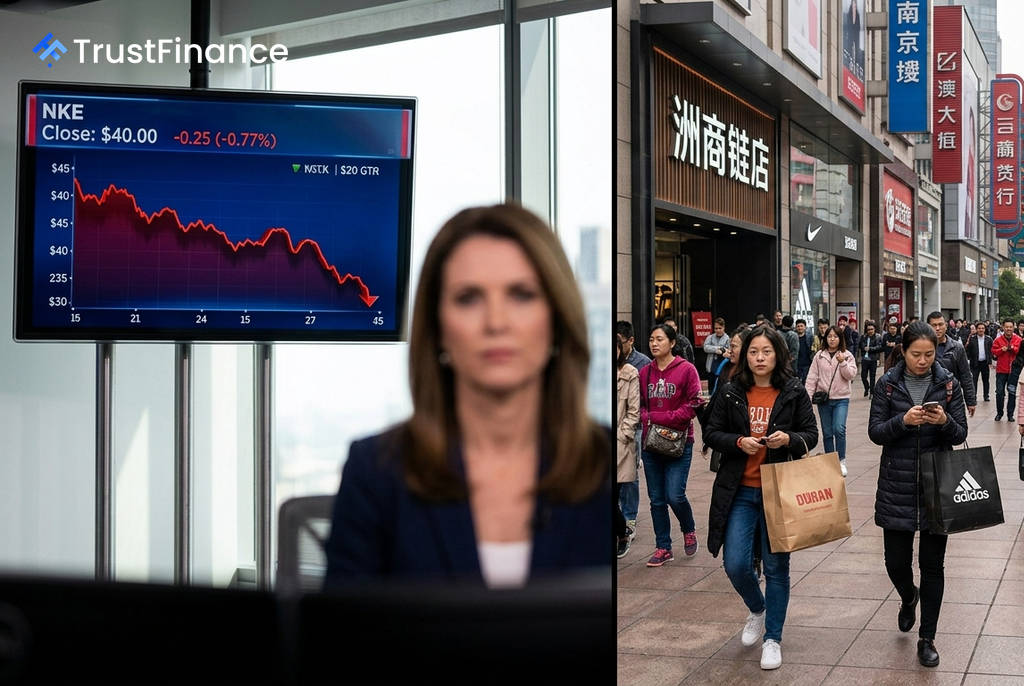
Nike's stock has plummeted nearly 35% year-to-date as the company undertakes a high-risk strategic pivot in China, its third-largest market. The move has created a sharp divide among investors, who are now weighing whether the battered shares represent a deep value opportunity or a potential value trap.
High-Stakes China Overhaul
Nike is in the midst of a significant distribution overhaul in China, a market that generated $5.85 billion in revenue for the company in fiscal year 2026. The strategy involves terminating online distribution agreements with major partners Topsports and Pou Sheng, a change set to take effect on January 1, 2027.
This decision is expected to cut approximately $750 million in annual revenue, or about 9.5% of the company's China sales. The move comes after eight consecutive quarters of declining sales in the region, with Nike aiming to protect its brand's pricing power by sacrificing short-term sales volume. Analysts at Citi have described the strategy as an "extreme move" that carries "considerable execution risk."
Market Reaction and Technical Pressure
The market has reacted harshly to the uncertainty, sending Nike (NKE) shares down 34.84% year-to-date to trade near their 52-week low of $40.00. In stark contrast, rival Adidas (ADDYY) has seen its stock decline by only 7.51% over the same period, with analysts flagging it as a primary beneficiary of Nike's pullback.
 Ad
Adidas reported 17% currency-constant growth in China during the first quarter of 2026. Meanwhile, technical indicators for Nike stock remain deeply negative, with a 'Strong Sell' signal across all timeframes and a weekly Average Directional Index (ADX) of 46.4 confirming a strong, established downtrend.
The Bull vs. Bear Debate
The stock's sharp decline has ignited a debate over its future prospects. Proponents of the bull case point to a potential value opportunity, with the stock trading at less than half its 52-week high. Valuation models and some analysts see significant upside, including:
- An InvestingPro Fair Value estimate of $57.88, suggesting a 34% potential increase.
- A price target of $68 from Bernstein, which maintains an 'Outperform' rating.
However, bears highlight the immediate revenue headwinds from the China strategy and a cautious consensus among analysts, with 25 'Hold' and 2 'Sell' ratings compared to just 12 'Buy' ratings. The market appears to be in a "show me" mode regarding the turnaround plan, with clear results not expected until 2027 at the earliest.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.