
Story
Nike Stock Hits 12-Year Low as Turnaround Seen Unlikely Before 2027
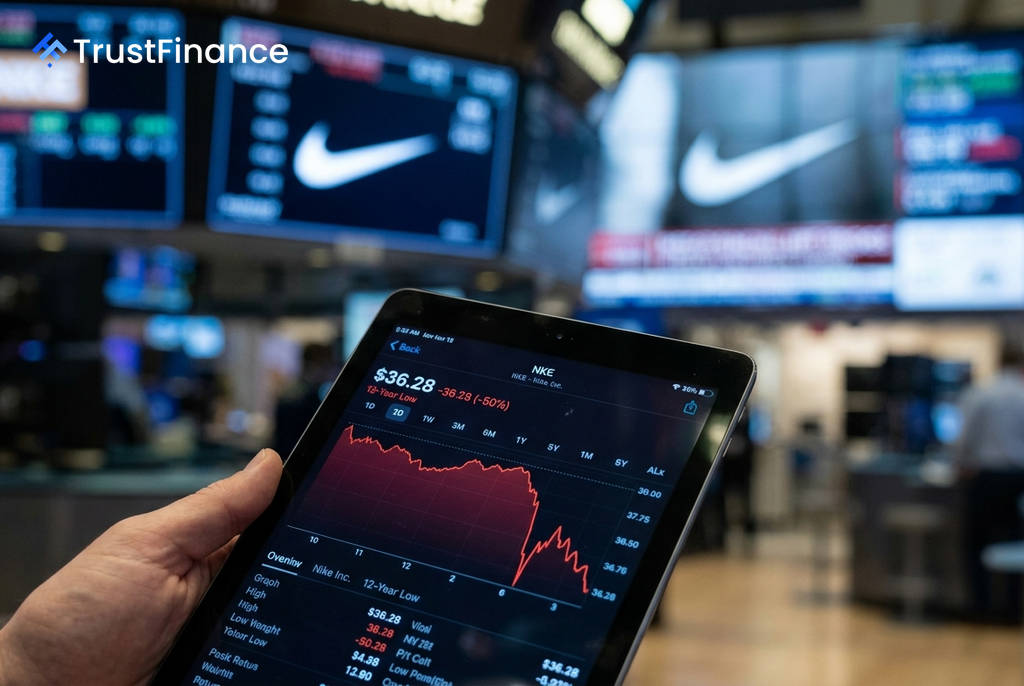
Nike Inc. (NKE) shares are trading at 12-year lows, reflecting deep-seated operational challenges and a financial outlook that suggests a prolonged turnaround. The stock was trading at $36.28 on September 16, approximately 50% below its 52-week high, as investors weigh a series of structural issues facing the iconic brand.
Deep-Rooted Challenges Erode Financials
Data reveals a significant decay in Nike's core financial health between fiscal years 2022 and 2026. The company has seen four years of zero net revenue growth, while its diluted earnings per share (EPS) have collapsed by -44% from $3.75 to $2.10. Over the same period, net income margin was nearly halved from 12.9% to 6.7%.
Analysts attribute this deterioration to several persistent problems:
- Brand Erosion: Nike's popularity in the key back-to-school segment fell from a peak of 92.5% in 2021 to just 45.8% in 2026, according to a Stifel survey.
- Channel Disruption: An aggressive shift to a direct-to-consumer (DTC) model has strained relationships with wholesale partners. While efforts to rebuild these channels are underway, the broader footwear market remains soft and highly promotional.
- Product Pipeline Lag: New lifestyle product innovations are not expected to reach a meaningful scale until the second half of 2027, highlighting long industry lead times.
Technicals Signal Strong Downtrend
 Ad
The one bright spot for the company has been its Running division, which has posted five straight quarters of double-digit growth. However, this segment remains a small fraction of Nike's overall business.
Technical indicators paint a bearish picture, with a "Strong Sell" rating across multiple timeframes. The weekly Average Directional Index (ADX), a measure of trend strength, sits at 62.5, with readings above 60 indicating a deeply entrenched downtrend. While the Relative Strength Index (RSI) has dipped into oversold territory, analysts caution that this does not guarantee a reversal given the strong bearish momentum.
The Long Road to Recovery
Analysts have outlined a multi-year roadmap for a potential recovery, with the company's November 2026 Capital Markets Day serving as the next major catalyst. This event is seen as a critical test for management to present a credible plan to restore earnings growth.
The earliest signs of a fundamental improvement, such as stabilizing margins, are not expected until the first half of 2027. The valuation presents a mixed picture: while the stock's 17.4x trailing P/E and 4.4% dividend yield may appeal to some, its forward P/E expands to 21.1x due to depressed earnings estimates. Persistent weakness in Greater China, intensifying competition, and the recent resignation of its Chief Accounting Officer add to the headwinds.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.