
Story
Morgan Stanley Upgrades DNB, Swedbank on Brighter Nordic Outlook; Danske Remains Top Pick
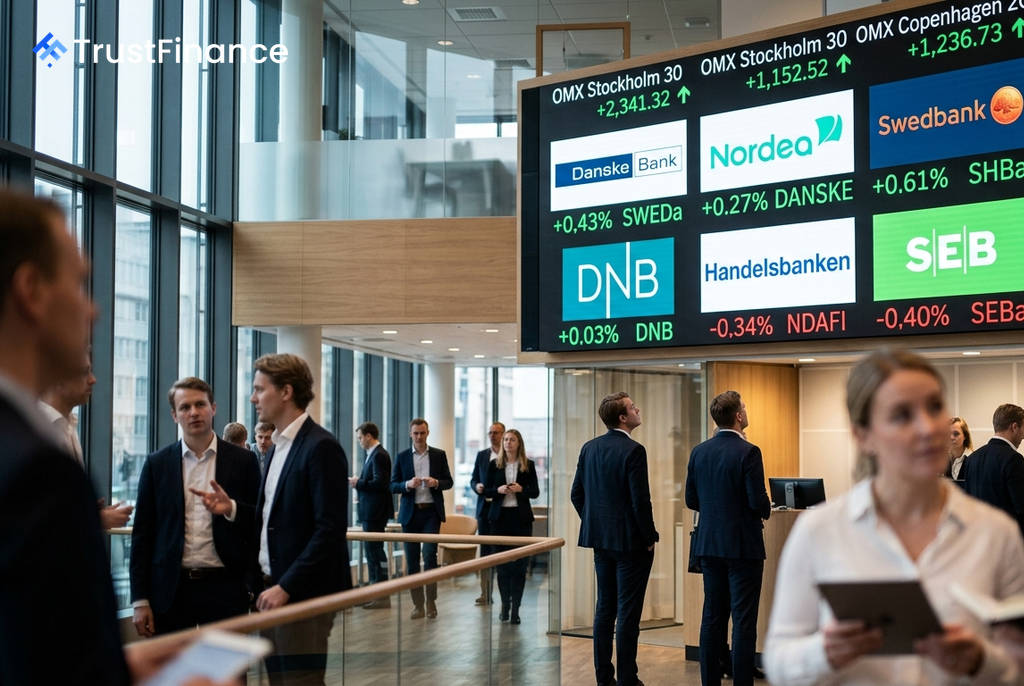
Morgan Stanley has revised its ratings on several major Nordic banks, upgrading DNB and Swedbank while downgrading Nordea, citing a more favorable macroeconomic environment and the prospect of further interest rate hikes. In a research note, the investment bank reaffirmed Danske Bank as its top pick in the sector.
Key Rating Changes
Analysts led by Gulnara Saitkulova outlined a series of adjustments to their ratings across the region. The key moves include:
- Danske Bank (DANSKE): Maintained at Overweight and designated the firm's top pick.
- DNB (DNB): Upgraded to Equal-weight from Underweight.
- Swedbank (SWEDa): Upgraded to Equal-weight from Underweight.
- Nordea (NDAFI): Downgraded to Equal-weight from Overweight.
- Handelsbanken (SHBa): Maintained at Underweight.
- SEB (SEBa): Maintained at Equal-weight.
Macro Tailwinds Support Sector
The more bullish stance is supported by improving macroeconomic conditions, including higher interest rates, stronger volumes, and widening spreads, according to the note. Morgan Stanley highlighted Sweden's real GDP growth, which is forecast at around 2% in 2026-27—approximately double the pace of the euro area—supported by roughly 88 billion Swedish crowns in fiscal stimulus.
 Ad
Furthermore, the analysts noted that Swedish mortgage spreads have recovered to around 150 basis points, returning to 2021 levels. They anticipate an additional 25 basis point rate hike from the European Central Bank, Sweden's Riksbank, and Norway's Norges Bank, viewing it as "a tailwind for this rate-sensitive region."
Bank-Specific Analysis
Morgan Stanley identified Danske Bank as offering "the highest upside," pointing to a potential valuation re-rating after the completion of a three-year probation tied to a money-laundering case. The analysts also cited an attractive total shareholder yield of 9-10% and strong momentum in corporate lending.
The upgrade for Swedbank was attributed to its significant progress in gaining mortgage market share in Sweden, which climbed to 20% in the second quarter of 2026 from just 5% in 2024. DNB's upgrade reflects a valuation that "now looks less demanding" at 11 times estimated 2027 earnings, though intense competition in Norway prevented a move to Overweight.
Conversely, Nordea was downgraded to Equal-weight because the stock is seen as increasingly "catalyst-light," with its current valuation largely reflecting its solid performance. Handelsbanken remains at Underweight, with analysts stating its business model "remains structurally challenged" by international operations that dilute group profitability.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.