
Story
Moody's Downgrades Mondi to Baa2 on Weakened Credit Metrics Amid Market Downturn
Summary
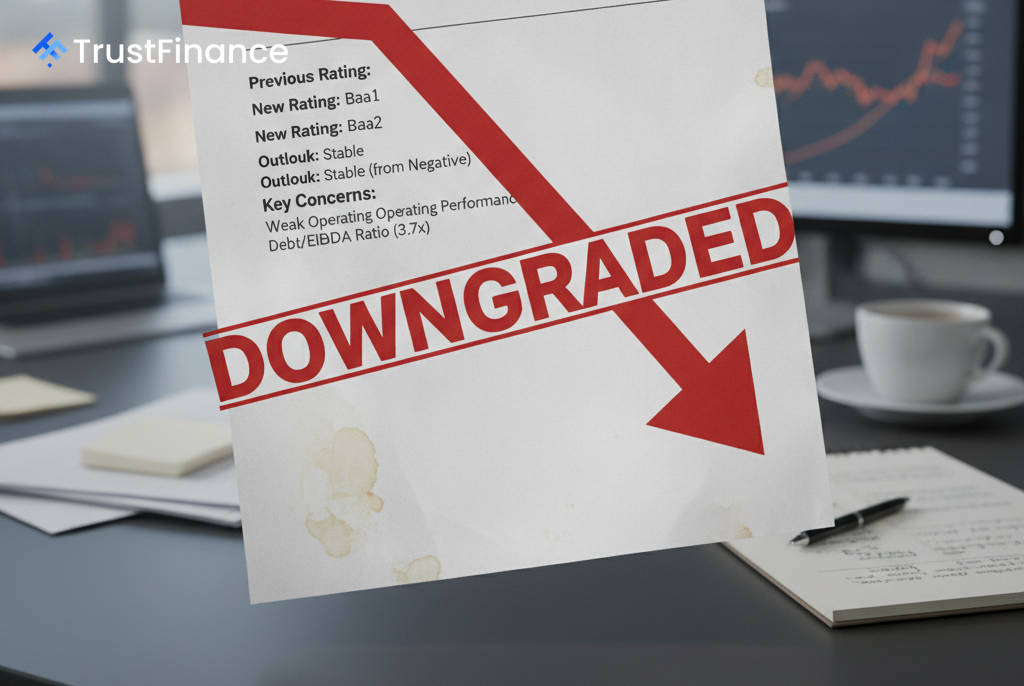
The ratings agency lowered Mondi's rating from Baa1, citing a prolonged downturn in the paper and packaging markets that has weakened the company's earnings, cash flow, and key financial ratios.
Moody's Ratings has downgraded packaging and paper group Mondi Plc to Baa2 from Baa1, attributing the move to sustained weak operating performance and credit metrics that have deteriorated amid a prolonged industry downturn. The ratings agency concurrently shifted Mondi's outlook to stable from negative.
Downgrade Driven by Weakened Metrics
The downgrade reflects weak earnings and cash flow generation over the past two years as Mondi navigated a challenging global paper and packaging market, according to Moody's. The agency noted that the company's key credit ratios for the twelve months ended June 2026 were materially weaker than levels appropriate for its previous rating.
Key metrics highlighted by the ratings agency include:
- Moody’s-adjusted gross debt/EBITDA: Stood at approximately 3.7x, significantly higher than the previous rating guidance of around 2.0x.
- Retained cash flow to net debt: Fell to approximately 19.9%, below the 30% threshold embedded in the prior guidance.
- EBITDA margin: Declined to approximately 10.1%, a material drop from historical levels and expectations for a Baa1 rating.
 Ad
Mondi experienced negative free cash flow in both 2024 and 2025, though it turned positive in the twelve months to June 2026, supported by working capital inflows and lower capital spending.
Supporting Factors and Stable Outlook
Despite the downgrade, Moody's stated that the new rating continues to be supported by Mondi's strong market positions in corrugated and flexible packaging, its broad geographic diversification, and its well-invested asset base. The company's vertical integration, which includes significant pulp production and forestry management, was also cited as a strength.
From a liquidity perspective, Mondi maintained a solid position as of June 30, 2026, with approximately €154 million in cash and access to a fully undrawn €1.0 billion committed revolving credit facility. The company also has no material debt maturities until 2028 and its debt structure does not contain financial maintenance covenants. The stable outlook indicates that Moody's expects Mondi's credit profile to remain consistent with the Baa2 rating in the near term.
Read next
More on Stocks
Pirelli Board Approves €1 Billion Expansion of Georgia Tire Plant
Pirelli will invest €1 billion to expand its Rome, Georgia, manufacturing facility, aiming to boost production of high-value tires and create approximately 1,000 new jobs.
Treasury Yields Rise as Traders Increase Bets on Another Fed Rate Hike
U.S. Treasury yields climbed on Tuesday, with the policy-sensitive 2-year note hitting a fresh two-year high, as markets priced in a greater than 50% chance of another Federal Reserve interest rate increase in October.

Amgen, Vicor Surge While Financials and Fitness Stocks Lag in Divergent Market Session
Amgen and Vicor Corp. were among Tuesday's top gainers, leading a day of mixed performance where significant rallies in some stocks contrasted with sharp declines in others, including LPL Financial and Planet Fitness.

Goldman Sachs Taps Microsoft as Top AI Pick on Enterprise Strength
Goldman Sachs has designated Microsoft as its leading investment choice in the artificial intelligence sector, highlighting the tech giant's strategic capital expenditures and strong enterprise adoption following recent meetings with company leadership.