
Story
Meta's Valuation Hinges on Proving AI Investments Can Drive Profit
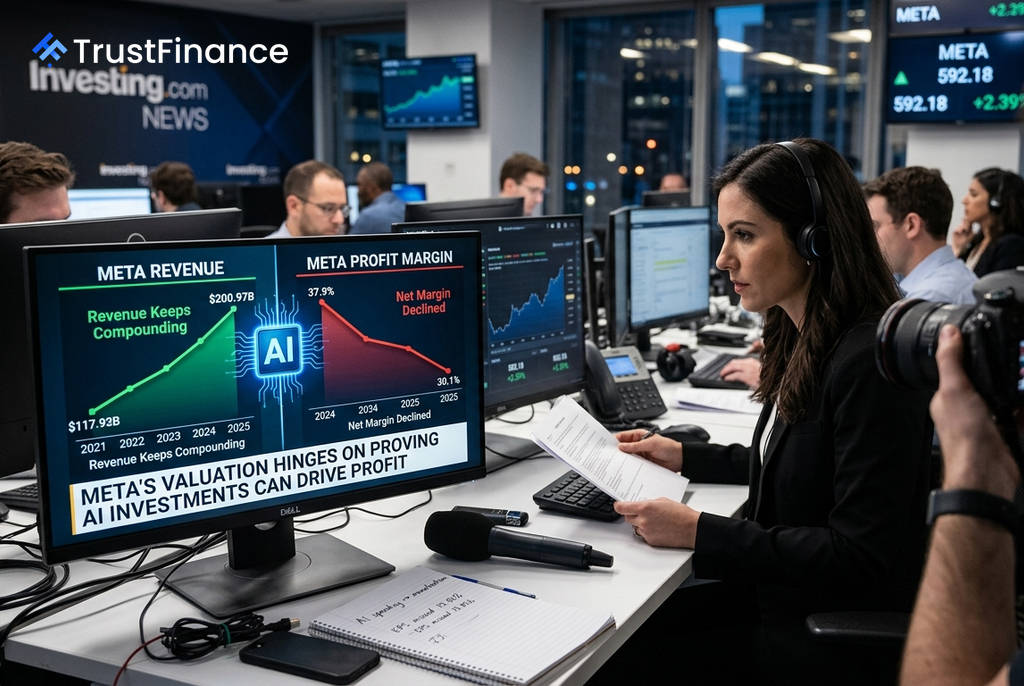
Meta Platforms (META) presents a complex picture for investors, with a valuation that appears compelling on the surface but is clouded by underlying profitability concerns. While the company's stock trades at a 18.3x forward earnings multiple, suggesting potential value, the market remains cautious as heavy investments in artificial intelligence have yet to translate into consistent earnings growth, according to an analysis by Investing.com.
Revenue Growth vs. Profit Squeeze
Meta has demonstrated robust top-line expansion, with annual revenue growing from $117.93 billion in 2021 to a projected $200.97 billion in 2025. Consensus estimates cited by Investing.com point to continued growth, forecasting $254.06 billion in revenue for fiscal year 2026 and $305.23 billion for 2027.
However, this growth has come at a cost to profitability. The company's most recent quarterly earnings per share (EPS) of $6.18 missed the expected $7.17, triggering a 9.16% negative price reaction. This reflects a broader trend of margin pressure, as net margin declined from 37.9% to 30.1% between 2024 and 2025, and free cash flow fell from $54.07 billion to $46.11 billion amid a heavy AI investment cycle.
Conflicting Market Signals
The divergence between revenue strength and earnings weakness has created a split in market sentiment and valuation models. While revenue estimates have risen, EPS estimates have declined by 5.59% over the last 90 days, as per the report. This indicates that while demand for Meta's services remains strong, the cost of delivering them is rising.
 Ad
This division is also visible in valuation perspectives:
- Analyst Targets: Street analysts see significant potential, with an average target price implying 29.6% upside as of June 30, 2026.
- Quantitative Models: In contrast, InvestingPro's fair value model suggests a much more modest 5.1% upside from the price of $592.18 on September 2, 2026.
Outlook: Awaiting Proof of Monetization
Recent developments, including new AI product launches and the dismissal of an antitrust lawsuit, have provided some positive momentum. Bernstein recently reiterated an Outperform rating with an $800 price target, citing Meta's advertising trajectory. However, the stock remains 10.64% lower year-to-date and is testing technical resistance levels.
Ultimately, the potential for Meta's stock to be re-rated higher by the market depends on its ability to prove that its substantial AI capital expenditures can generate a return and lead to improved margins. Investors are shifting their focus from the narrative of AI spending to the tangible results of AI monetization.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.