
Story
Humana Garners Five Wall Street Upgrades on 2028 Margin Recovery Outlook
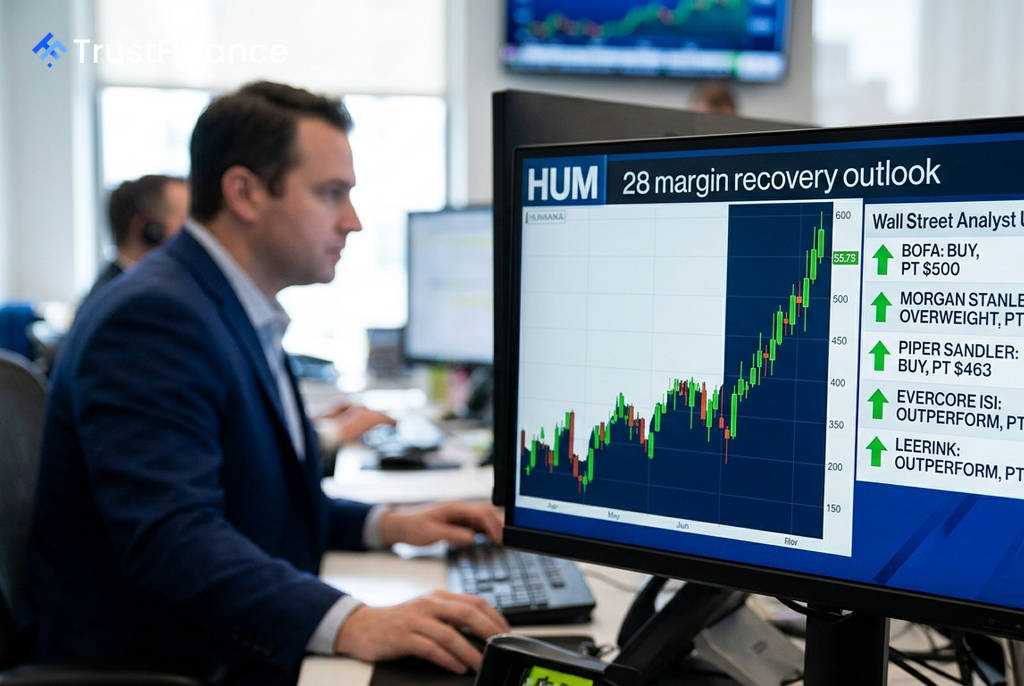
Humana Inc. (HUM) has received at least five analyst upgrades over the past week, as Wall Street shifts its focus from near-term pressures to a long-term margin recovery story projected to materialize by 2028. The upgrades, which include price targets ranging from $370 to $513, came despite a stock drop following the company's second-quarter earnings, signaling growing investor confidence in the insurer's multi-year strategic plan.
The 2028 Recovery Blueprint
Analysts are largely looking past the company's current performance and are instead valuing the stock on its potential future earnings power. The bull case centers on a specific three-year roadmap to restore profitability in its core Medicare Advantage (MA) business.
According to analyst reports, Humana's strategy involves:
- 2026: Navigating a year where individual MA margins are below breakeven, pressured by a significant headwind from lower "Stars" quality ratings on its Medical Loss Ratio.
- 2027: Aims to recover over 100 basis points of MA margin while pruning its membership base, with planned exits affecting approximately 600,000 members to improve the quality of its book of business.
- 2028: The target is to achieve a sustainable pre-tax MA margin of 3% or greater. Piper Sandler, one of the upgrading firms, projects this could translate to earnings per share of $25.72.
Q2 Results Provide Key Catalyst
 Ad
The trigger for this forward-looking sentiment was a key data point in Humana's Q2 results: stable medical costs. The company reported a medical cost ratio of 91.2%, which held steady despite a 25% year-over-year growth in MA membership. This allayed investor fears of a surge in healthcare utilization and provided a crucial proof point that management's cost controls are taking hold.
Central to the recovery thesis is the company's ability to improve its Medicare Advantage Star ratings. Higher ratings unlock significant federal bonus payments that directly boost margins. Management noted that a key plan, which covers a third of its MA members, is on a credible path to regain a 4-Star rating in 2027, reporting that it is tracking ahead of internal benchmarks on key quality measures.
A Cautious Counterpoint
Not all analysts share this optimistic long-term view. On the same day as several upgrades, Raymond James downgraded the stock to Market Perform, citing the Stars rating decision as a "large binary event" with too much uncertainty. The firm argued that at approximately 13.5 times its 2028 earnings estimate, the stock already reflects a significant amount of positive news.
Bears also point to execution risks, noting that the company's ambitious margin goals must be met flawlessly. Other potential headwinds include the risk that rapid membership growth could attract higher-cost patients and the ever-present uncertainty of changes to healthcare policy and risk-adjustment models.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.