
Story
German Short-Term Yields Hit Over Two-Year High as Oil Surge Stokes ECB Rate Hike Fears
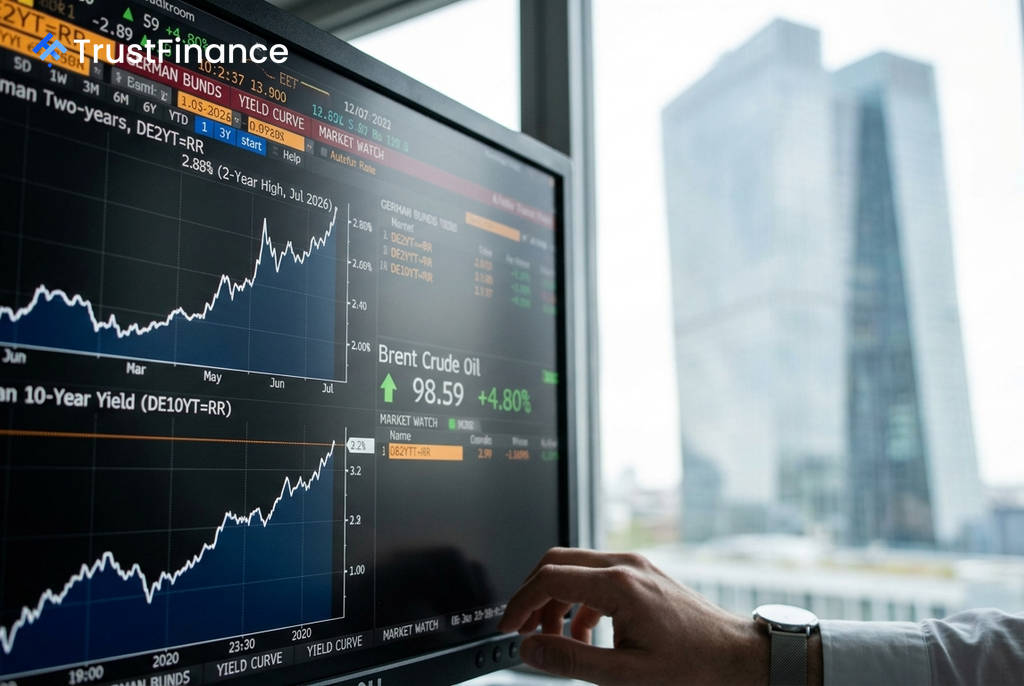
Short-dated German government bond yields climbed to their highest level in over two years on Thursday as a surge in crude oil prices fueled concerns about persistent inflation, prompting investors to reassess the European Central Bank's policy path.
Yields Surge on Inflation Fears
The rate-sensitive German two-year yield, a key barometer for near-term monetary policy expectations, reached an intraday high of 2.88%, a level not seen since mid-2024, according to Investing.com data. The sell-off in fixed-income also pushed the benchmark German 10-year Bund yield near 3.2%, approaching multi-month peaks.
This repricing in European sovereign debt is being driven by a sharp increase in global oil prices, which have risen amid fresh Middle East supply disruptions. The persistent energy rally has reignited market anxieties over imported inflation, threatening to complicate the Eurozone's recent progress on disinflation.
ECB Policy in Focus
The bond market turmoil comes just hours before the ECB's scheduled monetary policy announcement. While policymakers in Frankfurt are widely anticipated to hold the benchmark deposit facility rate steady at 2.25%, the inflationary pressure from energy costs has altered market forecasts for the central bank's future actions.
 Ad
Money markets have rapidly priced out expectations for near-term monetary easing. Swaps pricing now indicates an increasing probability of a rate hike by September as traders bet that higher energy costs will force the ECB to adopt a more hawkish stance.
Broader Market Impact
The move higher in German yields reverberated across the broader Eurozone government bond market. Italian 10-year sovereign bond yields held near the 4.00% mark, reflecting a wider risk-off sentiment in regional debt.
Consequently, the closely watched spread between Italian and German 10-year borrowing costs widened to approximately 82 basis points. This widening gap signals that investors are demanding a higher risk premium for holding debt from peripheral Eurozone economies amid the renewed uncertainty.
Read next
More on Forex
Polish Zloty Hits 11-Month Low Against Euro on Energy Price Pressure
The Polish zloty weakened to 4.410 against the euro, its lowest point since November 2023, as rising energy prices and caution ahead of a U.S. Federal Reserve decision weighed on the currency.

Sterling Slips as Dollar Strengthens Ahead of Fed Decision and UK Budget
The British pound lost ground against a resurgent U.S. dollar on Wednesday as market attention shifted from tech sector volatility to upcoming central bank decisions and the UK budget announcement.
Eurozone Bond Yields Climb as French Fiscal Concerns Return Ahead of Fed, ECB Decisions
Yields on French and German government bonds rose as relief from a ratings affirmation for France proved temporary, with investors refocusing on fiscal challenges and awaiting key policy verdicts from the U.S. Federal Reserve and the European Central Bank.

Canadian Dollar Slips as Markets Await Bank of Canada, Fed Decisions
The Canadian dollar edged lower against its U.S. counterpart, snapping a seven-day winning streak as investors adopted a cautious stance ahead of Wednesday's key interest rate announcements from both the Bank of Canada and the U.S. Federal Reserve.