
Story
Credo Technology Stock Plunges Despite Earnings Beat as Margin Concerns Dominate
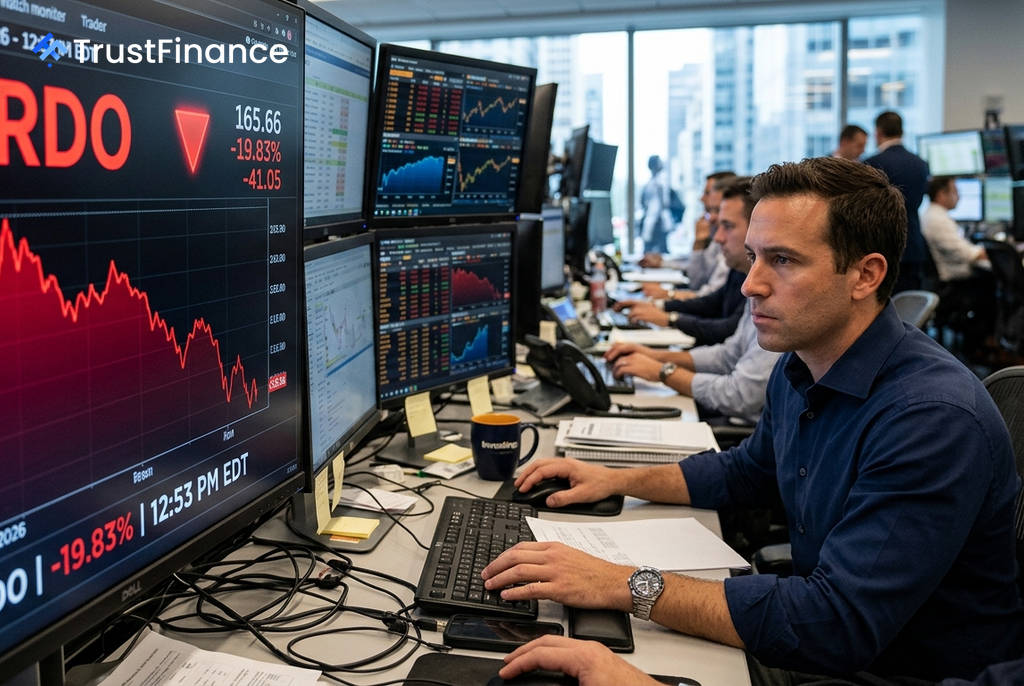
Credo Technology Group Holding Ltd. (NASDAQ: CRDO) shares fell nearly 20% in trading on Wednesday despite the company reporting first-quarter revenue and earnings that exceeded analyst estimates. Investor focus shifted from the strong top-line growth to contracting profitability, as pressure on gross margins overshadowed the otherwise positive results.
Revenue Beat Obscured by Margin Contraction
For its first fiscal quarter of 2027, Credo reported revenue of $479 million, an increase of 115% year-over-year and ahead of the consensus estimate of approximately $470 million. The company also posted earnings per share of $1.20, which beat expectations.
However, the market reacted negatively to the company's profitability metrics. According to the report, Credo's GAAP gross margin fell to 64.5% from 68.2% in the prior period. Guidance for the second quarter suggested this pressure would continue, prompting a sell-off as investors weighed the cost of the company's rapid growth in its optical products business.
Strong Growth Outlook Tempered by Profitability Questions
Credo's management provided a robust growth forecast, which did little to assuage near-term margin concerns. The company projects second-quarter revenue to be between $525 million and $535 million, implying sequential growth of roughly 10%. For the full fiscal year 2027, management expects revenue growth to exceed 85%.
This outlook highlights the central debate for investors. The bull case points to significant operating leverage, with operating expenses guided to rise about 55%—well below the anticipated revenue growth. The bear case, which dominated Wednesday's trading, is that the ramp-up of new, lower-margin optical products is structurally diluting the company's overall profitability.
 Ad
Key Catalysts and Customer Metrics
Investors are closely monitoring several key areas as the company scales its operations. While Credo's optical business is expanding, with management expecting over $600 million in optical revenue in fiscal 2027, this growth is the source of the current margin pressure.
Other key points from the earnings report include:
- Customer Concentration: The company's largest customer accounted for 33% of Q1 revenue. Management noted it expects broader adoption from hyperscale and cloud customers to improve this concentration over time.
- Next-Generation Products: Initial revenue from Credo's 1.6T digital signal processors (DSPs) is expected late in fiscal 2027, but a more significant contribution is not anticipated until fiscal 2028, making it a medium-term catalyst.
- Inventory: Inventory rose to $313.1 million as the company prepares for future demand, which supports the growth narrative but also increases execution risk if product ramps are delayed.
Ultimately, the market is looking for evidence that the current margin compression is temporary. The company's next earnings report will be critical in demonstrating whether it can scale its new products without permanently sacrificing profitability.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.