
Story
B. Riley Designates Ichor Holdings as Top Tech Pick on Semiconductor Outlook
Summary
B. Riley Securities has named semiconductor equipment supplier Ichor Holdings its top technology stock, setting a $105 price target based on accelerating industry demand and margin growth opportunities.
B. Riley Securities has identified Ichor Holdings (ICHR) as its leading stock selection in the technology sector, maintaining a Buy rating and issuing a $105 price target. The firm's analysis, released ahead of the SEMICON West conference, suggests the valuation represents approximately 83% upside potential from current levels.
Analyst's Thesis
B. Riley's positive outlook is anchored in the expectation of accelerating demand for semiconductor equipment, positioning Ichor as a key beneficiary. The company supplies critical components to major equipment manufacturers, including Applied Materials and Lam Research, which are projected to see system growth of over 35% and 15%, respectively, in calendar years 2027 and 2028.
The firm believes Ichor is a leveraged play on these industry bellwethers as they expand capacity across foundry, DRAM, and NAND segments. B. Riley noted Ichor is executing well on a plan to expand its gross margins into the mid-teens to 20% range and projects the company's annualized revenue capacity could grow from $2.0 billion in the near term toward $3.0 billion over the long term.
Financial Outlook and Valuation
B. Riley provided specific multi-year financial estimates for Ichor, which it believes are not fully reflected in the market's current valuation.
 Ad
- Revenue Estimates: $1.25 billion (2026), $1.67 billion (2027), and $1.91 billion (2028)
- Earnings Per Share (EPS) Estimates: $1.57 (2026), $3.44 (2027), and $4.68 (2028)
The analyst noted that consensus revenue growth estimates of 29% for 2027 and 10% for 2028 appear conservative. The firm's $105 price target is based on a 22x price-to-earnings (P/E) multiple applied to its calendar year 2028 EPS projection, a multiple that falls in the lower half of the stock's ten-year historical range.
Market Context
The endorsement comes after Ichor's shares have declined approximately 52% in the third quarter of 2026 to date, bringing its forward two-year P/E ratio to 17x, a one-year low. In its most recent report, Ichor announced second-quarter revenue of $294.8 million and a non-GAAP gross margin of 14.1%, which exceeded its guidance and prompted price target increases from other firms, including DA Davidson and Needham.
Read next
More on Stocks
Citi Lowers Burberry Price Target on Softer Luxury Demand
Citi analysts reduced their price target for Burberry to £14.6, citing a challenging macroeconomic environment and slowing growth in the luxury sector, though they maintained a "Buy" rating on the stock.
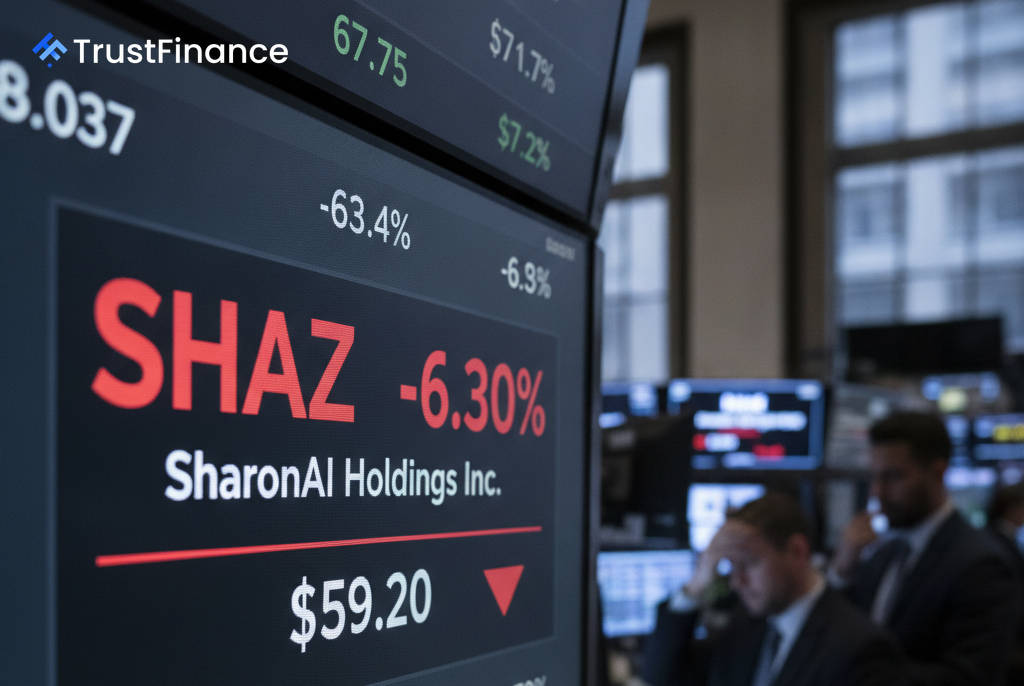
SharonAI Stock Falls Over 6% in 'Sell the News' Reaction to Partnership
Shares of SharonAI Holdings are declining sharply, erasing recent gains as investors take profits following a new partnership announcement. The drop comes amid broader market weakness and ongoing concerns about the company's high valuation.

Aehr Test Systems Stock Slides Amid Insider Selling and Analyst Concerns
Shares of Aehr Test Systems are extending recent losses amid a combination of factors, including the lingering impact of an analyst downgrade, recent insider selling, and a weak broader market for technology stocks.
Aurora Innovation Stock Slides Over 8% in 'Sell the News' Reaction to Investor Day
Shares of the autonomous trucking firm are declining despite positive operational updates, as investors take profits amid broader market weakness and concerns over the company's financials.