
Story
Affirm Could Surpass $200 a Share in Bull Case, Mizuho Analyst Says
Summary
A Mizuho analyst argues that Wall Street is significantly underestimating Affirm's long-term earnings potential, outlining a bull-case scenario where the stock could more than double from its current levels.
A Mizuho analyst on Thursday presented a bull-case scenario in which shares of Affirm (AFRM) could surge past $200, arguing that the market consensus is significantly undervaluing the buy-now-pay-later firm's future earnings power. The stock was trading around $71.12 at the time of the note's publication.
Underestimated Earnings Power
In a research note, Mizuho analyst Dan Dolev stated that the "consensus is grossly underestimating AFRM's long-term earnings power." While maintaining an official Outperform rating and a $100 price target on the stock, Dolev's more optimistic model projects Affirm could generate well over $10 in GAAP earnings per share (EPS) by 2030.
This forecast is roughly double the current consensus estimate and substantially higher than the company's own guidance of $3 to $4 in EPS, which was provided during its 2026 analyst day, according to the note.
Key Growth Drivers
Dolev identified three primary factors that could drive this significant outperformance:
 Ad
- Gross Merchandise Volume (GMV): The analyst sees potential for up to 50% upside to GMV, driven by the momentum of Affirm's payment card and broader network effects. This factor alone could contribute an additional $4 to EPS.
- Revenue and Costs: A favorable product mix and the potential acquisition of a bank license could boost the company's revenue less transaction costs.
- Agentic Commerce: Dolev highlighted the rise of AI-powered shopping agents, which would transact on behalf of consumers. He argued that a "rational, tireless AI robot shopper will optimize on price and systematically favor 0% APR checkout," directly benefiting Affirm's core offering.
Path to a $200 Valuation
To arrive at the $200-plus valuation, the Mizuho note analyzed a peer group of over 700 companies with market capitalizations above $10 billion and expected two-year EPS growth exceeding 50%. This group trades at a price-to-earnings multiple of 23x to 24x.
Applying that multiple to a present value of approximately $9 in 2028 EPS, Dolev's model suggests a potential share price "north of $200." This presents a significant upside from both the current trading price and the analyst's official price target.
Read next
More on Stocks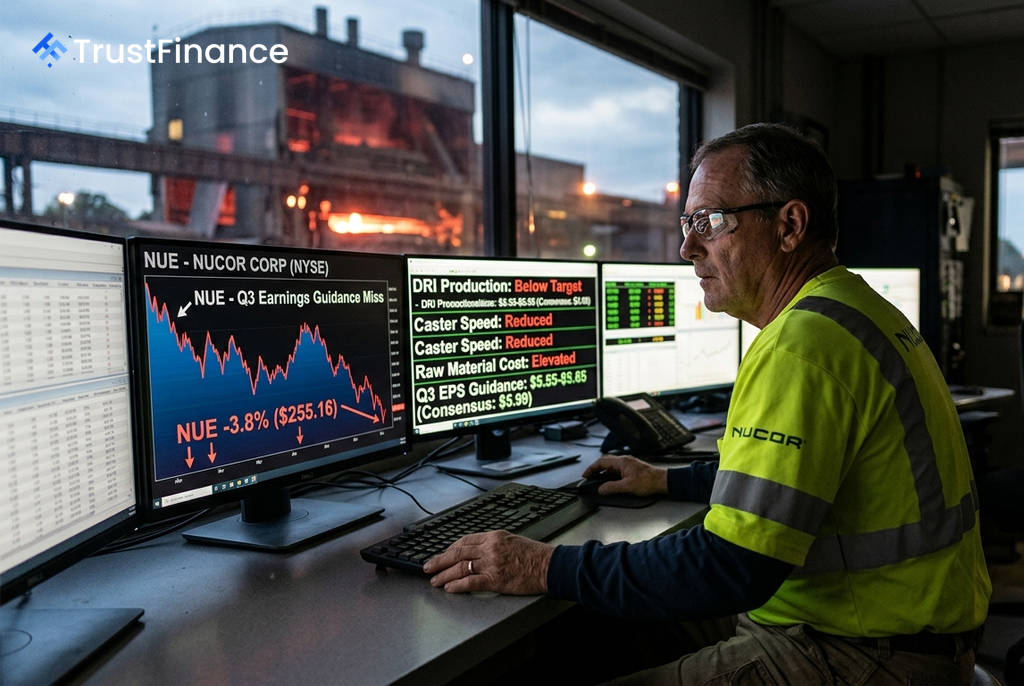
Nucor Stock Slides After Q3 Earnings Guidance Misses Analyst Forecasts
Nucor Corporation (NUE) shares fell after the company projected third-quarter earnings of $5.55 to $5.65 per share, below the Wall Street consensus of $5.99, citing the absence of significant one-time gains from the prior quarter.
Disney Asks Court to Halt FCC License Review, Alleges Political Pressure From Trump
The Walt Disney Company has filed a legal challenge to stop the Federal Communications Commission from conducting an early review of its ABC station licenses, claiming the regulator is acting on President Trump's directives.
Starbucks Settles Florida Lawsuit Over Diversity Policies for $1 Million
The coffee giant has agreed to settle a lawsuit with Florida's attorney general, pledging to avoid race- or sex-based quotas in its employment practices and pay $1 million to cover the state's litigation costs.
Latin American Stocks Rally as Dollar Slides After Fed Rate Hike
Equities and currencies across Latin America gained as a pullback in the U.S. dollar following the Federal Reserve's latest interest rate increase boosted commodity-linked assets and improved investor sentiment toward emerging markets.