
Story
S&P Revises Polaris Outlook to Positive on Deleveraging and Utility Vehicle Demand
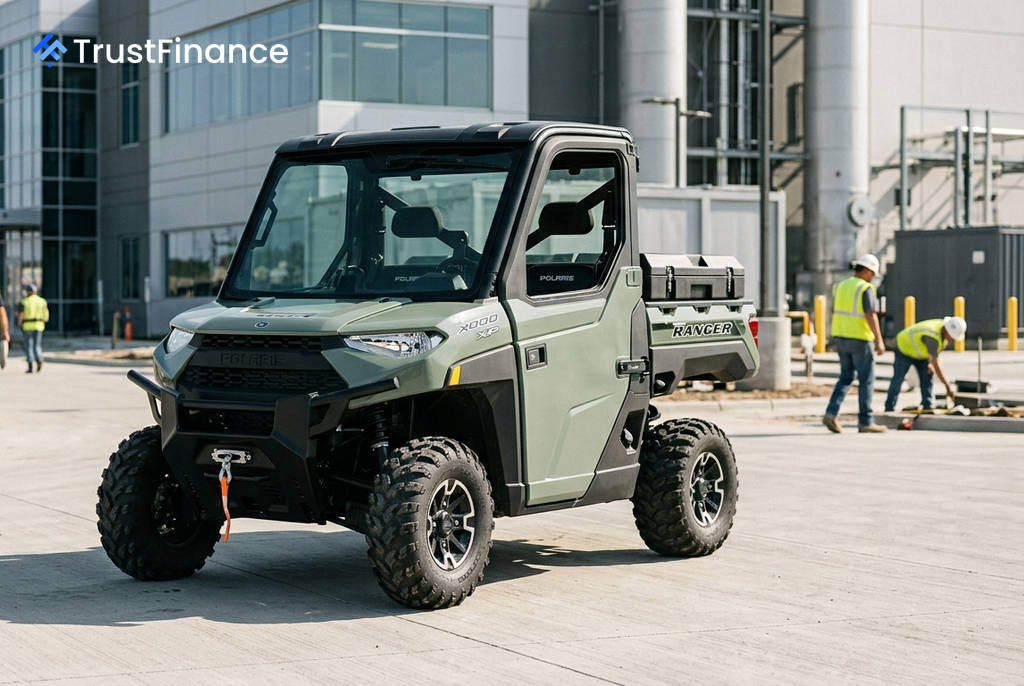
S&P Global Ratings has revised its outlook on Polaris Inc. (NYSE:PII) to positive from negative, citing expectations for significant deleveraging and resilient demand for its utility vehicles. The ratings agency affirmed its 'BBB-' issuer credit rating on the powersports manufacturer, signaling confidence in the company's financial trajectory.
Rating Rationale
The positive outlook is based on S&P's forecast that Polaris will outperform previous revenue and EBITDA assumptions for 2026 and 2027. The agency highlighted several key factors supporting its decision:
- Deleveraging: S&P projects Polaris will reduce its lease-adjusted leverage to the mid-2x area in 2026 and to approximately 2x by the end of 2027.
- Margin Improvement: The company's EBITDA margin is expected to increase to about 10% by 2027, aided by cost control measures and better alignment of shipments with retail sales.
- Stronger Liquidity: S&P also upgraded its liquidity assessment for Polaris to strong from adequate, noting sufficient anticipated covenant headroom.
Shifting Market Dynamics
The ratings action comes amid a divided powersports market. While North American retail sales in the sector rose 5% year-over-year in the second quarter of 2026, this growth was driven almost entirely by strong utility and commercial demand, including from data center construction projects.
 Ad
In contrast, recreational demand fell by a mid-teens percentage, according to S&P. The agency attributed this weakness to higher interest rates and a delayed replacement cycle for big-ticket discretionary items. For the remainder of 2026, S&P expects overall industry growth to be flat to up by a low-single-digit percentage.
Strategic Positioning and Outlook
Polaris appears well-positioned to capitalize on current market trends, as its utility and commercial offerings account for about 70% of its powersports segment revenue. S&P also viewed the company's first-quarter 2026 sale of the Indian Motorcycles brand as a "modestly credit positive" move.
Although the divestiture removed approximately $460 million in 2025 revenue, it also shed a business that was producing negative EBITDA. S&P estimates the sale will add about $50 million to Polaris's adjusted EBITDA on an annualized basis. The ratings firm projects Polaris's total revenue will increase by 2% to 5% through 2027, supported by its utility powersports and marine segments.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.