
Story
Salesforce Shares Surge as AI-Driven Earnings Beat and Strong Outlook Validate Strategy
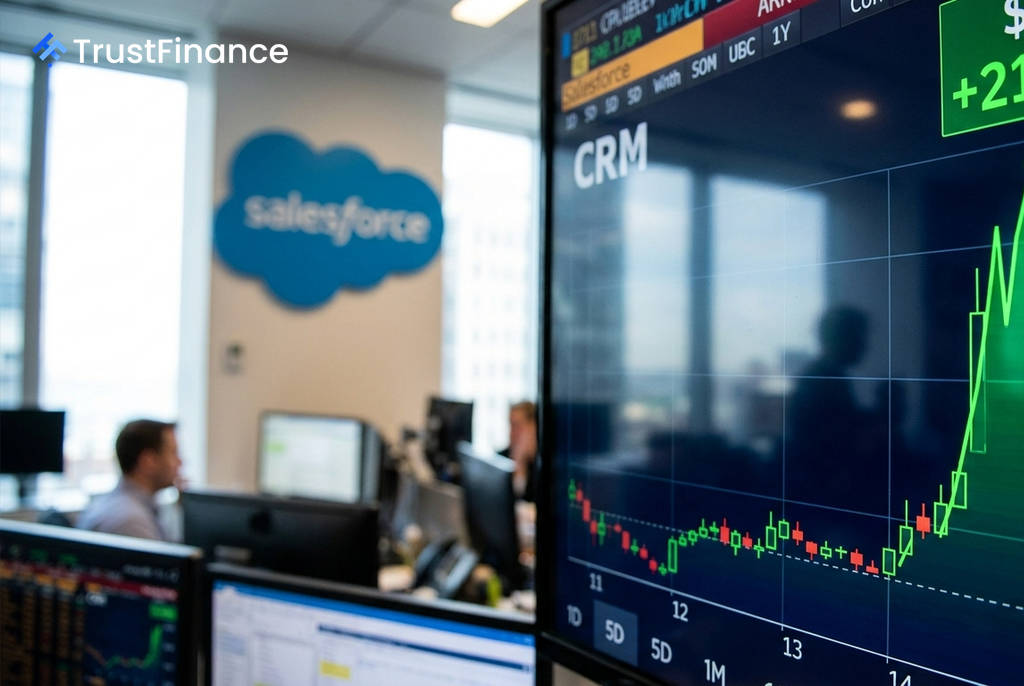
Salesforce Inc. (CRM) shares surged after the company posted fiscal second-quarter earnings that significantly beat Wall Street estimates and raised its full-year guidance, providing the strongest evidence yet that its heavy investment in artificial intelligence is translating into substantial revenue growth.
The business software giant reported adjusted earnings per share of $5.90 on revenue of $11.35 billion, handily beating the consensus estimates of $3.27 and $11.32 billion, respectively. Following the announcement, the company's stock was trading up approximately 22%.
AI Growth Takes Center Stage
The report's key highlight was the tangible monetization of Salesforce's AI initiatives. The company disclosed that its Agentforce product reached $1.5 billion in annual recurring revenue (ARR), a staggering 240% increase year-over-year. Combined with its other data-focused offerings, Salesforce's total AI and data ARR now stands at $3.9 billion, up 210% from the prior year.
Adding to the positive sentiment was the announcement of "Claudeforce," a new partnership with AI firm Anthropic. This integration layers Anthropic's Claude AI model directly into Salesforce's platform. Analysts at TD Cowen called the partnership a potential "trajectory changer" for the company and raised their price target to $280.
Re-acceleration and Profitability
 Ad
A crucial metric for investors, current Remaining Performance Obligation (cRPO), grew 14% in constant currency, its fastest pace in four years. This figure, which represents future revenue under contract, signals a potential re-acceleration in growth. Management guided for cRPO growth to remain around 14% in the third quarter, ahead of analyst expectations.
Salesforce also demonstrated strong operational efficiency. Free cash flow surged 81% year-over-year to $1.1 billion, and the company maintained a non-GAAP operating margin of 34.3%. In a sign of confidence, management boosted its full-year adjusted EPS forecast by nearly $2.60 to a range of $16.67 to $16.71.
Market Outlook and Analyst Reaction
The strong results prompted a wave of positive analyst revisions. Jefferies lifted its price target to $300, citing the first cRPO beat in three quarters, while Mizuho and Cantor Fitzgerald also raised their targets. Upcoming catalysts for the company include its Dreamforce conference, where further details on AI products are expected.
However, some skepticism remains. Analysts at Wells Fargo, while raising their price target to $230, maintained an "Equal Weight" rating, awaiting more definitive proof of sustained organic subscription growth. The key risk for investors is whether the company can meet its guidance for organic growth to accelerate through the second half of the fiscal year, which is crucial for sustaining the positive AI narrative.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.