
Story
Prologis Dividend Growth Draws Investor Focus Amid Valuation Concerns
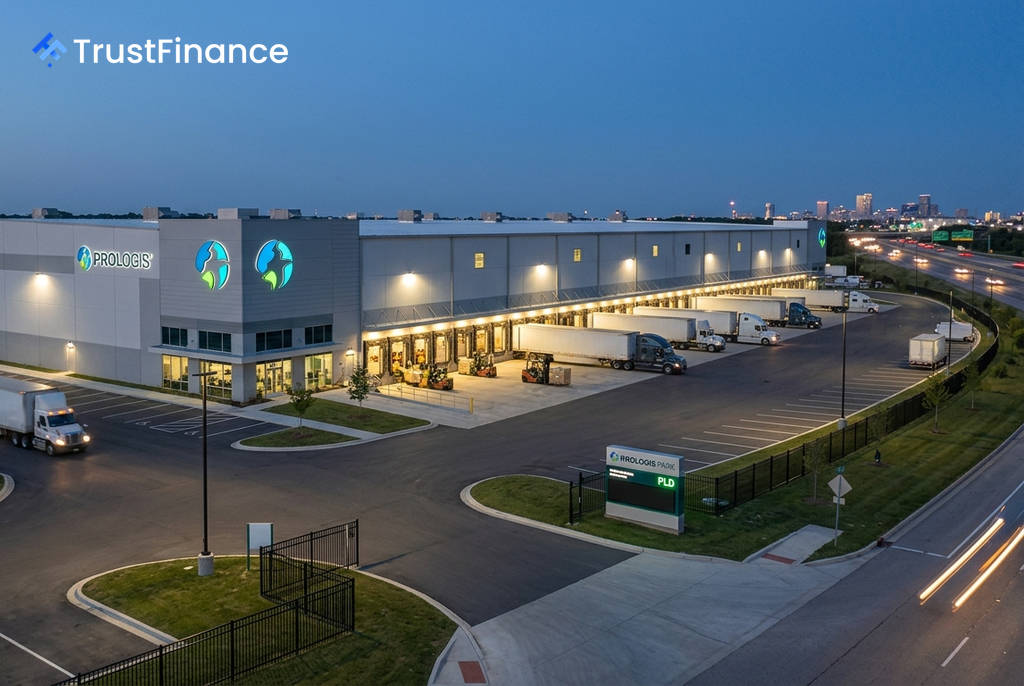
Prologis (PLD), a leading industrial real estate investment trust, is presenting a complex picture for investors, with its strong record of dividend growth running up against valuation metrics that suggest potential overextension. The company currently offers a 3.1% dividend yield at a price of $136.66, backed by 12 consecutive years of increased payouts to shareholders, according to a report from Investing.com.
A Record of Payout Growth
The central pillar of the investment case for Prologis is its consistent and rapid dividend expansion. The company’s dividend per share has grown by approximately 70% over the past five years, rising from $2.52 to a current annualized rate of $4.28.
This growth has been fueled by strong financial performance, with revenue nearly doubling from $5.16 billion in 2021 to a projected $9.19 billion in 2025. This top-line growth is supported by what the source describes as durable tailwinds from e-commerce logistics and a strategic expansion into the data center market.
Valuation and Market Headwinds
Despite the positive operational narrative, the stock's current valuation gives some analysts pause. Prologis trades at a high price-to-earnings (P/E) ratio of 30.9x and an enterprise value-to-EBITDA multiple of 23.5x.
A fair value model from InvestingPro, cited in the report, estimates the stock’s intrinsic value at $115.53, implying a potential downside of -15.5% from current levels. This is compounded by several market headwinds, including normalizing occupancy rates from post-pandemic peaks and reported pressure on market rents amid a slowdown in U.S. leasing demand.
 Ad
Wall Street Analysts Remain Divided
The bearish signal from the quantitative valuation model contrasts sharply with the broader Wall Street consensus. The average analyst price target suggests a potential upside of +17.1%, highlighting a significant divergence in outlook.
Recent ratings from major investment banks reflect this split opinion:
- Barclays: Overweight rating with a $119 price target.
- RBC Capital Markets: Sector Perform rating with a $117 target.
- BMO Capital Markets: Underperform rating with a $104 target.
This division indicates that while Prologis's dominant market position and growth story are recognized, investors and analysts are weighing those strengths against near-term cyclical pressures and a premium stock price.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.