
Story
Palantir's Valuation Soars to 95x Forward P/E, But Models Signal 25% Downside Risk
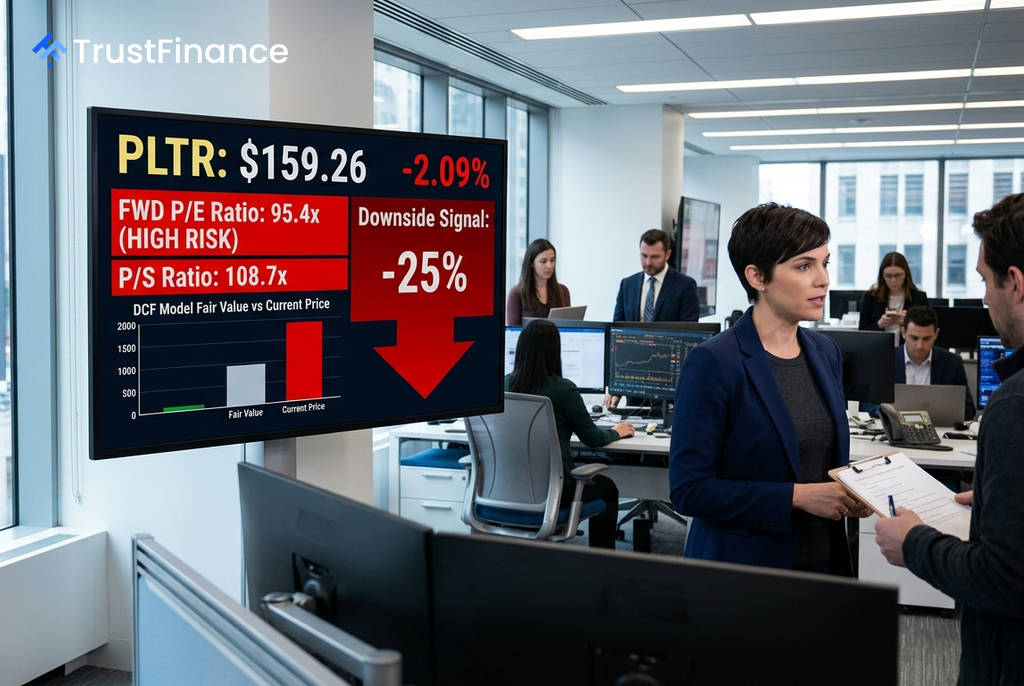
Palantir Technologies (NYSE: PLTR) is trading at valuation levels rarely seen even among high-growth software companies, with a forward price-to-earnings ratio of over 95x. While the company's fundamental performance is strong, an analysis by Investing.com suggests its stock price has far outpaced its financial reality, with valuation models indicating a potential 25% downside.
Stretched Valuation Metrics
Palantir's valuation is in rarefied territory, marked by exceptionally high multiples that signal significant investor optimism. The analysis highlights several key figures:
- Forward P/E Ratio: 95.4x, far exceeding the S&P 500's average of under 25x and the typical multiples of other AI software firms, which rarely surpass 60x.
- Price-to-Sales Ratio: 108.74x.
- Price-to-Book Ratio: 64.3x.
Fair value models based on Discounted Cash Flow (DCF) and peer comparisons both point to a potential downside of between 25% and 25.3% from current prices, according to the Investing.com report. While the Wall Street consensus price target of $189.24 implies about 12.5% upside, it underscores the wide gap between current trading levels and model-driven valuations.
Growth Story vs. Price
 Ad
The company's operational performance remains robust, but the central question for investors is whether this growth is already more than priced in. Recent quarters have shown year-over-year revenue growth between 85% and 93%, with forecasts for 2026 earnings-per-share growth hitting 170.6%.
Palantir also boasts strong profitability, with an EBITDA margin of 32.2% and a net income margin of 36.3%. The company maintains a healthy balance sheet with a net cash position of $6.95 billion. However, its free cash flow yield is just 0.4%, and with no dividend, returns are entirely dependent on share price appreciation.
Market Outlook and Analyst Divide
The extreme valuation has created a split among analysts. Firms like BofA and Oppenheimer remain bullish on the company's prospects, while others, including Citi and Jefferies, have urged caution due to the high multiples and potential for volatility.
The market appears to have priced in years of flawless execution. The core risk for investors is that any slowdown in Palantir's aggressive growth trajectory could trigger a sharp downward rerating of the stock. While continued success in the AI sector could eventually justify today's price, the margin for error is exceptionally thin.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.