
Story
Jefferies Initiates Coverage on Molbio Diagnostics with 'Buy' Rating
Summary
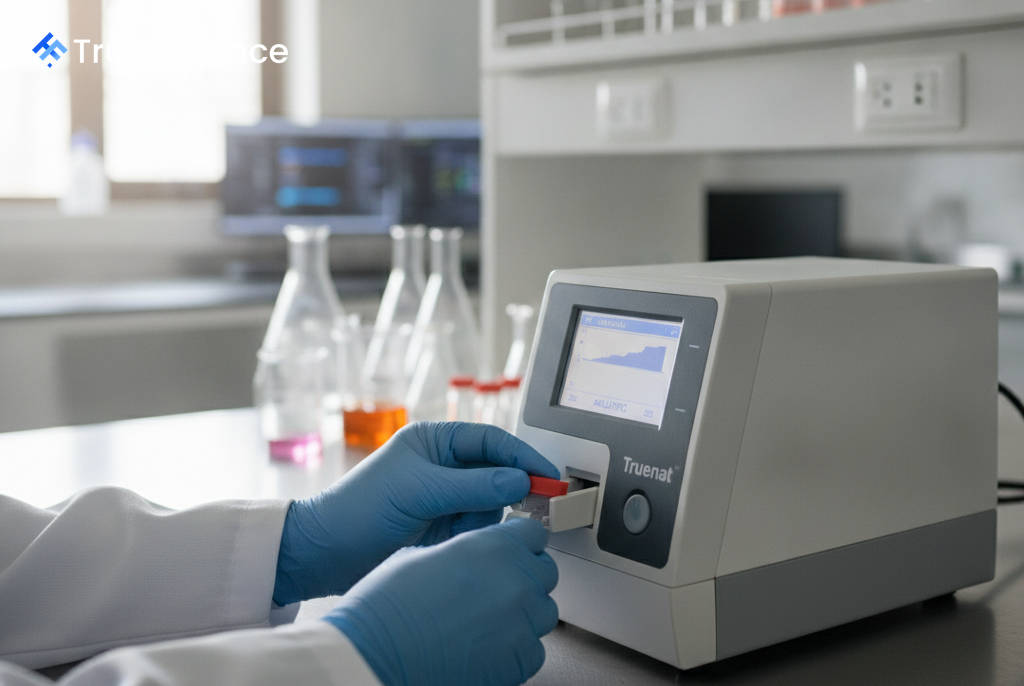
Jefferies has initiated coverage on Molbio Diagnostics, naming it a top pick in India's medical supplies sector with a 'Buy' rating and a price target of INR 1,600, citing the strength of its point-of-care diagnostics platform.
Jefferies has identified Molbio Diagnostics as a high-conviction pick in India’s medical devices sector, initiating coverage with a 'Buy' rating and a price target of INR 1,600. The brokerage firm's positive outlook is based on the med-tech company's successful commercialization of its innovative molecular diagnostics platform.
Growth Driven by Flagship Platform
Jefferies highlighted Molbio’s flagship Truenat platform, which it notes operates in an oligopolistic market. Developed over 13 years, Truenat is a portable, battery-operated molecular diagnostics system that enables high-quality testing at the point of care for approximately 30 diseases. The platform accounts for an estimated 86% of the company's fiscal 2026 sales.
The research note points out Truenat's competitive advantages over rival platforms like GeneXpert, stating it is lighter, faster, and less dependent on infrastructure. With Molbio's revenue at roughly $130 million compared to GeneXpert's $3 billion scale, Jefferies sees significant growth potential for the patent-protected technology.
Strong Financial Projections
 Ad
Jefferies forecasts a strong financial trajectory for Molbio through fiscal years 2026-2029. The firm projects a revenue compound annual growth rate (CAGR) of 22% and a profit after tax CAGR of 47%, driven by scaling existing products and increasing operating leverage.
Key factors expected to fuel this growth include:
- A sharp margin expansion of approximately 830 basis points.
- Rising test-kit capacity utilization, projected to increase from 58% in FY26 to 77% by FY29.
- The scaling of its Optrascan digital pathology platform, expected to reach 11% of sales by FY29.
- Declining employee and operating costs as a percentage of sales.
Jefferies' valuation is based on a target multiple of 40x the company's estimated September 2028 earnings per share.
Read next
More on Stocks
US Transportation Secretary Pushes to Expedite Aircraft Certification Amid China Competition Concerns
Transportation Secretary Sean Duffy stated the U.S. must speed up its aircraft approval process to maintain a competitive edge against China and encourage private investment in aviation innovation. The move follows existing FAA efforts to modernize certification.

Jefferies Identifies Three Biotech Firms with Blockbuster Drug Potential
Investment firm Jefferies has highlighted Delphia Therapeutics, Axsome Therapeutics, and BridgeBio Pharma as undervalued biotech companies with strong late-stage pipelines and significant commercial prospects.
Synopsys Shares Rise on OpenAI Partnership and Strong Revenue Forecast
Chip design software leader Synopsys is partnering with OpenAI on a revenue-sharing basis to develop a specialized AI model for semiconductor design, a move that boosted its stock and financial outlook.

Peoples Bancorp Stock Drops on $728 Million All-Stock Deal for Capital Bancorp
Shares of Peoples Bancorp fell over 5% after the bank announced it would acquire Capital Bancorp in an all-stock transaction valued at approximately $728.1 million, raising investor concerns about share dilution.