
Story
Goldman Sachs Upgrades Swissquote to 'Buy' on Core Business Strength

Summary
Goldman Sachs upgraded Swissquote to 'buy' from 'neutral' and raised its price target, citing robust growth in securities trading and forex that is expected to more than compensate for a slowdown in crypto-related revenue.
Goldman Sachs has upgraded Swissquote Group to "Buy" from "Neutral", citing confidence that the online bank's core operations will more than offset the ongoing weakness in its cryptocurrency business. Following the report, shares in Swissquote rose more than 6% in Wednesday's trading.
Analyst's Rationale
The upgrade is underpinned by Goldman's expectation for stronger earnings from securities trading, foreign exchange (forex), and net interest income. The investment bank's analysts believe this momentum will be sufficient to counteract a decline in revenue from crypto-related activities.
Goldman's forecast for Swissquote's 2026 securities and eForex revenue is SFr507 million, which is 6% above the Visible Alpha consensus of SFr477 million. Conversely, its forecast for net crypto assets income is SFr61 million, 17% below the consensus of SFr74 million, highlighting the bank's diverging view from the market on the drivers of Swissquote's future performance.
Revised Forecasts and Price Target
Goldman Sachs raised its 12-month price target for Swissquote to SFr50 from SFr48, implying a potential upside of 21.5% from the stock's SFr41.16 closing price mentioned in the report. The bank's updated financial models project a 2026 pre-tax profit of SFr411 million, which is 5% above the market consensus and 7% ahead of Swissquote's own guidance.
 Ad
Key forecast adjustments include:
- 2026 Revenue: Goldman's forecast of SFr795.1 million is 5% above the company's guidance of SFr760 million.
- 2026 Pre-tax Profit: The SFr411 million estimate is 7% higher than the company's SFr385 million guidance.
- Earnings Per Share (EPS): Estimates were raised for 2026 (to SFr2.34), 2027 (to SFr2.57), and 2028 (to SFr2.97).
Market Context and Valuation
Swissquote's shares have underperformed peers over the past year, falling 23% while European retail investment platforms rose an average of 18%. Goldman attributes this lag to the downturn in the digital asset market, noting that crypto-related income accounted for about 12% of Swissquote's revenue in 2025, down from a peak of 22% in 2021.
However, the report highlighted positive underlying trends in the non-crypto business, including a 15% year-on-year growth in trading accounts. Goldman also noted that Swissquote trades at a discount to its peers, with a 2027 estimated price-to-earnings ratio of 15.9 times, compared to a peer average of 18.1 times. The broker's price target is based on an unchanged target multiple of 18 times estimated earnings.
Read next
More on Stocks
Global Fuel Subsidies More Than Double as Middle East Tensions Push Oil Prices Higher
The number of countries subsidizing fuel has surged to 38 from 16 in just four months as governments grapple with oil prices nearing $110 a barrel amid escalating geopolitical conflict.
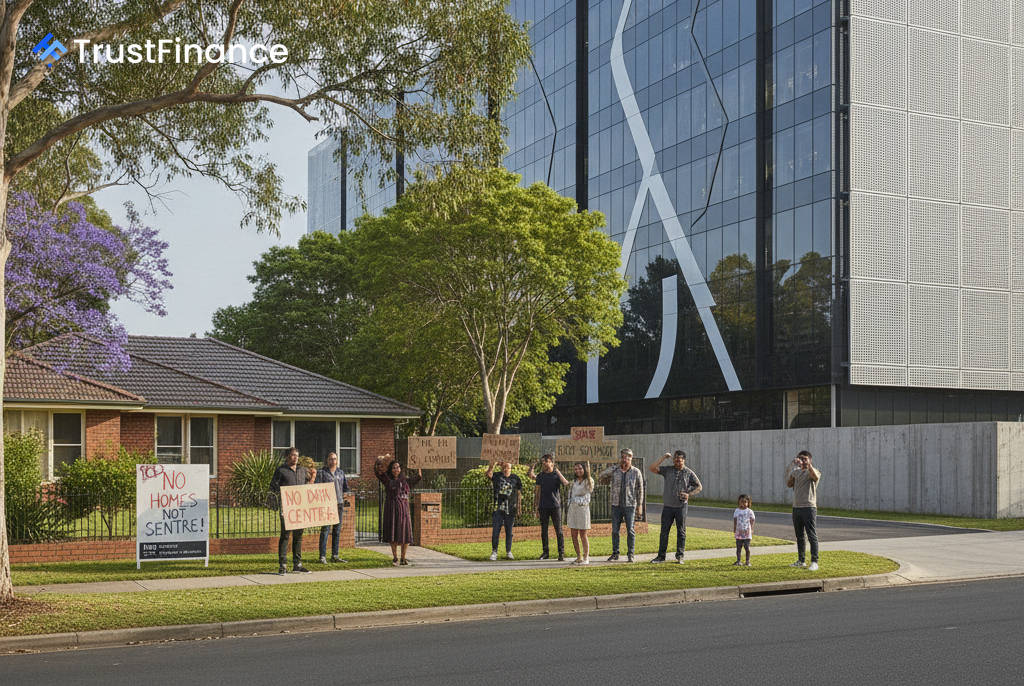
Goodman Group Scraps A$1.2 Billion Sydney Data Center Amid Local Opposition
Australian property giant Goodman Group has withdrawn its development application for a 90-megawatt data center in a Sydney suburb, citing community opposition and a changing regulatory environment.

UK Tribunal Allows Part of Consumer Lawsuit Against Apple and Amazon to Proceed
A UK appeals court has allowed a consumer lawsuit against Apple and Amazon to proceed, focusing on allegations that the tech giants colluded to inflate prices for Apple products on Amazon's marketplace.

Entain Shares Fall as Brazil Betting Ban Pushes 2026 Earnings to Low End of Guidance
The sports betting and gaming group's shares dropped after a provisional ban in Brazil forced it to guide its 2026 core earnings and revenue growth towards the lower end of its targets.