
Story
Eli Lilly's Growth Soars on Drug Sales, But Lofty Valuation Poses Investor Dilemma
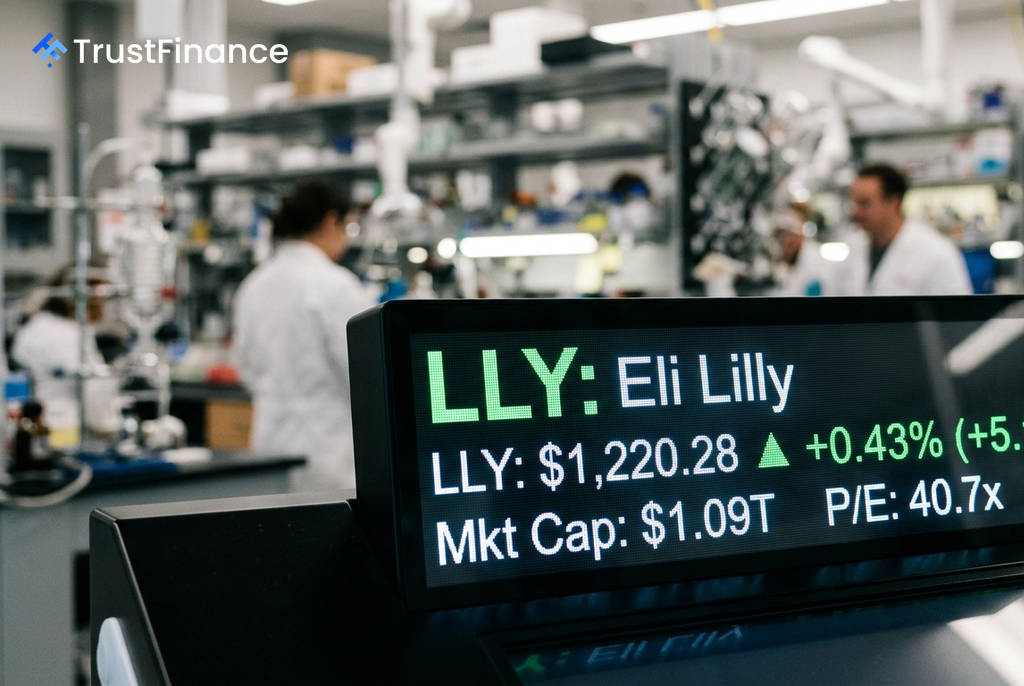
Eli Lilly's (NYSE: LLY) stock continues its powerful ascent, fueled by exceptional growth in its incretin-based drugs, Zepbound and Mounjaro. A recent analysis from Barclays reinforces the bull case by highlighting the franchise's accelerating momentum, but the company's trillion-dollar valuation is forcing investors to weigh its outstanding fundamentals against a stock price that may have already factored in future success.
The Bull Case: Incretin Dominance
A constructive note from Barclays underscores that Eli Lilly's growth engine shows no signs of slowing down, citing impressive prescription volume data. The firm's analysis points to the company's near-duopoly position in the incretin market.
Key growth metrics from the report include:
- Zepbound US Prescriptions: Grew 11% quarter-over-quarter and a staggering 60% year-over-year.
- Mounjaro US Prescriptions: Increased 12% quarter-over-quarter and 42% year-over-year.
- Market Share: The company now commands a dominant 60.9% share of the U.S. incretin market.
Barclays also noted that volume growth has historically more than offset any pricing pressures. The firm anticipates further catalysts from upcoming Phase 2 data presentations and the company's first investor event in five years, scheduled for December.
A Premium on Perfection
 Ad
Despite the operational strength, the primary challenge for investors is the stock's valuation. Eli Lilly currently trades at a trailing price-to-earnings (P/E) ratio of 40.7, a significant premium that reflects high market expectations for continued, flawless execution.
While the forward P/E ratio is a more moderate 33.4, it is contingent on the company's ability to sustain its rapid growth. According to Investing.com's fair value model, the stock has just 0.5% of potential upside from its current price of approximately $1,220. This stands in contrast to the broader analyst consensus, which projects an average upside of 10.1%.
Balancing Fundamentals and Risk
The company's underlying financial health is exceptionally strong, supporting the bullish outlook. As of June 30, 2026, key financial metrics underscored its operational excellence:
- Revenue Growth (YoY): 49.6%
- EPS Growth (YoY): 94.5%
- Return on Equity (ROE): 102.4%
- Piotroski Score: A perfect 9 out of 9, indicating peak financial health.
However, one potential area of concern is the company's balance sheet. Eli Lilly's debt-to-equity ratio is elevated at 139%, a result of leveraging up for acquisitions to expand its pipeline beyond incretins. While interest coverage is reportedly adequate, this level of debt is a factor for investors to monitor in the current economic environment.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.