
Story
Dell's AI Revenue Soars Amid Concentration Risks, HPE Emerges as Value Alternative
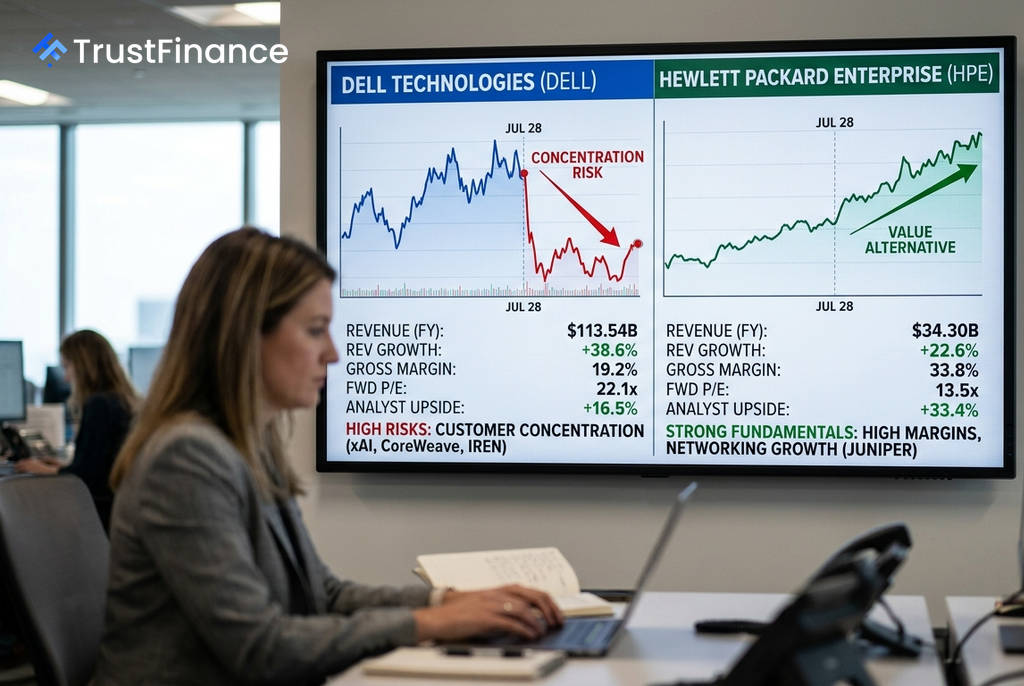
A recent market sell-off has highlighted the divergent strategies of two enterprise technology giants, Dell Technologies (DELL) and Hewlett Packard Enterprise (HPE), as they compete for dominance in the artificial intelligence infrastructure market. While Dell has captured investor attention with explosive AI-driven revenue growth, concerns over its customer concentration and margin pressure are bringing HPE's more balanced value proposition into focus.
Dell's High-Growth, High-Risk AI Bet
Dell has seen its stock deliver a +233.6% return over the past year, fueled by its leadership in the AI server market. The company has guided for approximately $60 billion in AI server revenue by fiscal year 2027. However, this rapid growth comes with significant risks that were recently brought to light.
According to a July 27 note from Evercore ISI, an estimated 70% of Dell's projected fiscal 2027 AI server revenue is expected to come from just three customers. This heavy concentration, coupled with concerns over the relatively thin 19.2% gross margins on its AI servers, contributed to a 14.3% stock decline on July 28. Despite the risks, Dell's forward price-to-earnings (P/E) ratio stands at 22.1x on the back of strong earnings estimates.
HPE's Diversified Value Proposition
Hewlett Packard Enterprise presents a contrasting investment case, focusing on a broader strategy that includes networking and hybrid cloud services. The company's stock trades at a more modest 13.5x forward P/E, and analysts see a potential upside of +33.4%, compared to +16.5% for Dell, according to the source data.
HPE's strengths lie in its financial health and diversification. The company boasts a superior gross margin of 33.8% and an attractive free cash flow yield of 6.0%. Its networking segment, bolstered by the integration of Juniper Networks, saw revenue surge 150% year-over-year. Positive catalysts include a recent price target increase to $74 from Citi and its selection by the U.S. Department of Energy for key AI and supercomputing research projects.
 Ad
Market Weighs Divergent Paths
The choice for investors hinges on their appetite for risk and their outlook on the AI market's evolution. Dell offers direct, high-octane exposure to AI server demand, while HPE provides a more diversified and attractively valued entry point into enterprise AI.
Key comparative metrics include:
- Valuation: HPE's 13.5x forward P/E is significantly lower than Dell's 22.1x.
- Margin Quality: HPE's 33.8% gross margin provides a much thicker cushion than Dell's 19.2%.
- Revenue Concentration: Dell's reliance on a few key customers is a primary risk, while HPE's business is more diversified.
- Analyst Upside: Wall Street consensus projects +33.4% upside for HPE, more than double the +16.5% seen for Dell.
The next major test for both companies will be their upcoming earnings reports, with HPE scheduled for around September 1, 2026, and Dell for September 3, 2026.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.