
Story
Celsius Holdings Downgraded to 'Hold' by Deutsche Bank on Delayed Recovery, Valuation Concerns
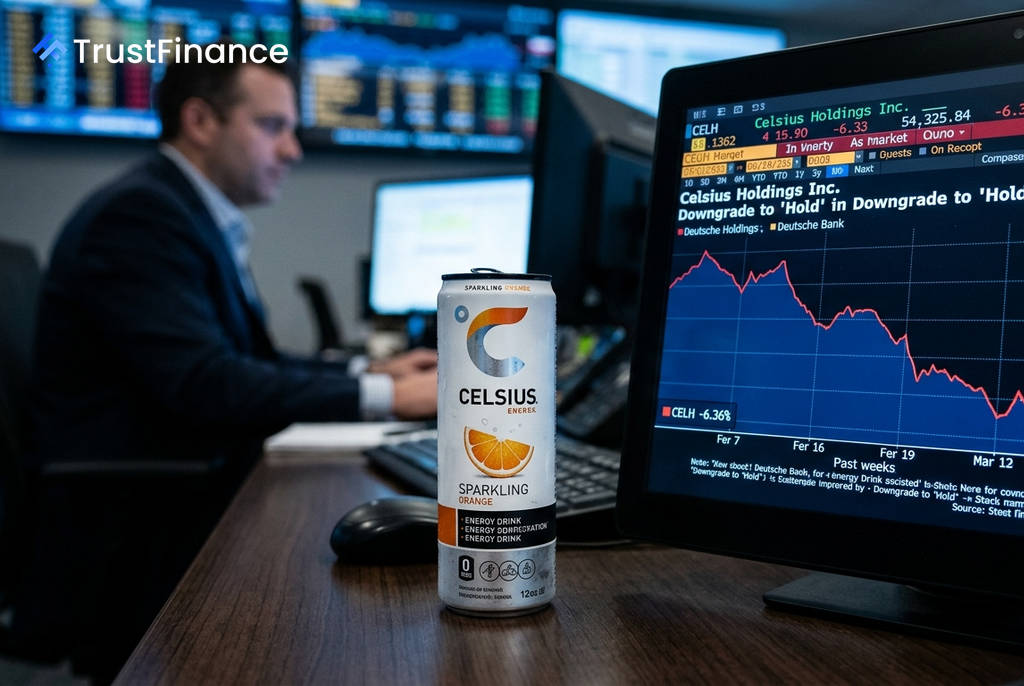
Deutsche Bank has downgraded Celsius Holdings (NASDAQ: CELH) to Hold from a previous Buy rating, citing a combination of weakening brand trends and a stock valuation that appears to have outrun the company's near-term fundamentals. While the bank raised its price target on the energy-drink maker to $35 from $30, it noted that the stock's recent price of $35.34 leaves little room for appreciation.
Valuation Outpaces Fundamentals
A key factor in the downgrade is the stock's recent performance. According to Deutsche Bank, Celsius shares have rallied approximately 30% over the past month, pushing investor expectations to a level that may be difficult for the business to support.
The bank's analysts suggested this optimism is partly fueled by hopes that shareholder or activist pressure could force operational or strategic changes. However, Deutsche Bank stated that the potential impact of such changes is difficult to value with any confidence at this time.
Recovery Timeline Pushed to 2027
Deutsche Bank highlighted that core trends for the Celsius brand deteriorated further in the second quarter, with both revenue and profitability falling short of expectations. The firm reported that Celsius management has pushed the timeline for a meaningful recovery out to fiscal 2027.
 Ad
Analysts also pointed to challenges across the company's broader portfolio. The Alani Nu brand is beginning to face more difficult growth comparisons as the benefits from its transition into PepsiCo's distribution network begin to fade, potentially making it harder to drive a clear acceleration in overall growth.
Analyst Outlook and Forecasts
Looking ahead, Deutsche Bank's financial forecasts for Celsius remain below the market consensus, signaling potential downside risk if investor expectations do not moderate.
- Fourth-Quarter Forecast: The bank projects revenue of $738 million, nearly 4% below consensus, and adjusted EBITDA of $149 million, which is almost 10% below consensus.
- Fiscal 2027 Estimates: The firm's revenue and adjusted EBITDA estimates for the full year remain 5% and 12% below consensus, respectively.
Deutsche Bank attributed its cautious outlook to factors including input-cost inflation, an unfavorable brand mix, and increased spending required to rebuild the core Celsius business. The bank said its stance could become more positive with tangible evidence of stronger consumption and improved execution.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.