
Story
Amgen Nears 52-Week High, But Valuation and Analyst Targets Signal Caution
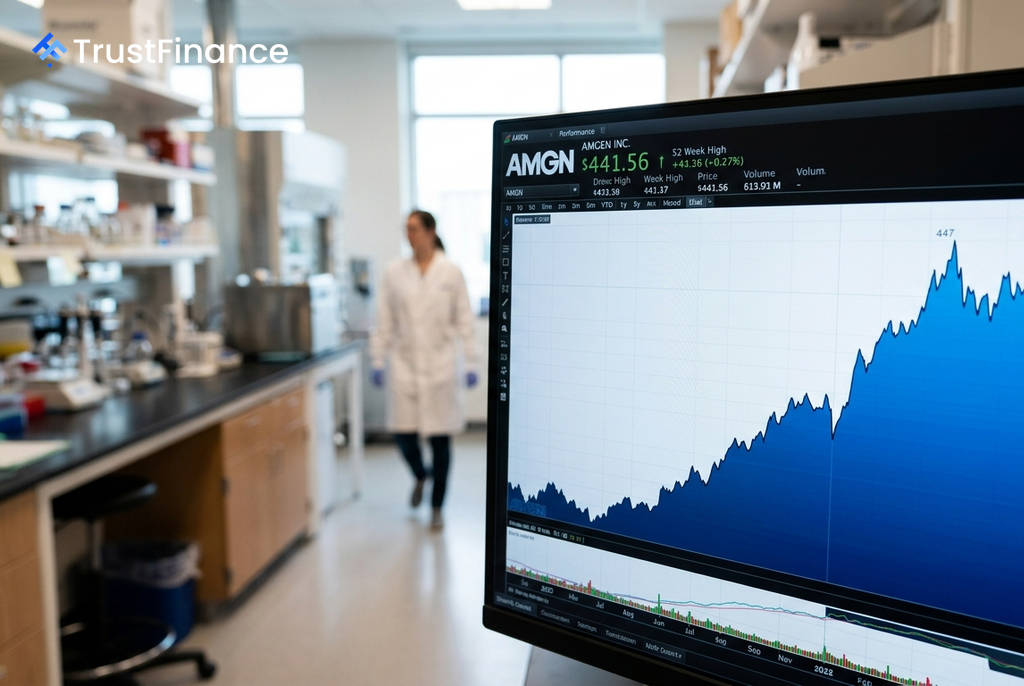
Amgen Inc. (NASDAQ: AMGN) is trading just shy of its 52-week high after a powerful +55.4% rally over the past year, but valuation metrics and analyst consensus suggest further gains may be limited. The biotech giant's strong operational performance is being weighed against a stretched valuation and risks from its recent large-scale acquisition.
Strong Performance Meets Stretched Valuations
As of September 3, Amgen's stock was trading at $441.56, near its 52-week peak of $447.03, according to data from Investing.com. This run-up has pushed its valuation to levels that imply limited near-term upside.
Investing.com's own Fair Value model estimates a price of $450, suggesting only +1.9% potential from current levels. More pointedly, the consensus target among Wall Street analysts sits 10.8% below the stock's current price. Key valuation multiples reflect this premium, with a trailing price-to-earnings (P/E) ratio of 27.4x and an EV/EBITDA multiple of 16.0x.
While technical indicators confirm a strong upward trend, some are flashing caution. The weekly Relative Strength Index (RSI) is at 72.8, a level widely considered to be in overbought territory, which can sometimes precede a price correction.
Solid Operations Weighed by Acquisition Debt
The rally is backed by solid fundamentals. Amgen has compounded its revenue from $25.98 billion in 2021 to a projected $36.75 billion in 2025, per the source. The company also generates robust free cash flow, averaging approximately $8.6 billion annually over the last five years, which supports its 2.3% dividend yield.
 Ad
However, the company's balance sheet is heavily leveraged following its acquisition of Horizon Therapeutics. The deal has pushed Amgen's debt-to-equity ratio to a substantial 490.3%. This risk has been magnified by recent regulatory setbacks for Tavneos, a key drug from the Horizon portfolio, which has had its approval revoked in the EU and suspended in the UK, citing unreliable trial data.
Future Growth Hinges on Pipeline Success
For investors, the bull case now largely depends on Amgen's drug pipeline delivering significant new growth drivers. Two assets are in the spotlight:
- Tezspire: Developed with AstraZeneca, this drug recently met its primary endpoints in a Phase 3 trial for eosinophilic esophagitis, potentially expanding its use beyond severe asthma into a new market.
- MariTide: This is Amgen's candidate for the lucrative obesity and diabetes market, dominated by GLP-1 drugs. Success with MariTide would place Amgen as a major competitor in one of pharma's fastest-growing sectors.
While these pipeline assets offer significant potential, they represent future opportunities that must still clear clinical and regulatory hurdles. Investors are now balancing the company's proven operational strength against a full valuation and the inherent risks of drug development.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.