
Story
Woolworths Faces Margin Pressure as Rival Coles Reports Strong Profit Growth
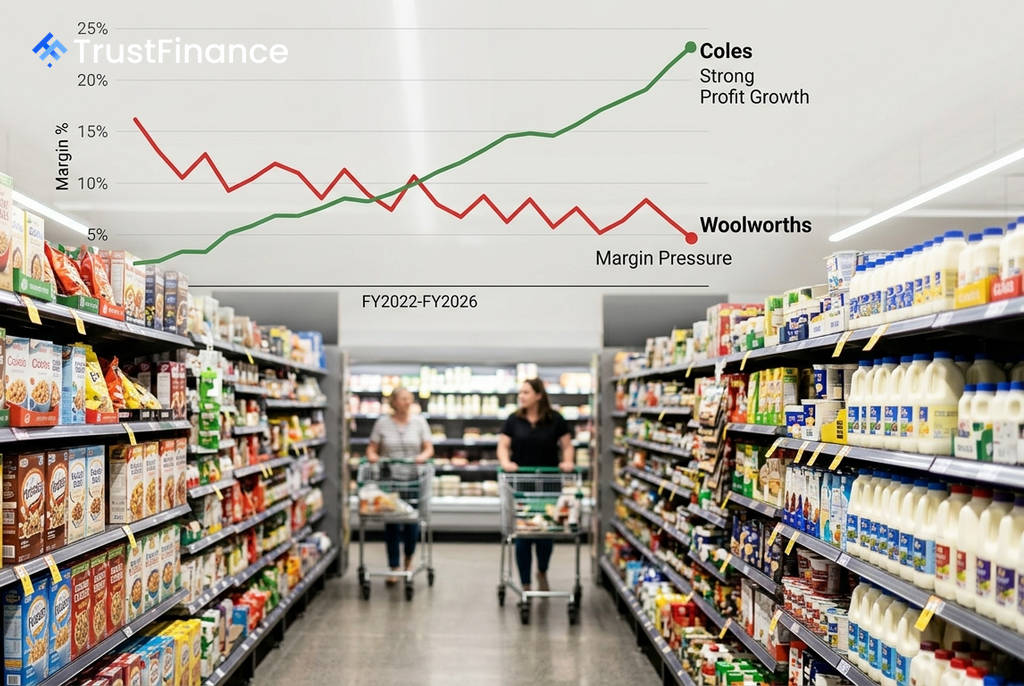
Woolworths Group Ltd (WOW) faces a high benchmark for its upcoming full-year 2026 earnings report, scheduled for August 26. The pressure comes after its primary competitor, Coles Group Ltd (COL), posted robust results that surpassed market expectations, sending its shares higher.
Coles Sets a Strong Precedent
Coles reported its full-year results on August 25, delivering a strong performance that has set the tone for the Australian supermarket sector. The company's report highlighted several key achievements:
- Net Profit: A 13.7% surge in net profit after tax (NPAT) to A$1.26 billion, beating consensus estimates.
- Sales Growth: Group sales rose 2.8% to A$45.6 billion.
- Margin Expansion: Supermarket earnings before interest and taxes (EBIT) grew 12.2%, with margins expanding by 43 basis points to 5.7%.
- E-commerce: Digital sales jumped 26.4% to A$5.6 billion.
The only significant weak spot for Coles was its liquor division, where EBIT fell by 47.8% to A$59 million, prompting plans to close 30 stores in fiscal 2027. Following the results, Coles' shares gained 2.43%.
Woolworths' Profitability Under Scrutiny
 Ad
Investors will be closely watching whether Woolworths can demonstrate a similar ability to manage costs and improve profitability. While consensus estimates project Woolworths will report revenue of A$71.64 billion and earnings per share (EPS) of A$1.26, the trend in analyst forecasts has been negative, with EPS estimates cut by 8.4% over the past year.
The central challenge for Woolworths is its net margin, which stood at a thin 1.4% in the prior fiscal year. This figure contrasts sharply with Coles, which has maintained a stable net margin between 2.4% and 2.7% for the last five years. Woolworths' ability to close this profitability gap will be a key focus of its August 26 announcement.
Market Outlook and Key Metrics
Valuation metrics highlight the different positions of the two grocery giants. Woolworths' high trailing price-to-earnings (P/E) ratio of 79.4x reflects a historically depressed earnings base rather than a premium valuation. In contrast, Coles trades at a more modest 30.3x trailing P/E and offers a higher dividend yield.
Key variables for investors to watch in Woolworths' report include its supermarket margin trajectory, e-commerce growth, the performance of its Dan Murphy's liquor business, and its financial guidance for fiscal 2027. With a high debt-to-equity ratio of 371.1%, the company's plans for capital allocation and dividends will also be under intense scrutiny. A Coles-style beat could help rerate the stock, while another margin disappointment could extend its recent underperformance.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.