
Story
Warner Bros. Discovery Downgraded by Seaport on Merger Delay, Weaker Outlook
Summary
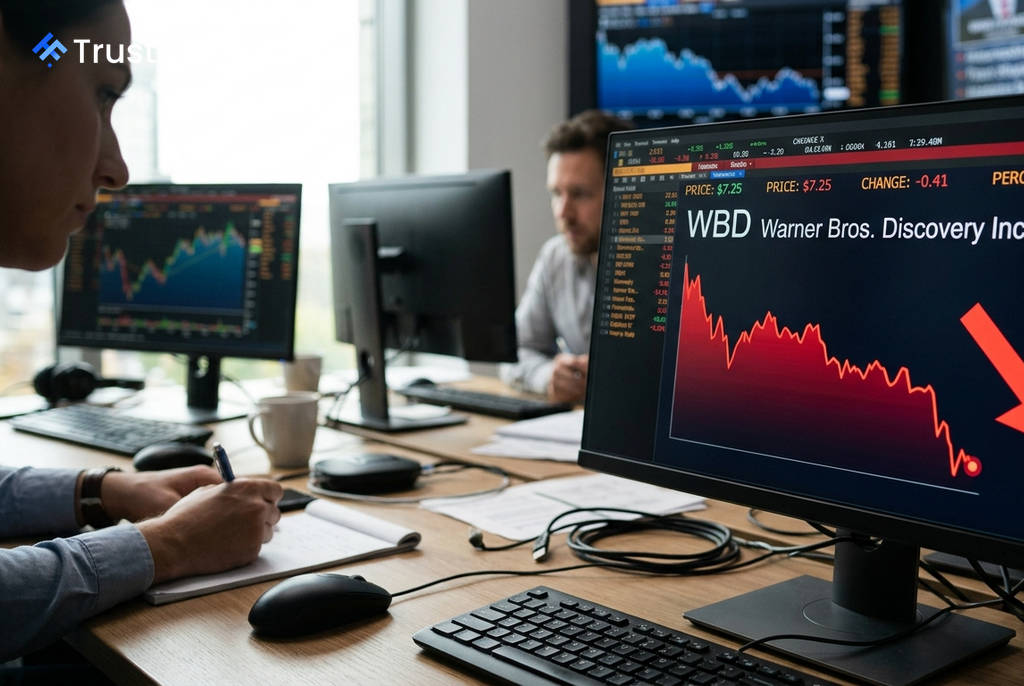
Seaport Research Partners lowered its rating on Warner Bros. Discovery to Neutral from Buy, citing significant delays in the proposed Paramount Skydance merger and a weaker near-term financial forecast.
Seaport Research Partners has downgraded Warner Bros. Discovery (NASDAQ: WBD) to Neutral from a Buy rating, citing increased uncertainty surrounding the timeline for its proposed acquisition by Paramount Skydance. The brokerage noted that the prolonged delay diminishes the stock's near-term appeal for investors.
Merger Delay Clouds Upside
The primary driver for the downgrade is Paramount Skydance's decision to postpone the acquisition until as late as June 1, 2027. According to Seaport, this delay, intended to address legal challenges from the Writers Guild and several U.S. state attorneys general, introduces a long period of uncertainty for shareholders.
While Seaport acknowledged that the deal still offers a potential upside of roughly 20% to the agreed cash consideration, the extended timeline makes other investment opportunities more compelling. The firm stated that the delay also postpones critical integration efforts and the realization of expected cost savings, or synergies, from the merger.
Financial Forecasts Trimmed
 Ad
Compounding the merger concerns, Seaport also lowered its financial estimates for Warner Bros. Discovery, pointing to recent underperformance and a challenging advertising environment. The firm highlighted two key factors for the revised forecast:
- Box Office Disappointment: The film *Supergirl* generated only about $124 million at the global box office, a figure Seaport noted was insufficient to cover production costs, let alone marketing expenses.
- Soft Ad Market: A softer advertising backdrop is expected for the summer, partly due to the absence of major sports programming like the FIFA World Cup and the NBA and NHL playoffs.
Reflecting these headwinds, Seaport reduced its second-quarter 2026 revenue estimate for the company by $236 million to $9.07 billion. The firm also cut its adjusted EBITDA forecast by $219 million to $1.83 billion for the same period.
Read next
More on Stocks
European Telecoms Face AI-Driven Price Pressure, Bank of America Warns
Bank of America analysts report that while AI agents could increase customer churn for European telecom operators by simplifying price comparisons, the technology also offers powerful tools for sales and personalized customer retention.

ShinyHunters Hackers Renew Attacks on Oracle PeopleSoft Flaw, Google's Mandiant Reports
Google's cybersecurity unit, Mandiant, reports that the hacking group ShinyHunters has resumed and adapted its exploitation of a known vulnerability in Oracle's PeopleSoft enterprise software, targeting organizations that failed to apply a full security patch.
Manulife Stock Climbs, Supported by Cross-Border Investor Optimism
Shares of Manulife Financial gained on Tuesday, buoyed by a strong performance in U.S. markets rather than any specific company news. The stock's move is also supported by a bullish technical posture and positive analyst ratings.
Escondida Union Rejects BHP's Bid to Pause Talks After Fatal Accident
A union at the world's largest copper mine, Escondida, has rejected a request from operator BHP to postpone contract negotiations following a fatal accident earlier this week. The union accused the company of using the tragedy to delay the collective bargaining process.