
Story
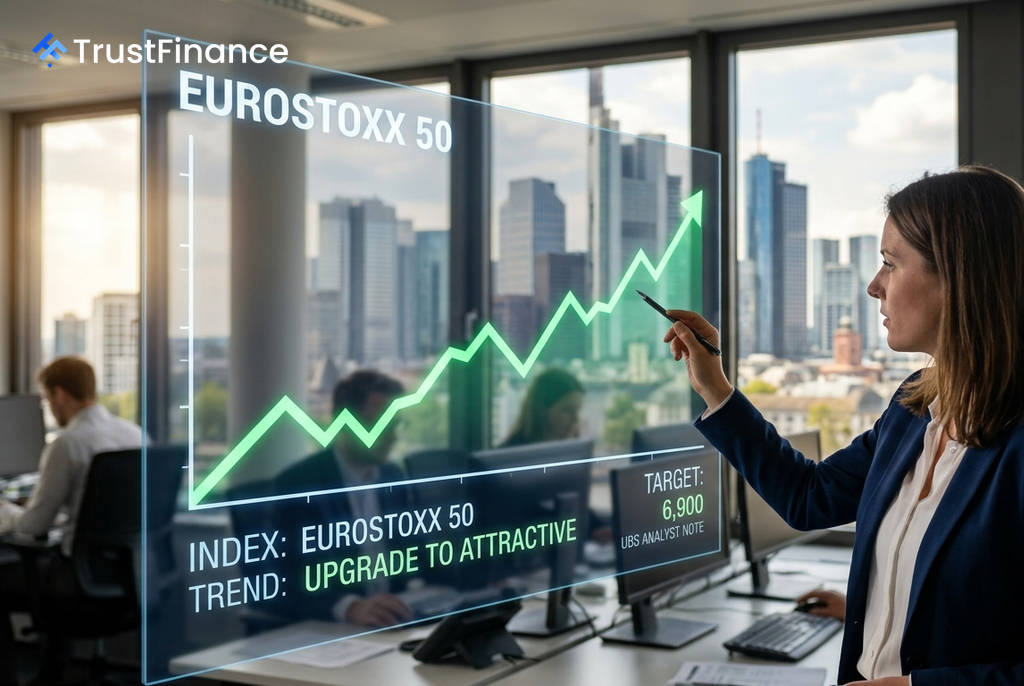
UBS Upgrades European Equities to 'Attractive,' Lifts EuroStoxx 50 Target
Summary
The investment bank raised its rating on European stocks, citing an improving cyclical outlook and fading uncertainties, while also increasing its price target for the EuroStoxx 50 index.
UBS has upgraded its view on European equities to Attractive from Neutral, anticipating that markets will shift focus to the region's strengthening cyclical outlook as geopolitical and energy-related risks diminish. In a note to clients, the bank's strategists also raised their June 2027 target for the EuroStoxx 50 index to 6,900 from 6,600.
A More Pro-Cyclical Stance
The new target for the EuroStoxx 50 implies a potential gain of approximately 10% from current levels, supplemented by an estimated dividend yield of 3.0%, according to the bank. The strategic shift involves becoming "more procyclical in our regional selections," strategists led by Matthew Gilman wrote.
This adjustment includes several specific ratings changes:
- Upgraded to Attractive: The Eurozone, Europe overall, and the banking sector.
- Downgraded to Neutral: The more defensive markets of Switzerland and the real estate sector.
Rationale for the Upgrade
UBS's more bullish outlook is founded on the end of a three-year period of earnings stagnation in the Eurozone. The bank forecasts 8% earnings growth for the EuroStoxx 50 this year and 15% growth in 2027. "The key debate is no longer whether earnings will recover, but how far and for how long this cycle can run," the strategists noted.
 Ad
The bank expects the market rally to broaden. While gains this year have been concentrated in stocks linked to artificial intelligence investment, UBS stated that returns for the rest of the market are up less than 5% year-to-date. It anticipates that more cyclical and previously underperforming sectors will begin to participate in the upward trend.
Spotlight on European Banks
The European banking sector received a standout upgrade to Attractive. UBS cited a combination of solid loan demand, elevated capital markets activity, a stable interest rate environment, and reasonable valuations. The strategists highlighted that the sector's return on equity has reached levels not seen since before the 2008 global financial crisis.
Furthermore, the bank pointed to the sector's strong capital positions, which it believes can support continued shareholder returns, including a projected dividend yield of 4.8%. Beyond banks, UBS also favors European consumer discretionary, industrials, and German equities, the latter for its industrial exposure and significant fiscal spending plans.
Key Risks to the Outlook
UBS also outlined several potential risks to its optimistic forecast. These include a slowdown in global growth, a reacceleration of inflation that could prompt more restrictive monetary policy, an escalation in geopolitical tensions, or a deterioration in the outlook for AI-related investment that could lead to valuation compression.
Read next
More on Stocks
Waste Management Sector Reshaped by AI and Urbanization Trends
The waste management industry is capitalizing on dual AI-driven catalysts—e-waste disposal and internal automation—alongside secular growth from urbanization, creating distinct opportunities among key players despite premium valuations.

Uniper Inks Decade-Long Deal for Sustainable Aviation Fuel with Arcadia eFuels
German utility Uniper has signed a long-term agreement to purchase 40,000 metric tons of synthetic sustainable aviation fuel annually from U.S.-based Arcadia eFuels. The deal, one of the largest of its kind, aims to meet growing demand and upcoming EU mandates for cleaner aviation fuels.
Canadian Stock Futures Decline as Gold Prices Weaken
Futures for Canada's main stock index fell Wednesday, pressured by a drop in gold prices amid a stronger U.S. dollar. Investors are also monitoring the market impact of new AI technologies and geopolitical developments.
UBS Initiates CoreWeave at 'Buy,' Citing Underappreciated AI Demand and 40% Upside
UBS launched coverage on AI infrastructure provider CoreWeave with a contrarian 'Buy' rating and a $120 price target, arguing that concerns over leverage are peaking and the market is underestimating the durability of AI compute demand.