
Story
S&P Revises Cemex Outlook to Positive on Lower Debt, Strong Earnings
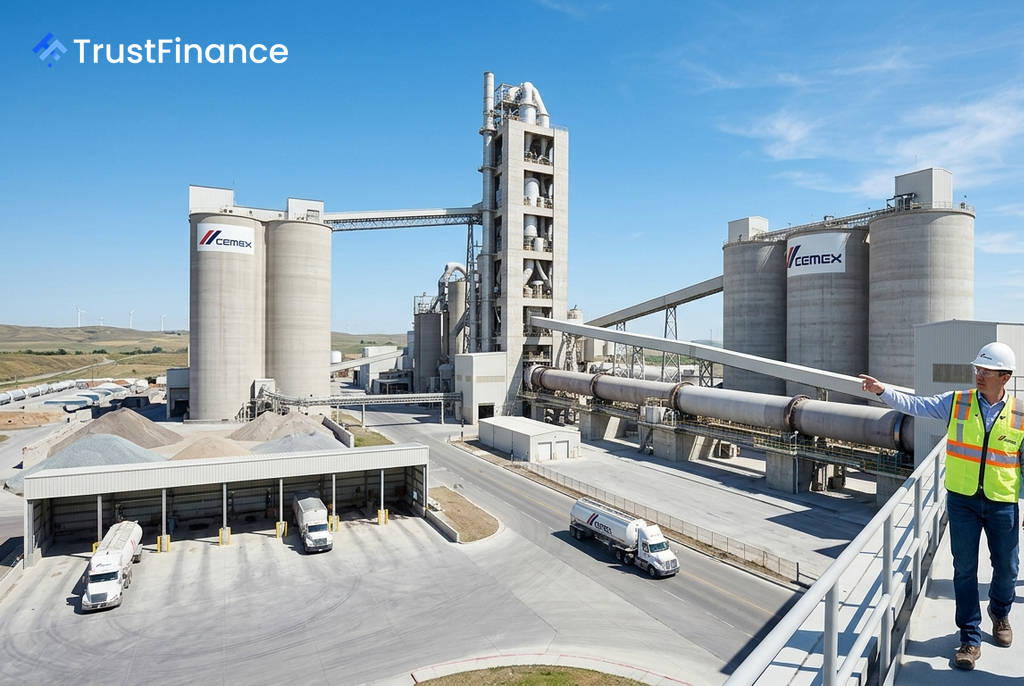
S&P Global Ratings has revised its outlook on Cemex S.A.B. de C.V. (NYSE:CX) to positive from stable, citing the cement producer's strong operational performance and success in reducing its debt load. The agency affirmed Cemex's 'BBB-' issuer credit rating, indicating that a future upgrade is possible if the company maintains its improved financial metrics.
Key Metrics Drive Outlook Change
The revision was underpinned by Cemex's strengthening credit metrics. In the first half of 2026, the company reported an S&P Global Ratings-adjusted debt-to-EBITDA ratio of 2.5x, with funds from operations (FFO) to debt near 30%. Free operating cash flow to debt stood above 15%.
This improved financial position was driven by robust earnings growth. Cemex's EBITDA grew nearly 27% in the first half of 2026 compared to the same period last year, reaching $1.8 billion. S&P projects the company's full-year EBITDA will rise to almost $3.6 billion in 2026 and $3.7 billion in 2027.
Proactive Balance Sheet Management
Cemex has recently undertaken several strategic financial actions. In June, the company completed a series of liability management transactions, including issuing $1.5 billion in new senior notes and opening a $3.0 billion revolving credit facility. These moves helped repay approximately $1.8 billion in bank loans and redeem $1.0 billion of subordinated perpetual notes.
 Ad
Alongside its deleveraging efforts, Cemex is also returning more capital to shareholders. The company raised its ordinary dividend by 40% to $180 million for 2026 and initiated a share buyback program of up to $500 million over the next three years. Additionally, Cemex plans to divest part of its Colombia operations for $485 million by the end of 2026.
Path to an Upgrade
The positive outlook reflects the potential for a credit rating upgrade over the next 12 to 24 months. S&P stated that an upgrade could occur if Cemex consistently maintains its adjusted debt-to-EBITDA ratio below 3.0x and its FFO-to-debt ratio above 30% through industry cycles.
Conversely, the ratings agency noted it could revise the outlook back to stable if the company's debt-to-EBITDA ratio rises back to 3.0x or above on a sustained basis, or if its FFO-to-debt metric falls below the 30% threshold.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.