
Story
SK Hynix Shares Fall Below IPO Price Amid Market Shocks, New Chinese Rivalry
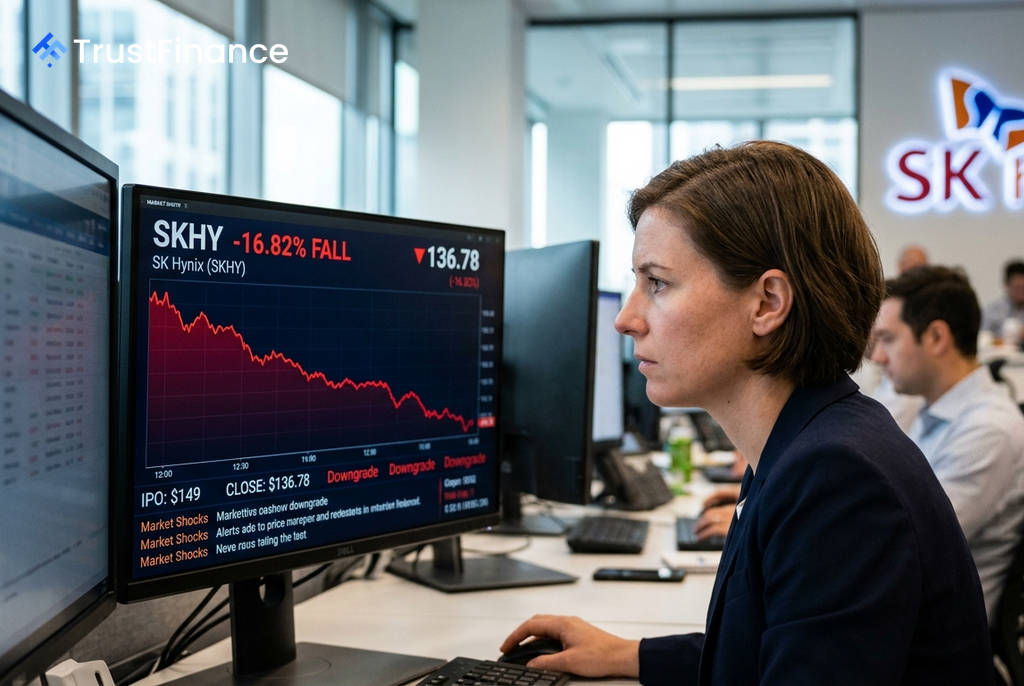
SK Hynix's U.S.-listed shares have fallen below their initial public offering price just weeks after the company's landmark $26.5 billion Nasdaq debut, as a confluence of technical trading pressures, macroeconomic shocks, and the emergence of a major Chinese rival soured investor sentiment.
A 'Perfect Storm' Hits Post-IPO
The American Depositary Receipts (ticker: SKHY), which began trading on July 10, have been hit by a wave of selling that pushed the stock below its $149 IPO price. The decline follows what was the second-largest U.S. listing in history.
The initial selloff was partly driven by a structural arbitrage opportunity, according to market analysts. The ADRs debuted at an approximate 50% premium to the company's shares in Seoul (000660), prompting investors to sell the home-listed stock and rotate into the U.S. shares, which compressed the valuation gap.
This pressure was compounded when several Korean securities firms trimmed their Q2 profit estimates, citing softer-than-expected memory pricing. Shortly after, on July 16, the Bank of Korea delivered an unexpected 25 basis point interest rate hike, its first in over three years, further weighing on the market.
Chinese Competitor Rattles Sector
The most significant blow to the stock came on July 27 with the blockbuster IPO of Chinese DRAM producer CXMT on Shanghai’s STAR Market. Shares of CXMT surged 466% on their first day of trading, giving the company an instant market capitalization of $483 billion.
 Ad
Investors immediately interpreted the successful listing as the arrival of a formidable new competitor in the global memory chip industry. The news sent SK Hynix shares tumbling 7.47% on Monday, deepening its post-IPO losses.
Analysts Point to Underlying Strength
Despite the recent volatility, some analysts argue the selloff is overdone and point to the company's strong underlying business fundamentals. In a note, Morgan Stanley described Monday's price drop as a "compelling entry point" for investors.
Key strengths cited by market proponents include:
- A dominant 56% to 58% global market share in high-bandwidth memory (HBM), a critical component for AI accelerators.
- Last-twelve-months revenue growth of 85% and a gross margin of 68% as of the first quarter of 2026.
- A forward price-to-earnings ratio of approximately 5.8x, which is considered low for a market leader.
Barclays, which initiated coverage with an Overweight rating and a $330 price target, also noted that potential U.S. manufacturing expansion could help close a valuation gap with rival Micron Technology over time. Investors are now looking to the company's second-quarter earnings report, scheduled for July 29, for a potential catalyst to reverse the recent downward trend.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.