
Story
Mizuho Initiates Coverage on European Oil Majors, Favoring BP and TotalEnergies Over Shell
Summary
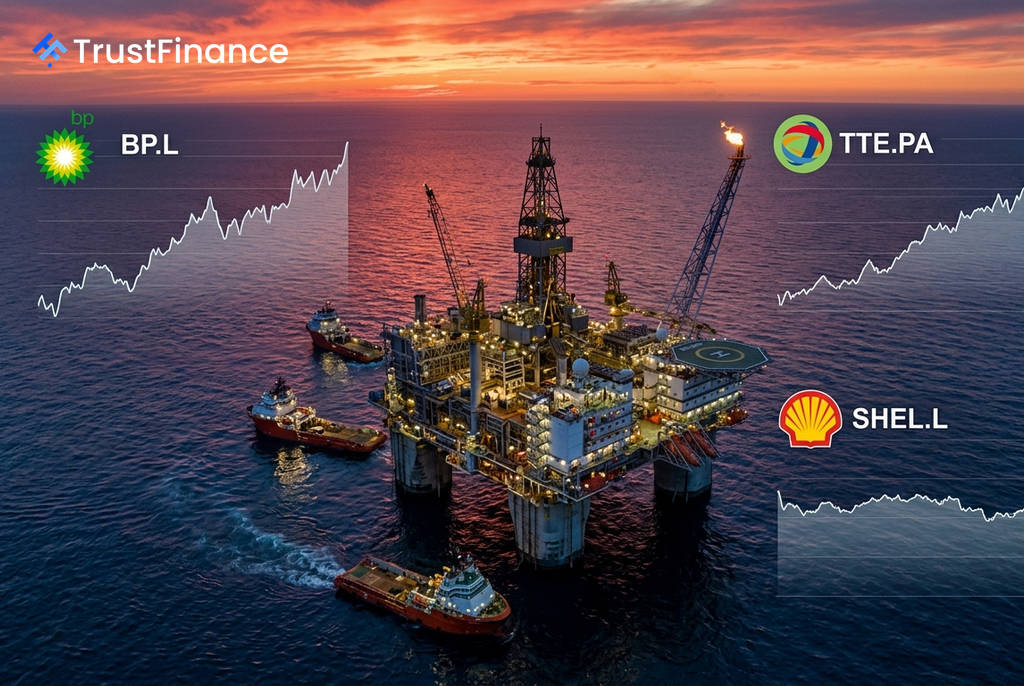
Mizuho Securities has launched coverage on three European energy giants, assigning 'Outperform' ratings to BP and TotalEnergies while starting Shell with a 'Neutral' rating, citing varying prospects in valuation, reserve life, and strategy.
Mizuho Securities initiated equity research coverage on European integrated oil companies BP, TotalEnergies, and Shell, seeing the most upside potential in BP and TotalEnergies.
In a note to clients, analysts led by Nitin Kumar assigned 'Outperform' ratings to BP and TotalEnergies, while Shell was initiated with a 'Neutral' rating, reflecting what the firm views as a more balanced risk-reward profile for the latter.
Analyst Ratings and Price Targets
Mizuho's initial ratings and price targets for the companies' American Depositary Shares (ADS) are as follows:
- BP (NYSE:BP): Outperform, with a $51 price target.
- TotalEnergies (NYSE:TTE): Outperform, with a $103 price target.
- Shell (NYSE:SHEL): Neutral, with a $98 price target.
The Bull Case for BP and TotalEnergies
 Ad
Mizuho's positive outlook on BP is based on its above-peer Return on Capital Employed (ROCE), focus on debt reduction, high dividend yield, and a discounted valuation compared to its peers. The firm noted BP's progress in its strategic reset back toward oil and gas and expects an "accelerated rate of change" under incoming CEO Meg O’Neill. The primary concern cited for BP is its reserve depth, with an organic reserve replacement rate of about 0.6x from 2023-2025, below the peer average of 0.8x.
For TotalEnergies, Mizuho highlighted a "differentiated, dual-engine growth strategy" that balances hydrocarbon investments with low-carbon power generation. The analysts pointed to the company's deep resource base, with roughly 12 years of reserve life, and its industry-low production costs of $4.81 per barrel of oil equivalent (boe). Mizuho estimates the company's Integrated Power segment could be worth $14-$15 per share and expects it to become free-cash-flow positive by 2027.
A Cautious Stance on Shell
Shell received a Neutral rating due to what Mizuho describes as a "balanced risk-reward." The firm acknowledged Shell's strengths, including its leadership position in global liquefied natural gas (LNG) and its sector-leading cash returns, with a total cash return yield estimated at 9.2% for 2026 versus a peer average of 6.5%.
However, the analysts remained on the sidelines due to several offsetting factors. These include a below-peer reserve life, higher balance-sheet leverage, and potential integration risks associated with its pending $16.7 billion acquisition of ARC Resources.
Read next
More on Stocks
Citi Lowers Burberry Price Target on Softer Luxury Demand
Citi analysts reduced their price target for Burberry to £14.6, citing a challenging macroeconomic environment and slowing growth in the luxury sector, though they maintained a "Buy" rating on the stock.
SharonAI Stock Falls Over 6% in 'Sell the News' Reaction to Partnership
Shares of SharonAI Holdings are declining sharply, erasing recent gains as investors take profits following a new partnership announcement. The drop comes amid broader market weakness and ongoing concerns about the company's high valuation.

Aehr Test Systems Stock Slides Amid Insider Selling and Analyst Concerns
Shares of Aehr Test Systems are extending recent losses amid a combination of factors, including the lingering impact of an analyst downgrade, recent insider selling, and a weak broader market for technology stocks.
Aurora Innovation Stock Slides Over 8% in 'Sell the News' Reaction to Investor Day
Shares of the autonomous trucking firm are declining despite positive operational updates, as investors take profits amid broader market weakness and concerns over the company's financials.