
Story
Fitch Revises Moody's Outlook to Positive, Citing Strong Cash Flow and Market Position
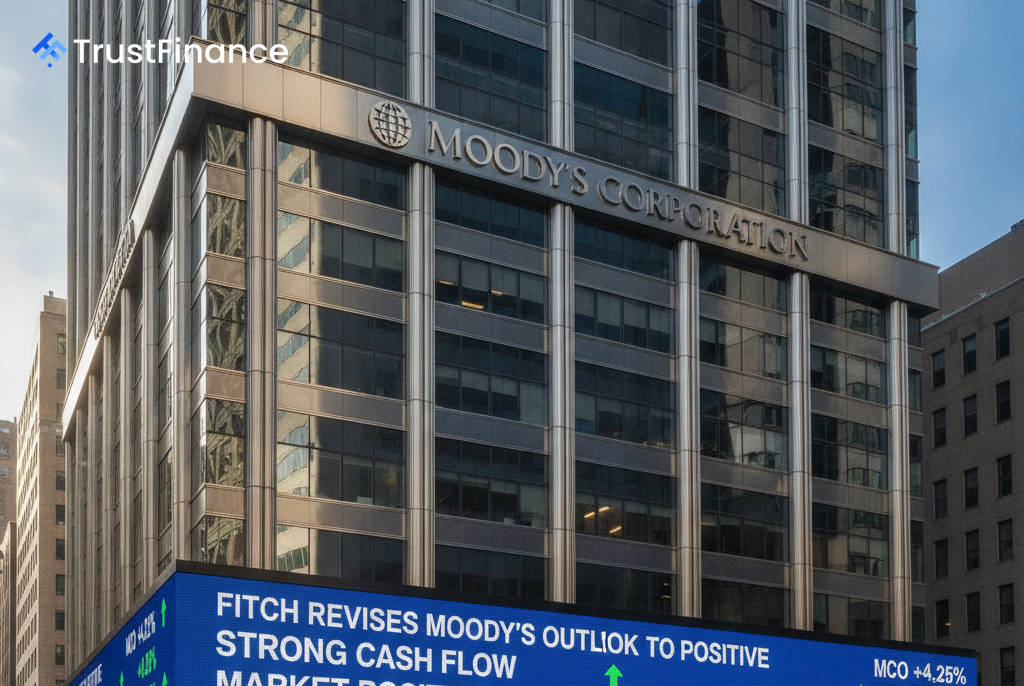
Fitch Ratings has revised its outlook on Moody’s Corporation (NYSE:MCO) to Positive from Stable, while affirming the company's Long-Term Issuer Default Rating (IDR) at 'BBB+'. The rating agency also affirmed Moody's Short-Term IDR and commercial paper ratings at 'F1'.
Rationale for the Positive Outlook
According to Fitch's announcement, the outlook revision is supported by a combination of Moody's strong financial profile and strategic positioning. The agency highlighted several key factors driving its decision:
- Strong Market Position: Moody’s stands as a leading global credit rating agency with significant scale.
- Financial Health: The company demonstrates sustained and expanding free cash flow, ending 2025 with EBITDA leverage of 1.7x. It also maintains a strong liquidity position with over $2 billion in cash, an undrawn revolver, and a $1 billion commercial paper program.
- Successful Diversification: The Moody's Analytics division provides a substantial source of recurring revenue, now accounting for more than 40% of the company's total revenue and enhancing its overall credit profile.
- Profitability: The business model is described as highly profitable and cash-generative, benefiting from low capital intensity and strong operating leverage.
 Ad
Future Expectations and Potential Upgrade
Fitch noted that a ratings upgrade could occur if Moody’s continues its growth trajectory while maintaining its current margin and free cash flow profile. The agency's rating assumptions project that Moody's will keep its financial metrics stable even as it continues to return significant capital to shareholders via dividends and share repurchases.
Fitch's forward-looking assumptions include Moody's 2026 results being in line with management expectations. For future years, the agency anticipates EBITDA margins will be sustained above 50% and that EBITDA leverage will remain below 2.0x, with revenue growth tapering to lower single digits from 2027 onward.