
Story
EPAM Valuation Model Shows 62% Upside, Diverging Sharply From Analyst Consensus
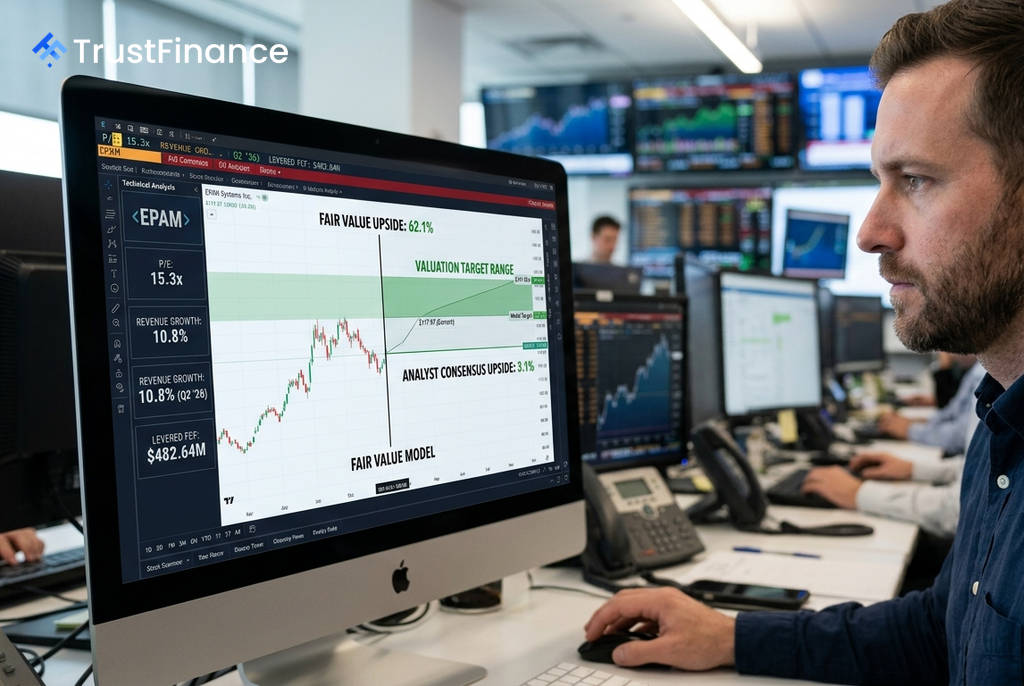
EPAM Systems (NYSE: EPAM) has been identified as a leading "underappreciated" technology stock by a quantitative screen, which suggests a potential fair-value upside of 62.1%. This optimistic valuation, however, stands in stark contrast to the consensus among Wall Street analysts, who project an upside of only 3.1%, creating a significant valuation mismatch, according to an analysis by Investing.com.
Valuation and Growth Metrics
The screening model highlighted EPAM based on a combination of valuation, growth, and size criteria. The IT services company exhibits a compelling profile for investors seeking growth at a reasonable price, combining double-digit revenue growth with a moderate price-to-earnings multiple.
Key financial metrics underpinning the model's assessment include:
- Price-to-Earnings (P/E) Ratio: 15.3x
- Revenue Growth: 10.8%
- Levered Free Cash Flow: $482.64 million
EPAM's ability to convert earnings into substantial free cash flow is a crucial factor supporting the model's bullish valuation case. However, the disconnect with analyst targets suggests the market is pricing in significant headwinds.
The Analyst Disconnect
 Ad
The primary risk highlighted by the analysis is the exceptionally wide gap between the model's valuation and the targets set by market analysts. This discrepancy suggests fundamentally different assumptions about the company's future performance. The model may be pricing in a more robust and rapid recovery in corporate IT and consulting spending than analysts currently anticipate.
Conversely, the cautious analyst consensus could reflect concerns about a prolonged slowdown in demand for IT services or other sector-specific challenges. The sustainability of EPAM's revenue growth and cash flow will be critical in determining which forecast proves more accurate.
Broader Tech Context
EPAM was not the only large technology firm to show such a divergence in the screen. Other prominent companies also exhibited a wide gap between model-based fair value and analyst expectations, pointing to a broader theme of valuation disagreement in the sector.
For comparison, the screen also surfaced:
- Adobe (ADBE): A 59.8% modeled upside versus a -12.6% downside implied by analyst targets.
- Accenture (ACN): A 60.3% modeled upside versus a -1.6% downside implied by analyst targets.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.