
Story
Benefit Systems Stock Has 25% Upside, JPMorgan Says in New Coverage
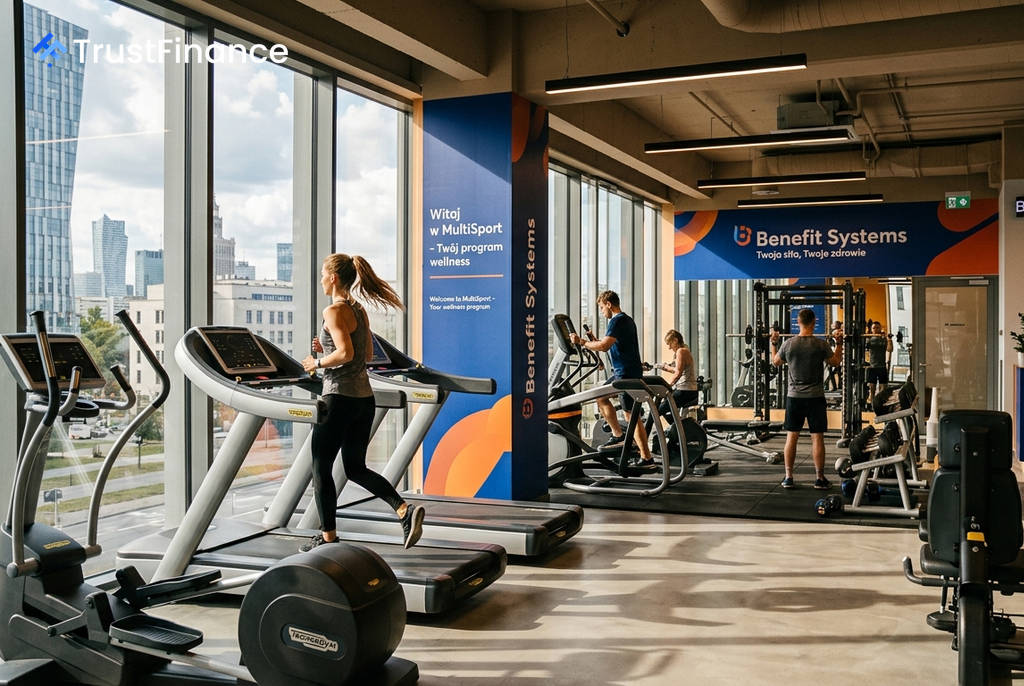
JPMorgan has initiated coverage on Polish employee benefits provider Benefit Systems with an Overweight rating, citing a potential upside of approximately 25%. In a note to clients, the bank set a December 2027 price target of 6,685 Polish zloty per share for the company.
Benefit Systems, a Warsaw-headquartered company with a market capitalization of $4.8 billion, specializes in non-wage employee benefits centered around its MultiSport card and a network of fitness clubs across Central and Eastern Europe and Türkiye. JPMorgan's price target is derived from a 10-year discounted cash flow model.
The Investment Thesis
JPMorgan's positive outlook rests on what it calls four structural growth drivers, arguing the company is "well positioned to leverage its vertically integrated model and leadership in sports cards." The bank highlighted the company's B2B platform, which is increasingly supported by its own network of fitness clubs.
The key growth factors identified by the bank include:
 Ad
- Low Market Penetration: Fitness participation in Benefit Systems' core markets is between 3%-9%, significantly below Western Europe (19%) and the U.S. (25%).
- Dominant Position: The company holds a commanding 83%-85% share of the Polish sports card market, with further growth potential.
- Consolidation Opportunity: A fragmented fitness club market offers opportunities for the company to expand its 2%-9% market share across its geographies.
- International Expansion: The bank projects strong international EBITDA growth from 2025-2030, forecasting 30% for foreign EU markets and 34% for Türkiye, compared to 13% for Poland.
Financial Outlook and Valuation
JPMorgan forecasts an 18% compound annual growth rate (CAGR) for adjusted EBITDA between 2027 and 2029, which is nearly double the 9%-10% expected for its peers. The bank also projects sector-leading group margins of 33% by 2027 and a sustainable dividend yield of 2%-4% between 2026 and 2030.
Despite the stock's significant year-to-date rally of about 52%, JPMorgan's analysts believe the current valuation "does not fully reflect the company’s superior operating and capital-return profile." The note identified several upcoming catalysts for investors to watch, including the September 7 record date for the 2025 dividend, third-quarter operating data in early October, and the release of third-quarter results on November 19.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.