
Story
Bending Spoons Gets Mixed Wall Street Ratings Post-IPO Amid Valuation Concerns
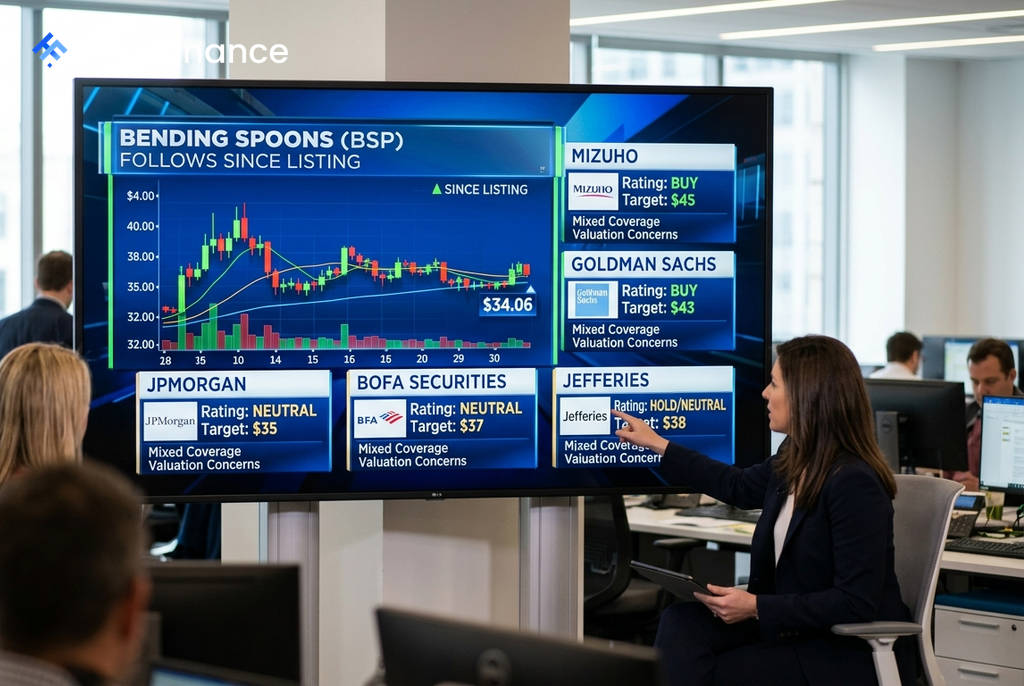
Bending Spoons (NASDAQ: BSP) received a mixed reception from Wall Street as six major investment firms initiated coverage, revealing a sharp divide on the company's valuation and its ambitious M&A-focused growth strategy. While the average price target of approximately $39 suggests a potential 14% upside from its recent price of about $34.06, a majority of analysts adopted a cautious stance.
A Divided Street
The initial analyst ratings show a split between outright bulls and a larger camp of skeptics. The price targets span a significant range, from a high of $45 to a low of $35, reflecting different outlooks on the company's ability to execute its strategy at scale.
- Goldman Sachs: Buy, $43 price target
- Mizuho: Outperform, $45 price target
- JPMorgan: Neutral, $35 price target
- BofA Securities: Neutral, $37 price target
- Jefferies: Hold, $38 price target
- Evercore ISI: In Line, $36 price target
The Bull and Bear Thesis
The core of the debate centers on whether Bending Spoons can successfully deploy billions in capital for acquisitions. The bullish case, led by Mizuho and Goldman Sachs, is a bet on the company's proven playbook of acquiring and optimizing digital subscription businesses. Mizuho's Street-high $45 target is based on projections that the company will deploy $4 billion in M&A in 2026 and another $4.3 billion in 2027.
 Ad
Conversely, the more cautious majority points to the stock's demanding valuation. BofA Securities noted that the current share price already factors in $9 billion of hypothetical M&A through 2028, an outcome that is far from guaranteed. This sentiment is echoed by JPMorgan's $35 target. Trading at a price-to-earnings (P/E) ratio of 271x, the stock carries high expectations for near-perfect execution.
What It Means for Investors
The prevalence of "Neutral" or "Hold" ratings from four of the six firms is unusual for a fresh wave of IPO coverage, which often skews positive. This indicates that while analysts acknowledge the company's successful business model, they see the current valuation as largely reflecting its future potential, leaving little room for error.
The key catalyst for Bending Spoons' stock will be its ability to meet the aggressive M&A deployment targets projected by its supporters. Investors will be closely watching whether the company can convert its M&A pipeline into tangible growth to justify its premium valuation.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.