
Story
Xiaomi Tipped as AI Home Appliance Leader by Morgan Stanley
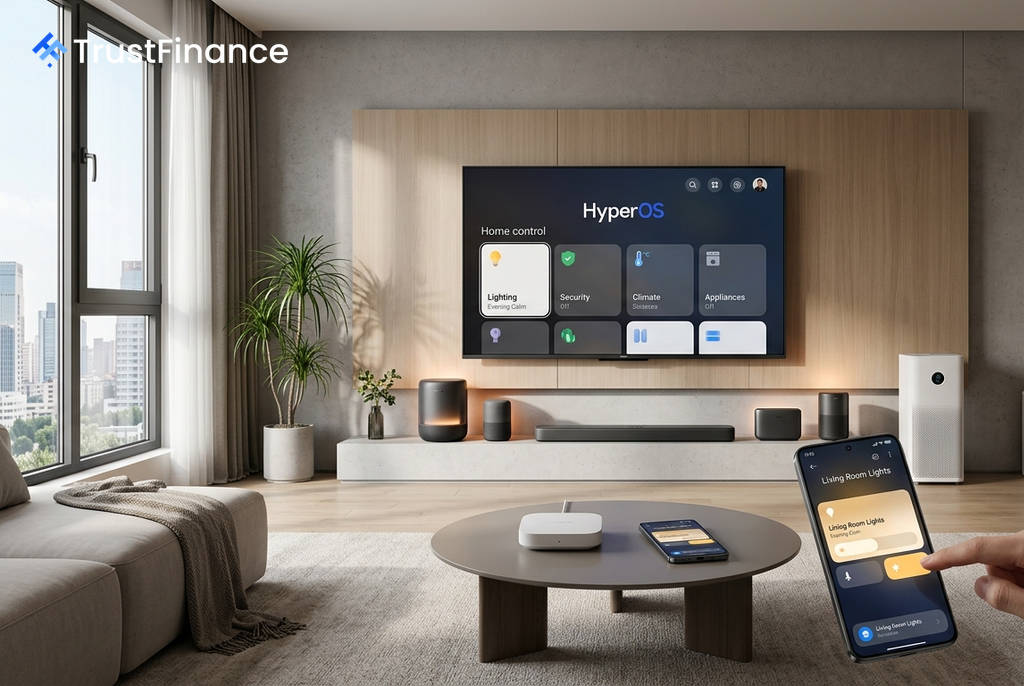
Xiaomi is well-positioned to emerge as a dominant force in China's burgeoning AI-powered home appliance market, according to a new analyst report from Morgan Stanley. The investment bank reiterated its Overweight rating on the tech company's stock, maintaining a price target of HK$45 and citing Xiaomi's integrated product ecosystem as a key competitive advantage.
Bullish Market Outlook
Morgan Stanley forecasts significant growth in the sector, projecting that China’s AI home appliance market will expand from its current size of roughly $123 billion to about $150 billion by 2030. This growth is expected to be driven by increased consumer adoption of connected devices and higher average selling prices.
For Xiaomi specifically, the bank's model predicts its domestic AI home appliance revenue could surpass RMB 200 billion by 2035. The report suggests that the company's overseas revenue in the segment could eventually exceed that figure, highlighting international expansion as another critical long-term growth driver.
The Ecosystem Advantage
Central to Morgan Stanley's positive thesis is Xiaomi's integrated "Human + Car + Home" strategy. The company's ability to connect a vast portfolio of devices—including smartphones, wearables, televisions, and electric vehicles—through its HyperOS platform is seen as a major differentiator.
 Ad
Key strengths highlighted in the report include:
- A Unified User Experience: The ecosystem creates opportunities to increase customer spending by seamlessly integrating multiple devices.
- Massive User Base: With over one billion connected devices globally, Xiaomi has a large, established network to cross-sell new products and deepen customer engagement.
- Synergistic Strategy: The firm's strategy is expected to create powerful synergies across its product lines, strengthening its market position against traditional appliance manufacturers.
Beyond Hardware and Near-Term Risks
Morgan Stanley's analysts believe the market underestimates the long-term value of Xiaomi's investments in artificial intelligence. The company's ongoing development of proprietary large language models (LLMs) and AI agents could become a more significant valuation driver as earnings growth accelerates through 2027 and 2028, supporting product differentiation and premium pricing.
The report also addressed near-term investor concerns about rising memory chip costs, viewing them as manageable. According to the note, Xiaomi's management has already outlined mitigation measures, including price increases and product mix adjustments, with cost pressures anticipated to ease in the second half of 2026.